

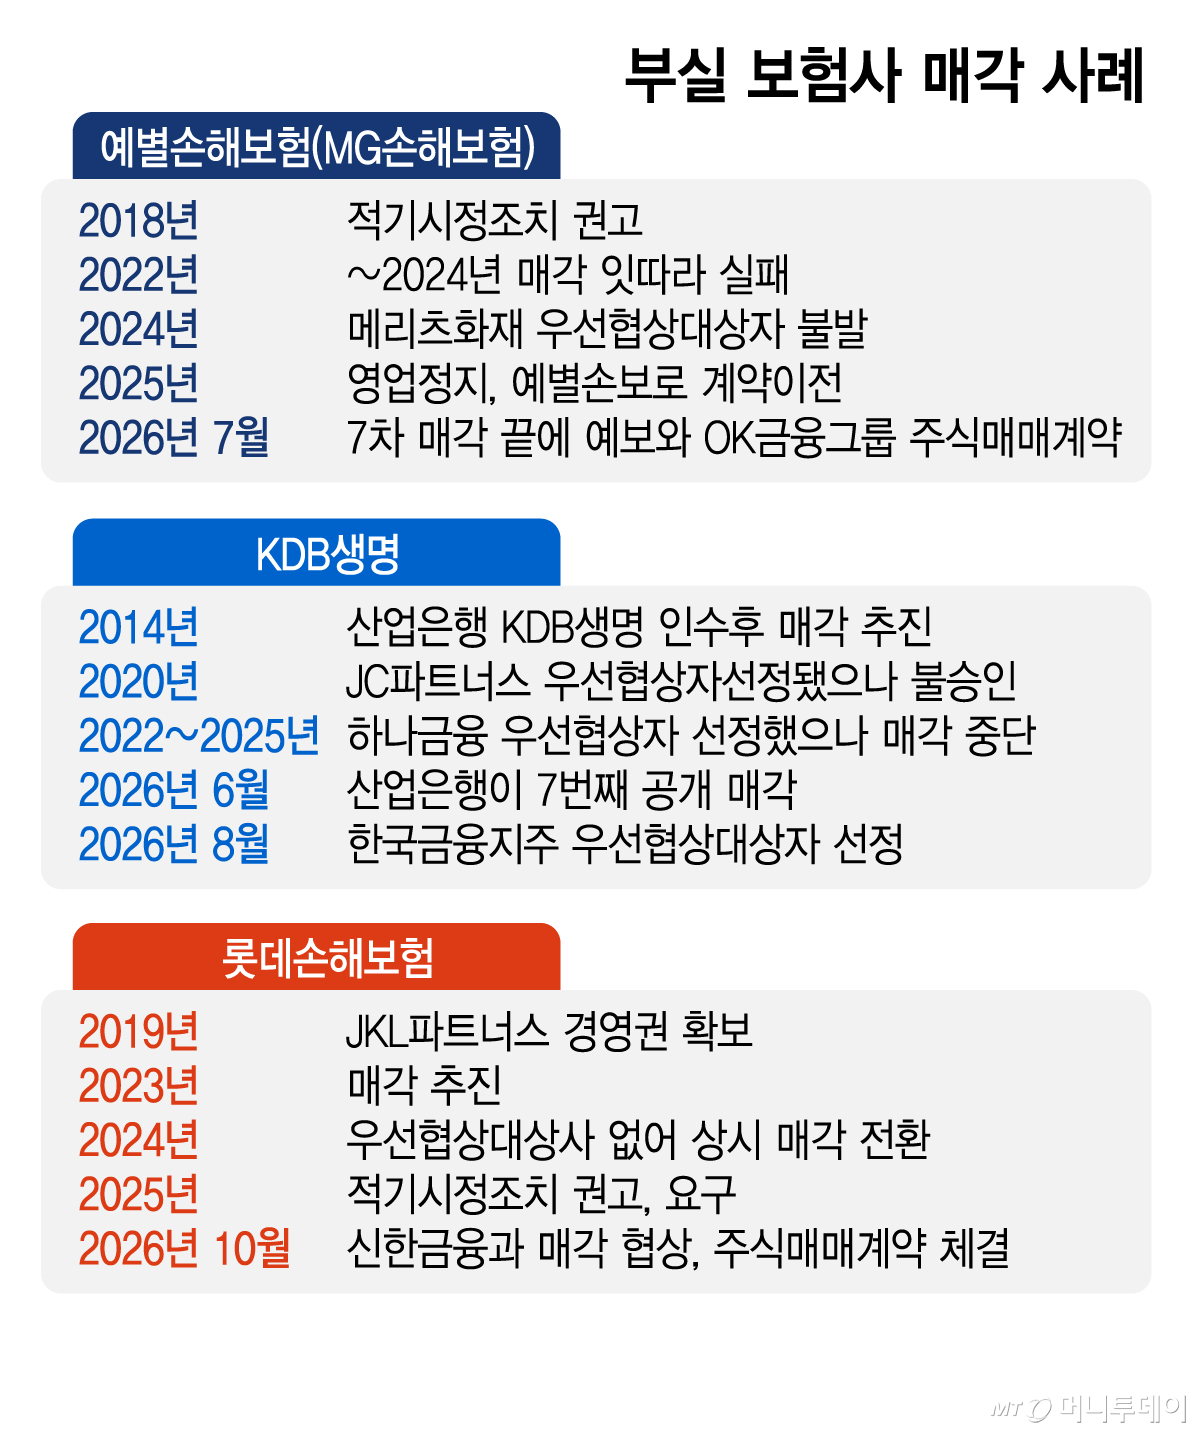
As Yeobyeol General Insurance, KDB Life, and Lotte General Insurance have struggled to find new owners after multiple failed sale attempts, financial authorities have begun preparing an insurance company resolution system for proactive restructuring. It is pointed out that the side effects are severe, with support funds from the Korea Deposit Insurance Corporation swelling to the 1st trillion won range due to repeated delays in resolving underperforming insurance companies, and the capital increase burden on the state-owned policy bank, the Korea Development Bank, expanding to the 2nd trillion won range.
According to financial authorities on the 21st, the Financial Services Commission and the Korea Deposit Insurance Corporation have recently launched a kickoff meeting and a task force (TF), respectively, to prepare an improvement plan for a proactive and swift insurance company resolution system. This can be seen as a de facto restructuring plan for underperforming insurance companies. The financial authorities are considering options such as introducing a 'contract transfer system' that transfers the insurance contracts of underperforming insurers to other insurance companies while changing contract terms, such as increasing premiums, and establishing a 'run-off insurance company' that maintains and manages only existing contracts without new business operations and pays out insurance benefits.
The reason financial authorities are preparing an insurance company resolution system is that the exit of 'zombie insurance companies' is not easy under the current system. This is because problems remain unresolved, with it taking nearly 10 years from when an underperforming insurance company receives prompt corrective action (management improvement measures) from financial authorities to actual sale or exit.
In the case of Yeobyeol General Insurance (formerly MG General Insurance), for which OK Financial Group signed a share purchase agreement (SPA) earlier this month, the sale failed six times after it received prompt corrective action in 2018. The underperformance grew due to the long delay in the sale. The Korea Deposit Insurance Corporation had to sign a contract to transfer Yeobyeol General Insurance to OK Financial while adding approximately 114 billion won in additional support funds.
KDB Life, for which Korea Financial Investment Group was selected as the priority negotiation candidate, is similar. The Korea Development Bank attempted seven sales since 2014 but failed every time. It is estimated that the bank has invested more than 2 trillion won in KDB Life over the past decade or so.
To swiftly resolve 'zombie' insurance companies, financial authorities are considering introducing a contract transfer system and run-off insurance companies. If the contract transfer system is introduced, it will be possible to reduce the burden on acquirers by changing contract terms. Coverage scope and premiums can be adjusted according to the acquirer's wishes, enabling faster resolution compared to before, while policyholders may have to bear some losses.

 in FINANCE
