

Samsung Electronics unveiled its next-generation memory technologies, including HBM5 (8th-generation high-bandwidth memory), and the outcomes of collaborations with global tech companies at an event in Silicon Valley, U.S.
Samsung Electronics announced on the 13th that it introduced its strategy for next-generation memory and storage technologies aimed at enhancing AI infrastructure performance, as well as the results of collaborations with global partners, at the 'OCP (Open Compute Project) Global Summit 2026,' which opened on the 12th (local time). The event brings together global IT, semiconductor, server, and data center companies to discuss open hardware technologies, standardization, and the direction of AI infrastructure innovation.
Samsung Electronics participated as a Diamond sponsor, the highest tier, for the second consecutive year, under the theme 'Architecting AI Systems - Innovations. Together.'
In particular, at this event, the company revealed three technological directions: △high-performance memory such as HBM5 and custom HBM, △CXL-based memory expansion technology, and △data storage and management technologies utilizing next-generation SSDs (Solid State Drives).
Alongside these announcements, Samsung Electronics jointly demonstrated a CXL-based memory expansion solution with AMD and exhibited collaboration outcomes with global AI companies, including Groq LPU (Language Processing Unit) wafers and the NVIDIA Groq 3 LPX (Language Processing Accelerator) system.
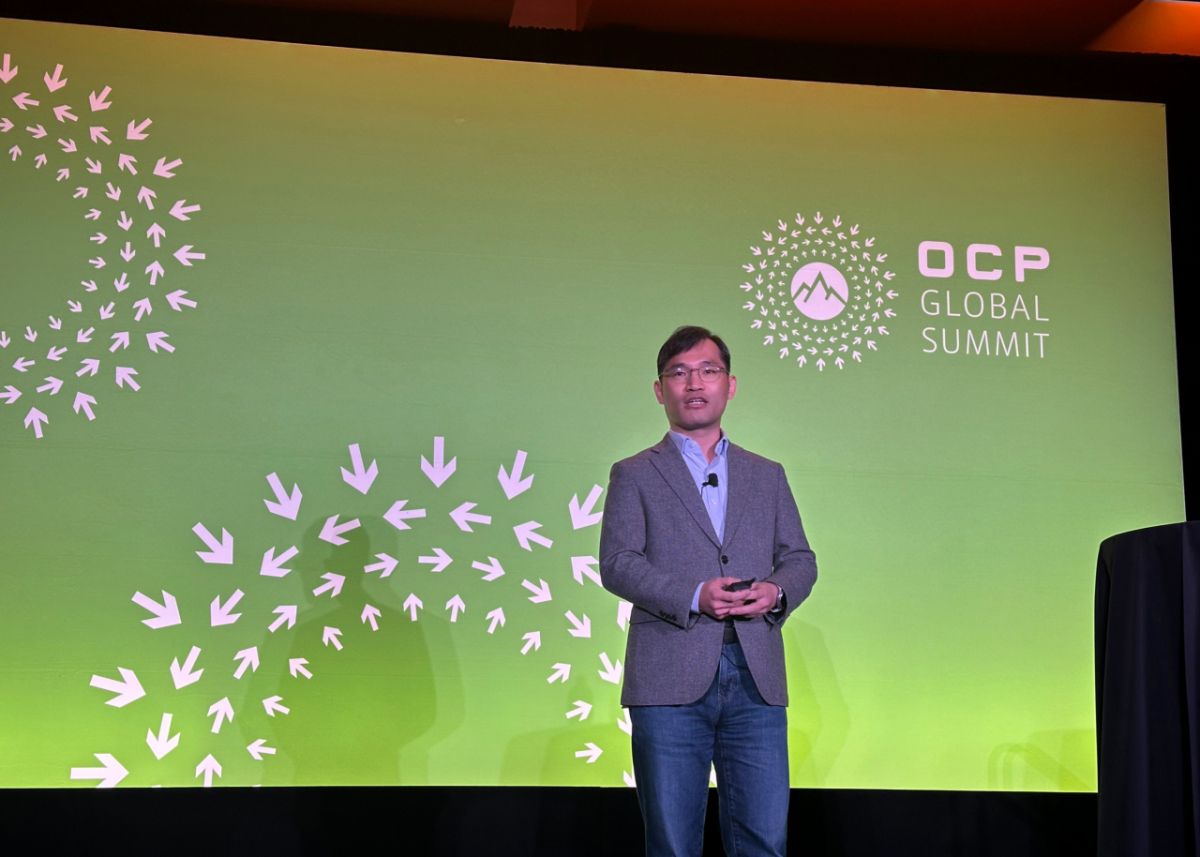
Shim Ho-jun, executive vice president of Samsung Electronics' AE (Application Engineering) team, delivered a keynote presentation explaining that as AI models grow larger and the volume of data to be processed during inference, along with KV cache capacity (temporarily stored results for subsequent operations), increases, it is becoming increasingly important not only to expand memory bandwidth but also to enhance memory capacity and data storage and management technologies to improve AI system performance.
He then outlined a three-pronged technical strategy to address these challenges: △Speed, △Memory Expansion, and △Data Persistence. High-performance memory addresses speed, CXL-based technology handles expansion, and storage technology ensures data persistence.
Furthermore, Samsung Electronics is expanding its collaboration on technology verification by conducting co-design with global customers and partners from the early stages of development, aiming to optimize the entire AI system—including CPUs (Central Processing Units), GPUs (Graphics Processing Units), memory, and storage—rather than merely improving the performance of individual memory products.
The company also jointly demonstrated a CXL-based memory expansion solution with AMD. This represents the outcome of technical collaboration aimed at flexibly expanding the memory capacity of AI systems. The company noted that this is significant as it involves verifying the technology in real system environments with a global computing platform company and expanding cooperation to improve AI infrastructure performance.
Meanwhile, based on its technological capabilities and industry-leading production capacity, Samsung Electronics maintains the top position in both the global DRAM and NAND flash markets. According to market research firm Counterpoint Research, Samsung Electronics recorded a 39% market share by revenue in the global DRAM market in the second quarter of this year, securing first place. SK Hynix and Micron held shares of 26% and 25%, respectively. Additionally, according to market research firm TrendForce, Samsung Electronics also ranked first with a 29.3% share of the global NAND market during the same period.
In terms of production capacity, Omdia forecasts that Samsung Electronics' DRAM production capacity this year will be approximately 8.175 million wafers annually on a 300mm wafer basis. This scale surpasses SK Hynix's approximately 6.66 million and Micron's approximately 3.6 million. For NAND, Omdia forecasts Samsung Electronics' annual wafer production volume at approximately 4.77 million wafers this year, expected to significantly lead SK Hynix and Solidigm's combined approximately 2.79 million.

 in INDUSTRY
