
memory semiconductor (hereinafter memory) prices are expected to continue their upward trend in the fourth quarter of this year. This is because demand for both DRAM and NAND flash (hereinafter NAND) continues to exceed supply, driven by aggressive capital investment by global CSPs (large cloud service providers). As the memory boom is set to continue next year as well, the earnings growth trajectory of Samsung Electronics and SK Hynix is also expected to steepen.
According to industry sources on the 15th, global investment bank Bernstein recently forecast in a report that memory contract prices will rise further in the fourth quarter of this year. Previously, DRAM and NAND contract prices rose by nearly 20% each in the third quarter compared to the previous quarter. Bernstein analyzed, “While the price increase rate in the third quarter slowed compared to the second quarter, it still exceeds past peak levels,” adding that “market demand is continuously outpacing supply.”
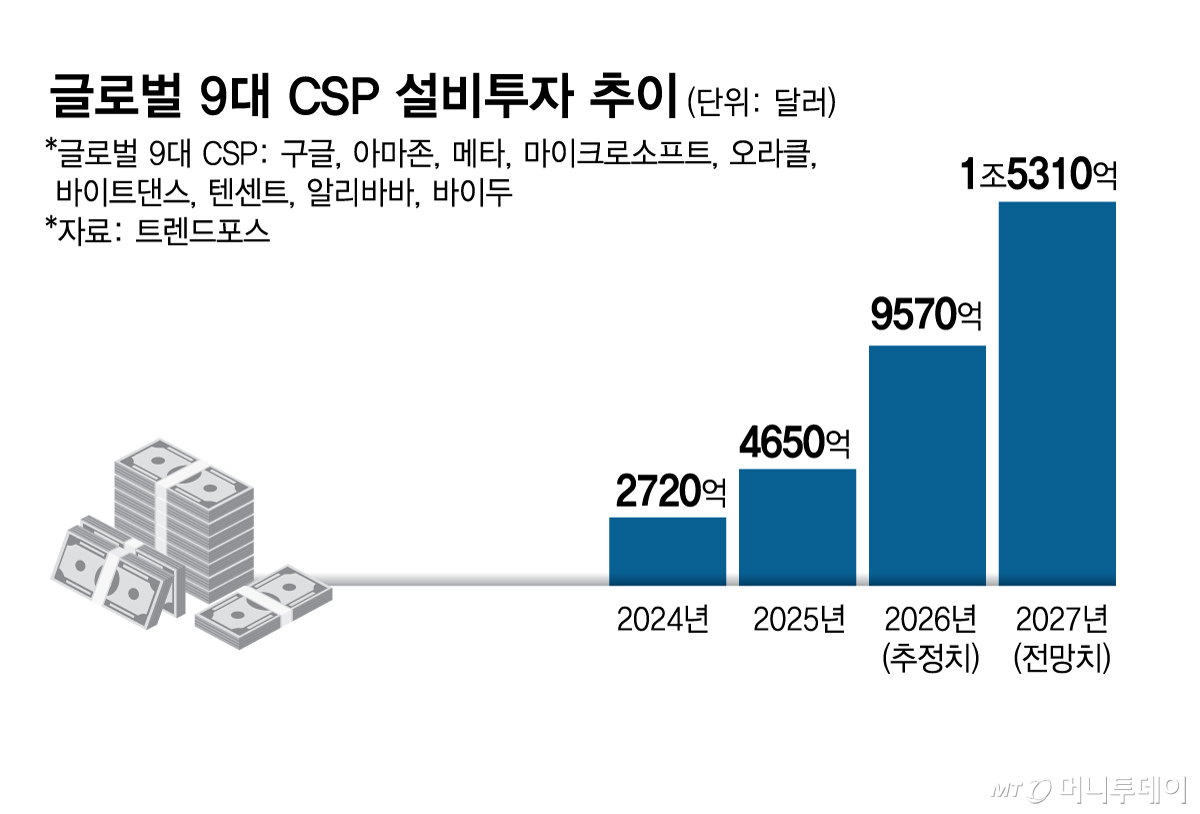
The expansion of AI (artificial intelligence) server investment by global CSPs is cited as a key factor behind rising memory prices. Market research firm TrendForce expects the capital expenditure (CAPEX) scale of the world’s top 9 CSPs, including Google, Amazon, and Meta, to reach $957 billion (approximately 1290.8016 trillion won) this year. It predicted that this figure will expand to $1.531 trillion (approximately 2065.0128 trillion won) next year. The firm also revised its forecast for the capital expenditure growth rate next year upward from 50% to 60%.
Recent remarks by NVIDIA have also bolstered this outlook. Colette Kress, NVIDIA’s Chief Financial Officer (CFO), stated during the earnings announcement conference call for the second quarter of fiscal year 2027 that “the magnitude of memory price increases has exceeded initial expectations and will be even higher next year,” adding that “the memory shortage is largely due to the construction of AI infrastructure itself.”
The supply-demand imbalance in the memory market is also deepening. According to TrendForce, DRAM lead times (the period from order to delivery) have reached 20 weeks. Suppliers are also showing signs of shifting some of their production capacity for PCs to servers to meet robust server DRAM demand from U.S. CSPs. NAND lead times have also extended to 16 weeks as major CSPs proactively secure volumes of enterprise solid-state drives (eSSDs). Considering that typical lead times are around 8 weeks, this represents a doubling in duration.
The memory supply shortage is expected to persist for the next two years. Global investment bank Barclays expects DRAM demand to exceed supply by 13.9% in the fourth quarter of 2027. It also forecast that NAND demand will exceed supply by 8.3% in the first quarter of 2028, reaching the peak level of the supply-demand gap.
As memory prices remain firm, expectations for the earnings of Samsung Electronics and SK Hynix are rising. According to financial information provider FnGuide, the combined operating profit consensus estimate (average forecast from securities firms) for the two companies this year was tallied at 534.2083 trillion won. This is expected to increase to 964.3392 trillion won next year.
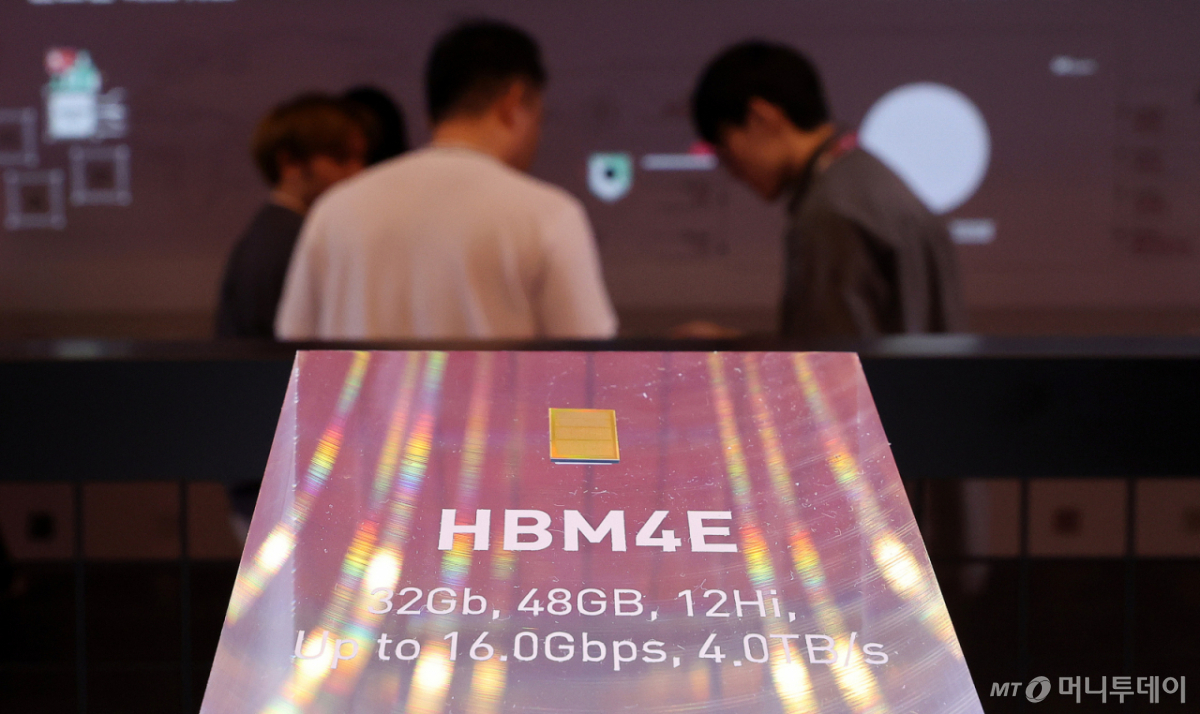
In particular, with the full-scale shipment of next-generation AI accelerators from NVIDIA and AMD beginning next year, HBM (high-bandwidth memory) revenue is also projected to expand. TrendForce expects the blended average selling price (Blended ASP) of HBM next year to rise by 121% compared to this year. Since HBM consumes more wafers than standard DRAM, increased production could lead to a decrease in commodity DRAM supply and higher prices.
An industry official stated, “While past memory booms were driven by consumer demand for PCs and smartphones, this time AI data center investment is propelling the market,” adding that “if global CSPs continue to expand their investments, the memory boom phase will likely last longer than expected.”
 in INDUSTRY

