

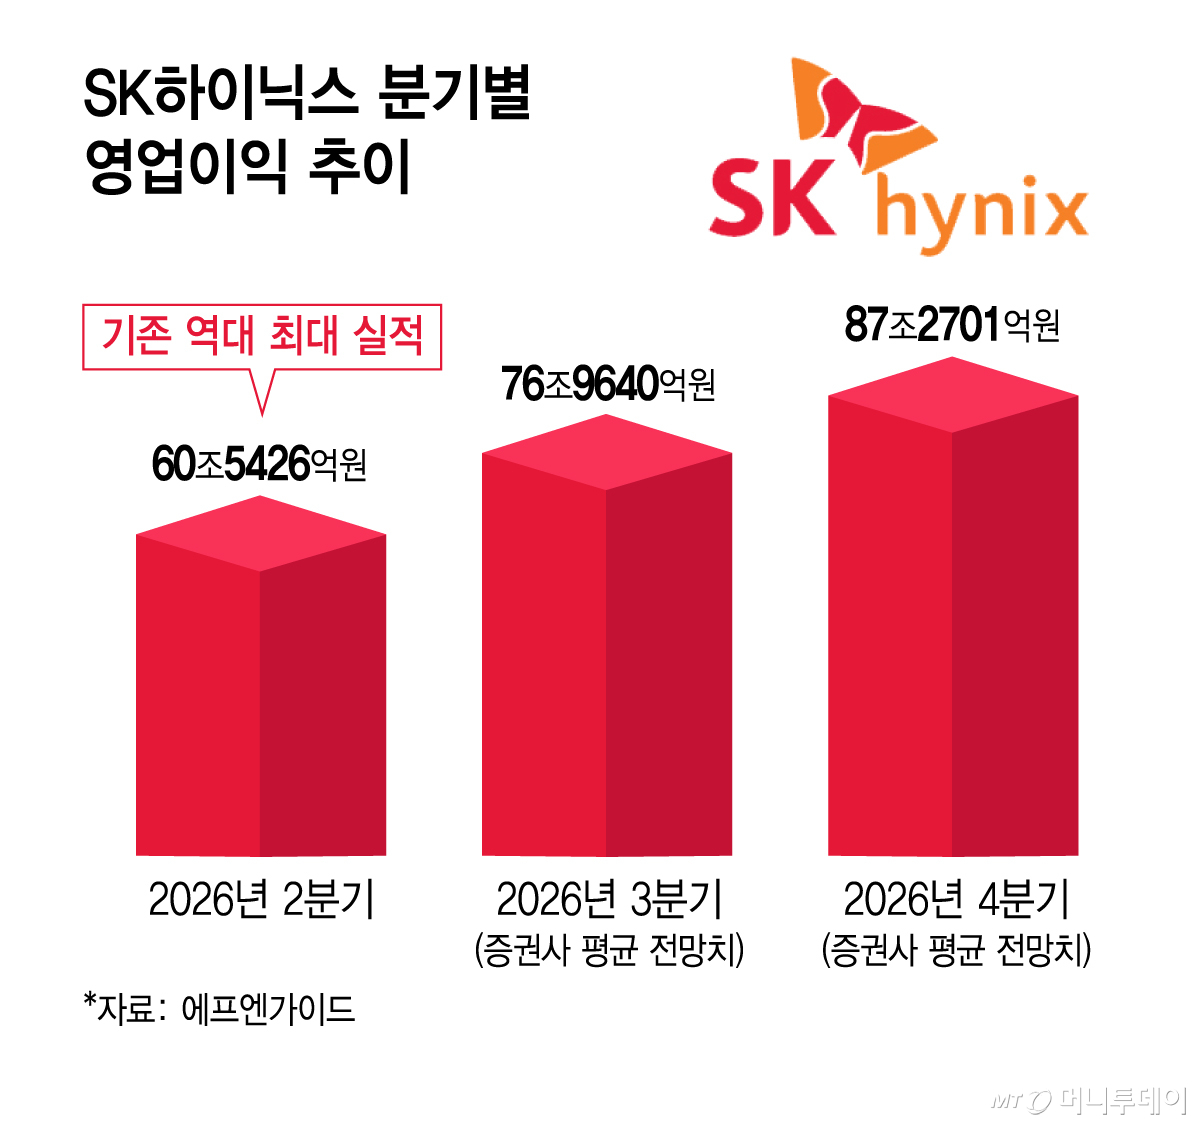
Following Samsung Electronics, SK hynix is also expected to set a new all-time high for its performance in the third quarter of this year. With revenue from HBM4 (6th generation) being fully reflected, the company’s growth trajectory is poised to gain further momentum based on its leading position in the HBM (High Bandwidth Memory) market. Observers also predict that the continued strength in memory semiconductor prices will offset the burden of a declining won-dollar exchange rate.
According to financial information provider FnGuide, SK hynix’s consensus estimate for operating profit in Q3 this year stands at 76.964 trillion won. If this figure materializes, it would mark the sixth consecutive quarter of record-breaking results since Q2 last year. The projected operating profit margin is expected to reach approximately 78.4%. SK hynix is scheduled to announce its Q3 earnings on the 29th.
The expansion of HBM4 revenue is cited as a key driver behind the strong performance. This is due to the full reflection of HBM4 sales for Nvidia’s next-generation AI (Artificial Intelligence) platform, "Vera Rubin," starting from Q3.
According to market research firm Counterpoint Research, SK hynix took the top spot in the global HBM market by revenue in Q2 last quarter with a 50% share, surpassing Samsung Electronics (33%) and Micron (18%). Global investment bank J.P. Morgan predicted that SK Hynix would account for the highest share of 54% among the three major memory makers in Nvidia’s HBM supply this year.
Prices for DRAM and NAND flash (hereinafter referred to as "NAND") are also on an upward trend. Meritz Securities analyzed that SK Hynix’s selling prices for DRAM and NAND rose by 22% and 15%, respectively, in Q3.
Kim Sun-woo, a researcher at Meritz Securities, said, "We believe the resilient recovery in SK Hynix’s shipment volumes and selling prices will lead to faster performance improvement compared to competitors." He added, "In Q2 last quarter, the company was held back by rising prices due to having the highest HBM sales ratio in the industry, but with the full-scale supply of HBM4, its contribution to profits is set to accelerate as well."
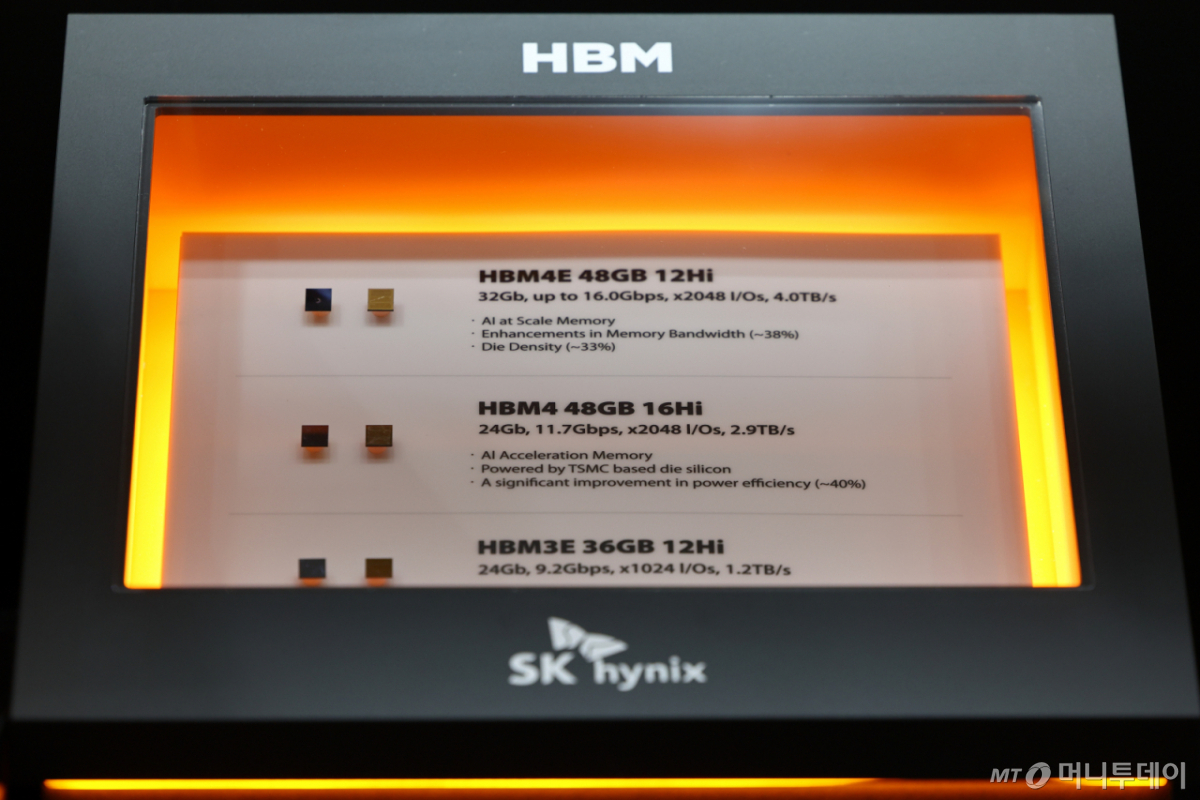
Despite the decline in the won-dollar exchange rate, the company is expected to maintain solid performance driven by the "memory supercycle (period of boom)." The won-dollar exchange rate has consistently remained in the 1,300-won range since the 21st of last month.
In its annual business report last year, SK hynix noted that a 10% drop in the won-dollar exchange rate would result in a decrease of approximately 1.2104 trillion won in net income before corporate tax. Son In-jun, a researcher at Eugene Investment & Securities, said, "We have revised our performance estimates downward to reflect the stronger won, but rising memory prices will offset this."
The upward trend in performance is expected to continue into Q4 as well. J.P. Morgan raised its forecast for the DRAM contract price increase rate in Q4 this year from the previous 3-8% to 10-15%. It also raised its forecast for the NAND contract price increase rate from 0-5% to 15-20%, predicting that strong memory prices will persist. The average selling price (ASP) of HBM4 is estimated to rise by 121% compared to last year through next year. The company also expects the selling price per GB (gigabyte) to reach a level of $3 to $5.
Driven by rising memory prices, expectations for SK hynix’s performance are also climbing. According to FnGuide, SK hynix’s consensus estimate for operating profit in Q4 stands at 87.2701 trillion won.
Meanwhile, SK hynix will also disclose plans for additional shareholder returns alongside its Q3 earnings announcement. The securities industry expects the funding source for these additional shareholder returns to exceed 30 trillion won.
Kim Rok-ho, a researcher at Hana Securities, stated, "Based on free cash flow, we anticipate an additional shareholder return funding source of at least over 30 trillion won," adding that "share buybacks and cancellations will be utilized more significantly than dividends."

 in INDUSTRY

