

The era of bank mortgage loan interest rates reaching "8% annually" is imminent. Following the Bank of Korea's two consecutive hikes to the base rate, bringing it to 3%, market forecasts even suggest the base rate could rise to 3.5% next year. With both market rates and banks' funding costs rising together, competition among banks over interest rates has vanished due to total household loan management, leaving borrowers facing a double burden of a "loan cliff" and high interest rates.
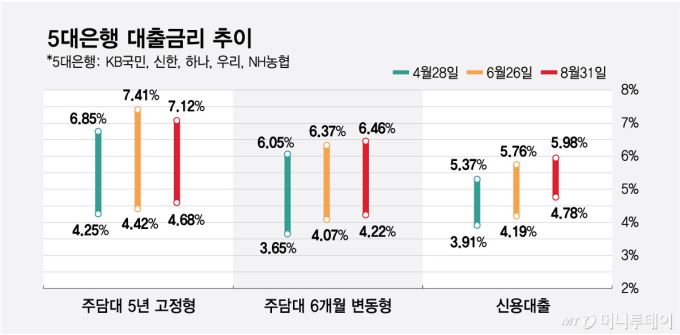
According to the financial sector on the 31st, mortgage loan interest rates for KB Kookmin, Shinhan, Hana, Woori, and NH NongHyup Bank were recorded as follows: fixed-rate loans ranged from 4.68% to 7.12%, variable-rate loans from 4.22% to 6.46%, and personal loans from 4.78% to 5.98%. The highest rate for fixed-rate mortgages has already surpassed 7%, while variable rates have climbed to the mid-6% range. The upper limit for personal loan rates is also eyeing above 6%.
The upward trend in loan interest rates since the second half of the year is clear. Compared to late April, when fixed-rate mortgage loans among the five major banks ranged from 4.25% to 6.85% and personal loans from 3.91% to 5.37%, interest rate levels have surged significantly in just four months. The average mortgage loan interest rate for new transactions by banks last month was also 4.48%, up 0.12 percentage points (P) from the previous month (4.36%). Rising for three consecutive months since May, this marks the highest level in two years and eight months since November 2023 (4.48%).
The first factor driving up loan interest rates is the base rate. The Bank of Korea Monetary Policy Board raised the base rate from 2.75% to 3.00% on the 27th, an increase of 0.25 percentage points. This marks the second consecutive monthly hike, and the first time in one year and nine months that the base rate has entered the 3rd% range.
The possibility of further hikes remains open. Markets anticipate that considering inflation, real estate prices, and exchange rates, the Bank of Korea will implement additional interest rate hikes within the year. Morgan Stanley forecasts that the Bank of Korea's base rate could rise to 3.5% in the first quarter of next year. President Lee Jae-myung also recently shared an article containing such forecasts, expressing concern over rising interest rates.
If the base rate rises to 3.5%, there is a possibility that the highest fixed-rate mortgage loan rates, currently in the 7th% range, could exceed 8%. This is because rising base rates increase banks' funding costs and are reflected in loan rates with a time lag.
The interest rate on five-year bank bonds (AAA·unsecured), which serves as the benchmark for fixed-rate mortgages, was recorded at an average of 4.351% on the 28th. Compared to 4.241% at the end of June, this represents a 0.11 percentage point increase since the second half of the year. With rising U.S. Treasury yields as well, it is not easy for domestic market rates to decline.
Pressure on variable-rate mortgages is also increasing. The COFIX (Cost of Funds Index), which serves as the benchmark rate for variable-rate mortgages, reflects banks' funding costs from deposits and time deposits, making it sensitive to base rate hikes. The COFIX based on new transaction amounts in July was 3.18%, up 0.13 percentage points from the previous month. Rising for four consecutive months since April, this marks the highest level in one year and seven months since December 2024 (3.22%).
Especially, there has been a sharp increase in borrowers choosing variable rates for new mortgages, which could amplify future interest rate shocks. Last month, the share of variable-rate loans among new mortgage loans by banks reached 68.1%, the highest level in about 12 years since February 2014. Borrowers who chose variable rates simply because rates were low are now fully exposed to the risk of future interest rate hikes.
Banks' added interest rates are also increasing borrowers' burdens. The average household loan spread for the five major banks last month was 3.266%, higher than the 3rd% base rate. Mortgage loan spreads also reached an average of 3.26%. Analysts suggest that with market rates rising and high spreads being maintained, final loan interest rates are being pushed up.
If mortgage loan rates reach 8%, the burden felt by borrowers is expected to increase sharply. If a borrower takes out a 300 million won loan for 30 years under an equal principal and interest repayment method, the monthly repayment would be about 1.43 million won at a 4% annual rate, but it jumps to about 267 million won at an 8% rate. This means an increase in burden of 770,000 won per month and over 9 million won annually.
Borrowers who took out five-year fixed-rate (hybrid) mortgages during the low-interest period of 2021 could face a "rate bomb" when rates are recalculated this year. If someone borrowed 300 million won for 30 years at a 3% annual rate in 2021 under an equal principal and interest repayment method, the monthly repayment was about 1.27 million won. After repaying for five years, if the remaining principal of approximately 267 million won is recalculated at a 7% annual rate, the monthly repayment would jump to about 1.89 million won; at 8%, it would reach about 2.06 million won. Even after repaying the principal for five years, the monthly burden increases by approximately 620,000 won and 790,000 won, respectively.
Even a 0.25 percentage point increase in the base rate creates a significant interest burden for all households. According to estimates by the Bank of Korea, if mortgage loan rates rise by 0.25 percentage points, the total annual interest burden for all borrowers would be about 18 trillion won, and the average interest amount per borrower would increase from 5.843 million won to 6.139 million won, a rise of 296,000 won. A simple calculation assuming the 0.50 percentage point base rate hike in the previous month and this month is fully reflected in loan rates results in an annual increase of about 592,000 won.
Interest rates are rising, yet the threshold for loans remains high. Although financial authorities have partially relaxed their target for total household loan management in the second half of the year, banks find it difficult to actively increase loan supply due to annual targets and prudence management. Critics point out that if loan demand surges, banks can adjust the growth rate by reducing preferential rates or raising spreads, making it hard to expect "interest rate competition" among banks.

 in FINANCE

