

Three internet-only banks are pursuing divergent strategies in personal business loans. Toss Bank, which entered the business loan market first, has reduced its outstanding balance and prioritized asset quality management. In contrast, KakaoBank and K bank have aggressively expanded their portfolios through collateral-based lending, increasing by over 2 trillion won each within two years to surpass Toss Bank.
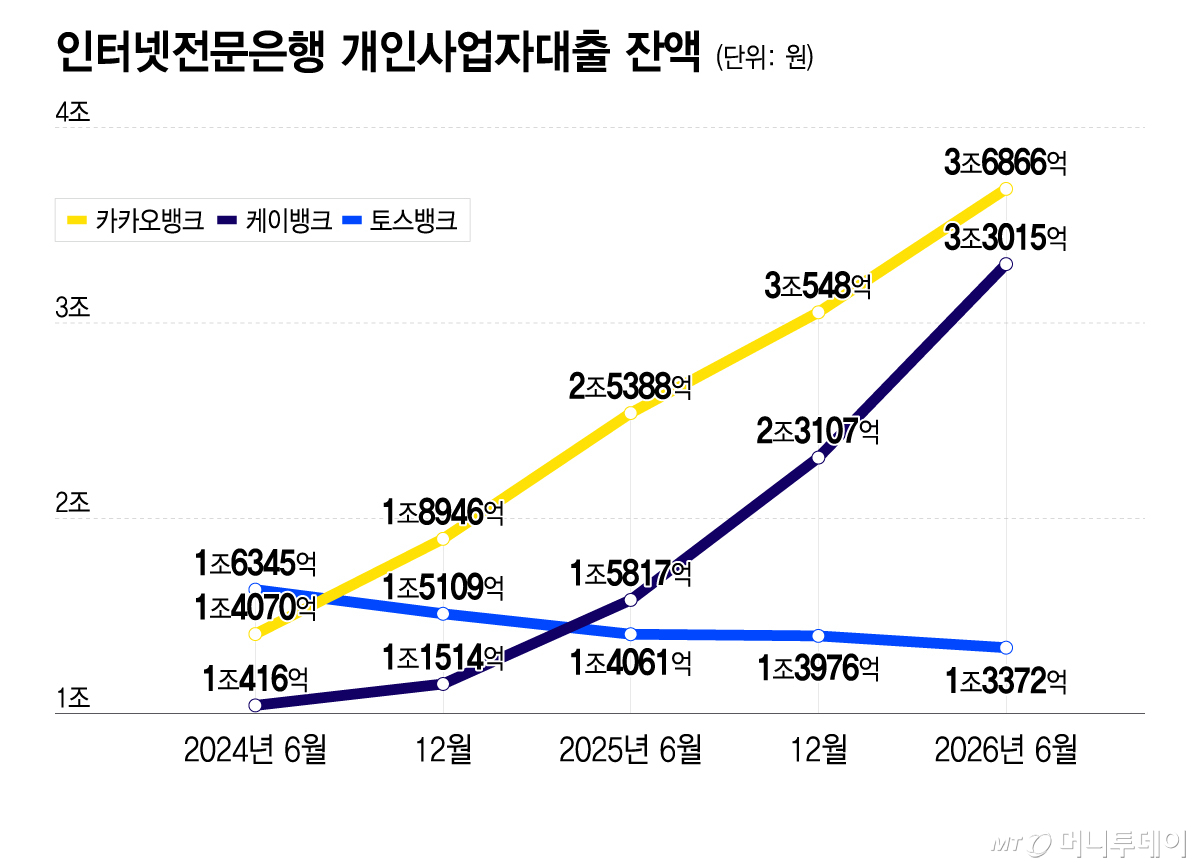
According to financial industry data released on the 2nd, Toss Bank's business loan balance stood at 1.3372 trillion won as of late June, down 4.9% year-on-year. As the first internet bank to launch business loans, Toss Bank held the largest portfolio among the three banks in June 2024, with a balance of 1.6345 trillion won. At that time, KakaoBank's balance was 1.4070 trillion won, and K bank's was 1.4160 trillion won.
However, as of late June, KakaoBank's business loan balance rose 45.2% year-on-year to 3.6866 trillion won, while K bank recorded an 108.7% increase to 3.3015 trillion won. Both banks increased their portfolios by approximately 2.2 trillion won compared to two years ago.
The decline in Toss Bank's balance stems from risk management efforts. As of the end of 2024, Toss Bank's corporate loan delinquency rate stood at around 3%, a relatively high level. Subsequently, by reducing its outstanding balance, the bank lowered its delinquency rate to the early 2% range, improving by 0.87 percentage points (P) within one year. At the same time, its non-performing loan (NPL) ratio improved to 1.78% in June this year, a 0.57P improvement compared to the same period last year.
In contrast, KakaoBank and K bank are aggressively expanding their business loans centered on collateral-based lending. K bank launched its business real estate collateral loan product in August 2024, while KakaoBank introduced a similar product in October 2025. Currently, collateral and guarantee loans account for 69% of KakaoBank's business loan portfolio, compared to 45% at K bank. Thanks to their focus on collateral-based lending, both banks maintain healthy asset quality indicators. As of late June, KakaoBank's corporate loan delinquency rate improved by 0.07P year-on-year, while K bank saw a 0.42P improvement. Although Toss Bank currently lacks business collateral loans, analysts predict it will move to the next phase and enter the collateral loan market once its asset quality management is finalized.
A financial industry official stated, "There was a period two to three years ago when credit loans for self-employed individuals were significantly increased, leading to higher loan loss provisions, so this move aims to establish safety measures." The official added, "However, there are limitations in offering only collateral and guarantee loans to self-employed individuals. How effectively credit information data is utilized to execute loans will become a key factor in creating gaps between asset quality and profitability."

 in FINANCE
