

The COFIX (Cost of Funds Index), which serves as the benchmark for variable-rate loans in the banking sector, rose for four consecutive months before pausing temporarily, but loan rates are expected to continue climbing. With banks across the board raising deposit rates since September and mounting pressure from rising U.S. bond yields, the likelihood of further increases in loan rates has grown.
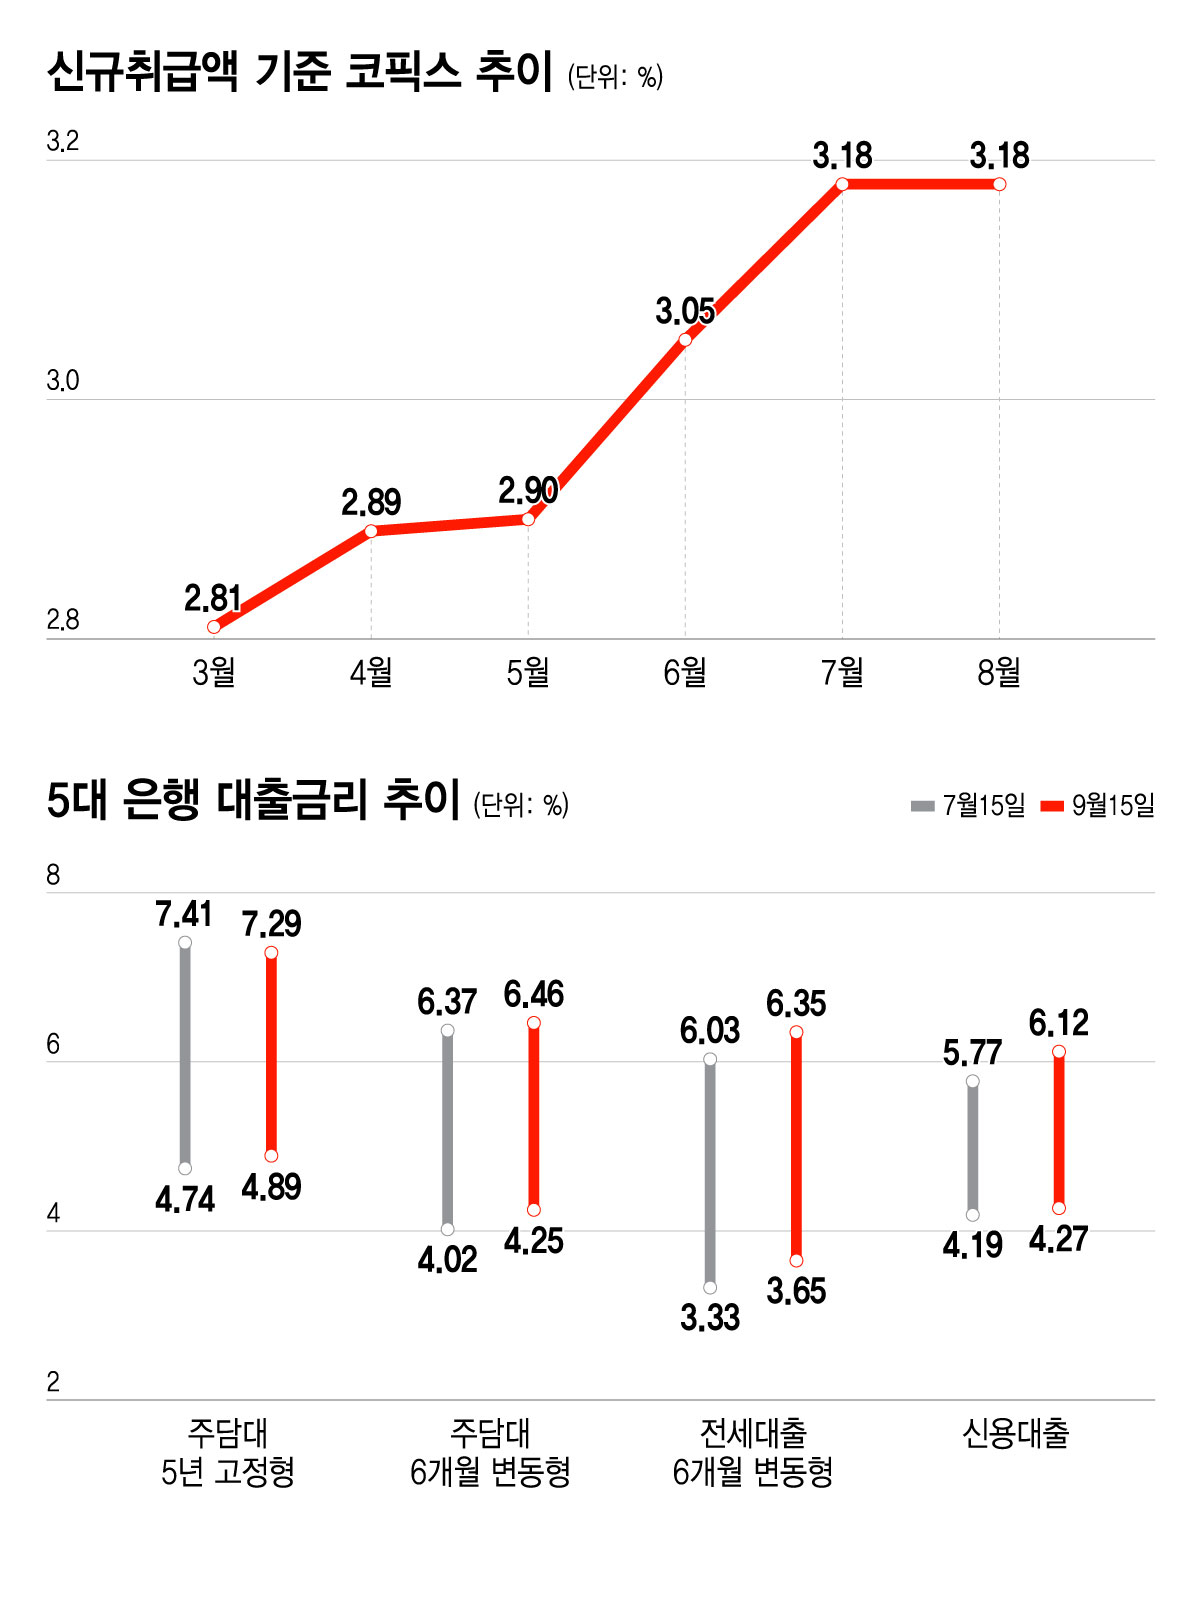
The Bankers Association announced on the 15th that COFIX based on new transaction volume for August stood at 3.18%, matching the previous month's level. COFIX is a cost indicator calculated as a weighted average of deposit rates raised by eight domestic banks and directly determines interest rates for six-month variable-rate home loans (hereinafter referred to as mortgage loans).
COFIX based on new transaction volume rose for four consecutive months from April through July but halted its upward trend in August. This occurred despite the rate-hiking cycle, as some banks secured large volumes of low-cost deposits through institutional investors, corporations, and treasury operations.
Although COFIX has temporarily paused, mortgage loan rates at banks are already on an upward trajectory. As of today, variable-rate mortgage loan rates at the five major banks (KB Kookmin, Shinhan, Hana, Woori, NH NongHyup) ranged from 4.25% to 6.46%, with the lower bound rising by 0.23 percentage points (P) and the upper bound by 0.09 P compared to two months ago (4.02%–6.37%).
The same trend applies to other loans. Six-month variable-rate personal loan rates rose from 4.19%–5.77% to 4.27%–6.12% over the same period, with lower and upper bounds increasing by 0.08 P and 0.35 P, respectively. Six-month variable-rate tenant loan rates also climbed from 3.33%–6.03% to 3.65%–6.35%, with both lower and upper bounds rising by 0.32 P.
The issue is that upward pressure on loan rates may intensify starting in September. Major banks have uniformly raised fixed deposit rates by approximately 0.1 to 0.6 P this month. As the cost for banks to raise funds through deposits has increased, COFIX based on new transaction volume for September is also likely to rise again.
Market interest rates that drive up fixed-rate mortgage loan rates are also climbing sharply. The five-year corporate bond yield, a key reference rate for five-year fixed-rate mortgage products, reached 4.578% on the 11th, marking its highest level since March 2023. It remained at a high level of 4.577% on the 14th as well.
Five-year fixed-rate mortgage loan rates at the five major banks rose from an annual range of 4.74%–7.41% two months ago to 4.89%–7.29% today, with the lower bound increasing by 0.15 P. The upper bound decreased by 0.12 P, but this was due to NH NongHyup Bank's individual interest rate cut. All other four banks, excluding NH NongHyup Bank, saw their rates rise compared to two months ago.
Upward pressure from U.S. interest rates is triggering further increases in domestic loan rates. The 10-year U.S. Treasury yield briefly hit 5.03% today, reaching its highest level since July 2007. Moreover, with growing possibilities of additional tightening by the Federal Reserve System (Federal Reserve), upward pressure on interest rates across the global bond market is intensifying.
While loan rates are rising, household loans at banks have shown a declining trend since September. As of the 14th, outstanding household loans at the five major banks totaled 781 trillion 793.2 billion won, down by 326 billion won from the end of last month (782 trillion 119.2 billion won).
Notably, outstanding mortgage loan balances fell by 589.3 billion won to 620 trillion 683.8 billion won over the same period, leading the overall decline in household loans. This is interpreted as being driven by factors such as rising interest rates and strengthened household loan management by banks, which have constrained loan demand.

 in FINANCE
