

Concerns have emerged that SK Hynix’s shareholder value could be eroded over the possibility of Solidigm’s listing on the U.S. stock market (IPO). The reasoning is that, to the extent equity is ceded to external investors, future profits must be shared. However, there are also voices arguing that it is difficult to equate equity dilution with a reduction in economic value. If Solidigm secures funds by being recognized at a high corporate valuation and utilizes them for growth, the absolute value of SK Hynix’s held equity could actually increase.
Solidigm was launched based on Intel’s NAND and storage business, which SK Hynix decided to acquire in 2020. SK Hynix paid a total acquisition price of $8.844 billion (approximately 11.85 trillion won). After undergoing a restructuring of its U.S. business structure this year, Solidigm is currently a grand-subsidiary of SK Hynix, controlled through NPS (SK Hynix NAND Product Solutions).
The background for the raised possibility of an IPO includes expanding demand for eSSDs (enterprise solid-state drives) driven by increased investment in AI (artificial intelligence) infrastructure, as well as the need for investment funds to secure production capacity and technological competitiveness. According to Bloomberg News, Solidigm has selected Wi Han (CEO) as its lead underwriter for a U.S. IPO and is expected to raise approximately $10 billion (13.4 trillion won) through a listing as early as next year. The anticipated corporate valuation is discussed at levels of up to $100 billion to $150 billion. SK Hynix stated that it is considering various options but has not confirmed any specific matters.
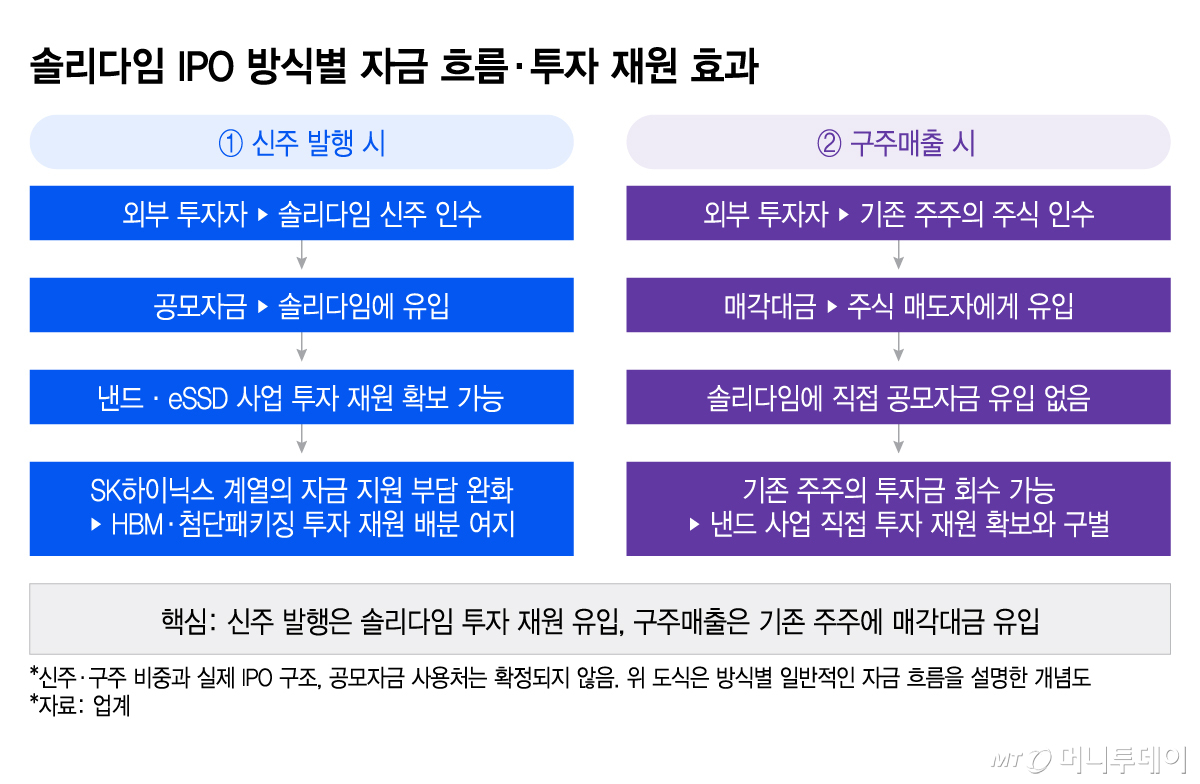
To calculate the P&L of a listing, one must first distinguish between new share issuance and the sale of existing shares. New share issuance involves Solidigm issuing new shares; while this lowers the equity ratio of existing shareholders, the funds flow into Solidigm. The sale of existing shares involves existing shareholders selling their held stocks; in this case, the proceeds go to SK Hynix’s subsidiary that sold the shares. The economic effect differs depending on whether the goal is to secure growth resources for a listed company or for an existing investor to recover part of their investment.
The core of new share issuance lies not in the equity ratio figure, but in the issue price. The higher the market values Solidigm, the less equity is required to raise the same amount of funds. Even if the equity ratio of existing shareholders decreases, it is difficult to definitively state that the value of their holdings has decreased, as cash flows into the company in exchange for this dilution. By simple calculation, if a corporate valuation of $100 billion is recognized and approximately $10 billion is raised, existing shareholders can maintain an equity ratio of around 90%.
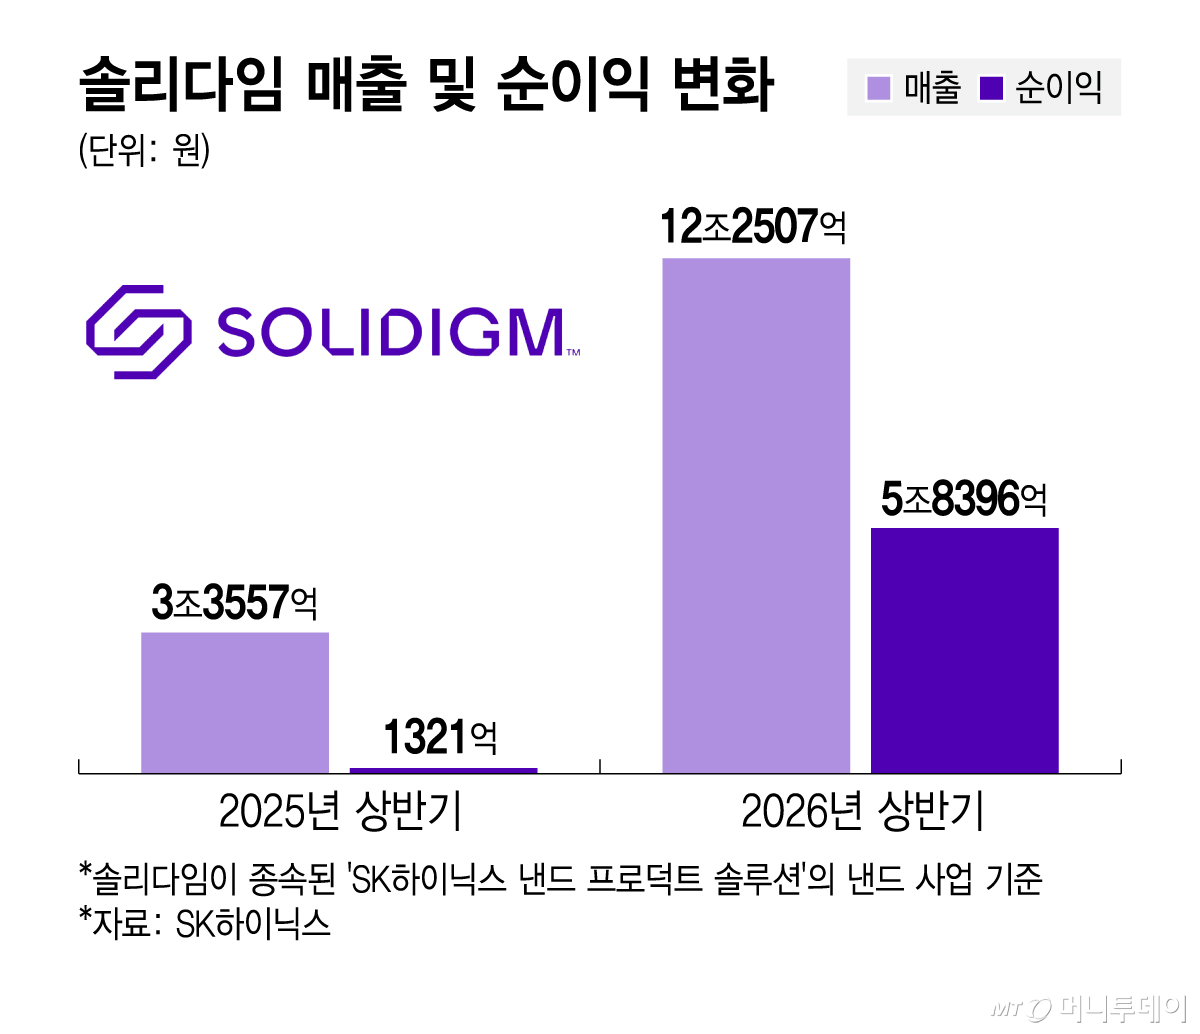
The timing of the listing at which a high corporate valuation can be recognized is also important. Solidigm (NPS’s NAND business) recorded revenue of 12.2507 trillion won and net income of 5.8396 trillion won in the first half of this year. These figures increased by 3.7 times and 44.2 times, respectively, compared to the same period last year. Strong performance in the high-capacity eSSD business drove the improvement in results.
The corporate valuations of competing companies that serve as benchmarks at the time of listing are also at their highest levels. The market capitalization of U.S. NAND company SanDisk is approximately $247.8 billion, an increase of about 13 times compared to a year ago. Japan’s Kioxia also saw its stock price rise nearly ninefold over the same period, recording a market capitalization of approximately 30 trillion yen. It is a time when high valuations can be received upon listing.
A listing could also serve as an opportunity to confirm Solidigm’s value through an independent market price. If a solid company is evaluated at a high value as an independent listed entity, SK Hynix’s corporate value may also be re-evaluated. However, the portion of profits generated by Solidigm that accrues to SK Hynix shareholders could decrease, and there is a possibility that funds intended for investment in the NAND and SSD business may choose Solidigm directly instead of SK Hynix.
If the raised funds are invested in expanding production capacity and R&D to enhance business value, SK Hynix can hold greater value even with a lower equity ratio. As Solidigm secures its own investment resources, SK Hynix’s burden of additional capital contributions may also decrease. This is about increasing the scale and speed of growth through external capital attraction.
The method of listing a company acquired via M&A (merger and acquisition) on the U.S. stock market while maintaining its status as the major shareholder has been utilized in the global semiconductor sector as well. There is also a view that this differs in starting point from the "carve-out" method, which involves physically splitting off an existing core business for listing.
Intel acquired autonomous driving company Mobileye for $15.3 billion in 2017 and listed it on NASDAQ in October 2022. The listing was conducted through a public offering of newly issued shares by Mobileye. At the time, Intel also stated that it would leverage Mobileye’s value for Intel shareholders through Mobileye’s listing.
SoftBank utilized the sale of existing shares when it listed semiconductor design company Arm, which it acquired in 2016, on NASDAQ in 2023. It secured approximately $4.9 billion while retaining an equity stake of about 90.6%. If SK Hynix uses the method of selling existing shares, it could realize part of the investment return from the M&A into which approximately $9 billion was invested.
The core of Solidigm’s IPO P&L lies not only in "how much equity is ceded" but also in "at what price and how it is ceded." The value of held equity before and after the listing, as well as the burden of additional capital contributions for investment, must be compared together. If high valuation is recognized to increase capital and accelerate high growth, Solidigm’s listing could become a choice to expand M&A results while accepting equity dilution.
An industry official said, "It is important not just the form of 'dual listing,' but what actual structure the transaction takes and how that result changes the value for SK Hynix’s existing shareholders," adding, "It is premature to judge whether shareholder value will be eroded in a state where specific IPO methods have not yet been revealed."

 in INDUSTRY


