

Despite comebacks by BTS, BIGBANG, aespa, and others, entertainment ETFs (exchange-traded funds) remain sluggish. Since the beginning of the year, returns have hovered around -40%, and capital is flowing out. Experts in the financial investment industry diagnosed that there is currently insufficient momentum to boost entertainment stocks.
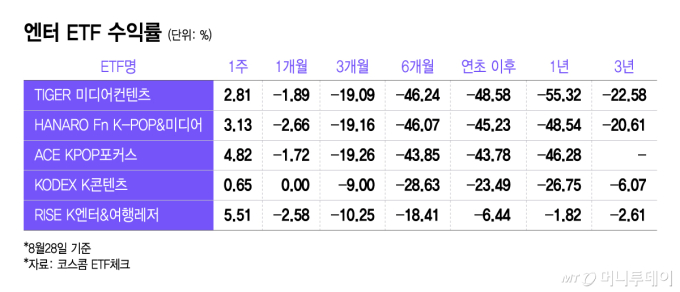
According to KOSCOM's ETF Check on the 31st, as of the 28th, 'TIGER Media Content' has recorded a return of -48.58% since the start of the year. This ranks as the third-lowest return among all domestically listed ETFs.
Both 'HANARO Fn K-POP & Media' and 'ACE KPOP Focus' also posted returns of -45.23% and -43.78%, respectively, placing them in the lower tier of returns. Additionally, other funds investing in domestic entertainment stocks such as 'ACE KPOP Focus' (-43.78%), 'KODEX K-Content' (-23.49%), and 'RISE K-Entertainment & Travel Leisure' (-6.44%) also showed negative returns.
Except for the most recent week, period-based returns for entertainment ETFs have all been negative. This is due to the concentration of semiconductor stocks since the beginning of the year, which has marginalized entertainment stocks in the market, coupled with a lack of momentum to reverse the situation.
Following BTS's comeback in March and controversy over the audience count at the Gwanghwamun outdoor free concert, sell-off pressure emerged around HYBE, causing entertainment stocks to waver. Although expectations rose later with news that popular idols such as BIGBANG and aespa would return in the second quarter, it was insufficient to revive the damaged investor sentiment.
In particular, JYP Entertainment's consolidated operating profit for the second quarter fell 41.4% year-on-year to 31 billion won, while sales dropped 15.1% to 183.1 billion won, both missing market consensus estimates. Given that the prior-year performance was substantial, a decline was inevitable, and album unit sales were also lackluster. While HYBE, SM Entertainment, and YG Entertainment reported results that met or exceeded consensus estimates, their stock prices failed to follow suit.
Capital outflows from entertainment ETFs continue. Since the beginning of the year, 118.7 billion won has flowed out of five entertainment ETFs, with an additional 13.1 billion won exiting over the past three months.
Although entertainment stocks have risen recently amid a rotating market trend, experts believe it is unlikely that they will successfully rebound.
Lee Hwan-wook, a researcher at Yuanta Securities, stated, "A conservative approach is needed regarding whether investor sentiment will continue to improve," and analyzed that "there is currently no clear upward momentum." He further explained, "The entertainment industry has entered a phase of growth slowdown due to the peak-out of album sales in the first half of 2023 and the burden of mega IP (intellectual property) reverse base effects. Accordingly, a realistic adjustment of the 12th-month forward PER (price-to-earnings ratio) band, which previously stood at 20–30 times, is necessary."
Indeed, since the beginning of this month, multiple securities firms have simultaneously lowered target prices for HYBE, SM Entertainment, JYP, and YG Entertainment.
Looking ahead, entertainment stocks could gain strength if events such as the lifting of China's Hallyu ban occur; however, projections suggest that even then, the upside will be limited due to the absence of visible results so far.
Lee Hwa-jeong, a researcher at NH Investment & Securities, said, "For entertainment stock valuations to pass their peak and for a stock price rebound to become visible, earnings stability must fundamentally be supported, and an investment narrative (investment logic) that can drive investor sentiment must be secured." She added, "Long-term accumulated earnings uncertainty has been acting as an obstacle to the initial stock price rebound."

 in STOCK
