

The securities industry's view of Kakao, which has fallen to its 52-week low, has turned cold. While investment ratings remain "Buy," a succession of brokerages have cut their target prices by more than 30%. Analysts assess that this is due to the delayed monetization of Kakao's AI (artificial intelligence) business and concerns over corporate valuation discounts following its human spin-off.
Kakao, brokerage report target prices uniformly lowered this month… "It means expectations have dropped"
According to the financial investment industry on the 28th, nine out of 12 Kakao reports issued by brokerages since the beginning of this month lowered their target prices. Most of the reports that maintained their target prices also came from firms that had previously lowered them.
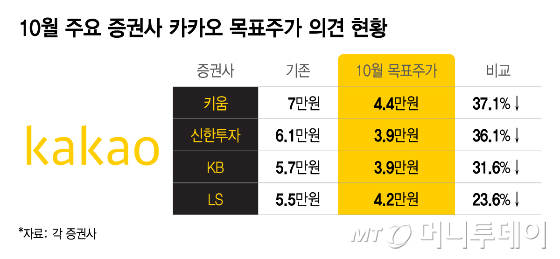
Specifically, Kiwoom Securities cut its target price by 37.1% from 70,000 won to 44,000 won, and Shinhan Investment Corp lowered it by 36.1% from 61,000 won to 39,000 won. KB Securities also revised its target price down by 31.6% from 57,000 won to 39,000 won, with three firms in total cutting their target prices by more than 30%.
In addition, LS Securities lowered its target price by 23.6% from 55,000 won to 42,000 won, and DB Securities cut it by 17.5% from 57,000 won to 47,000 won. Samsung Securities further reduced its target price, which had already been lowered in August, from 40,000 won to 35,000 won.
It is notable that all firms maintained a "Buy" investment rating despite significantly lowering their target prices. Considering the atmosphere in which domestic brokerages are reluctant to issue "Sell" ratings in their reports, the interpretation emerges that the successive large cuts in target prices reflect a more active incorporation of negative outlooks.
An official in the securities industry said, "It is necessary to pay attention to changes in target prices rather than investment ratings," adding, "The fact that multiple brokerages have uniformly and significantly lowered their target prices in a short period means that overall expectations for the company have dropped."
Doubts about growth + concerns over holding company discount after spin-off… "Stock price rebound requires business results"
Analysis suggests that doubts about growth lie behind the securities industry's negative view of Kakao. Although Kakao is positioning AI as its next-generation growth engine and expanding related businesses, it is assessed to be difficult to confirm specific revenue-generating capabilities. A common concern among brokerages is also the uncertainty regarding when expanded AI investments will translate into actual increases in sales and profits.
Concerns over corporate valuation discounts due to the human spin-off are also a burden. Kakao plans to split the company into KakaoAI and KakaoX through a business structure reorganization. KakaoAI will handle AI and platform businesses such as KakaoTalk, advertising, and commerce, while KakaoX is structured to pursue investments by utilizing its held assets and the financial strength of its affiliates.
The securities industry points out the possibility that a holding company discount may be applied to KakaoX, which will have the character of an investment company after the spin-off. This means that the value of subsidiaries held by KakaoX may not be fully reflected in the stock price. Typically, investment companies tend to be valued lower than their asset value due to constraints on cash realization and capital utilization compared to directly holding subsidiary shares.
This contrasts with Naver (NAVER), a leading domestic platform company. Although Naver's stock price has also recently fallen to its 52-week low level, most reports have maintained their target prices, and some have even raised them. The difference appears to stem from assessments of the revenue base of existing businesses such as search, commerce, and advertising, and the potential for applying AI technology to business operations.
Lee Ji-eun, a research analyst at KB Securities, forecasted, "Kakao has been pursuing its AI agent business since last year, but progress in the business has not met expectations due to delays in collaboration with external partners," adding, "Despite considerable time having passed, visible results have been limited, so a stock price rebound will be possible from the point when initial monetization results are confirmed."

 in STOCK
