

Dongwoon Anatek is continuing to post an operating loss this year, driven by expanded research and development (R&D) investment in digital healthcare and other areas.
However, the company partially improved its profitability in the third quarter of this year, among other factors due to a rising share of high-margin products.
The company's strategy is to pursue diversification of its semiconductor product lineup while focusing on the commercialization of "D-Salife," a saliva-based blood glucose measurement system.
Dongwoon Anatek said Monday that it recorded revenue of 30 billion won and an operating loss of 400 million won in the third quarter of this year.
Revenue was at a similar level to the same period last year, while operating profit turned into a deficit compared to the same period last year. However, the scale of the operating loss decreased noticeably compared to the previous quarter (a loss of 5.1 billion won).
A Dongwoon Anatek official said, "There is an aspect where profitability has improved as the share of high-specification products increased in our core semiconductor business for smartphones. We are expanding R&D investment, including digital healthcare."
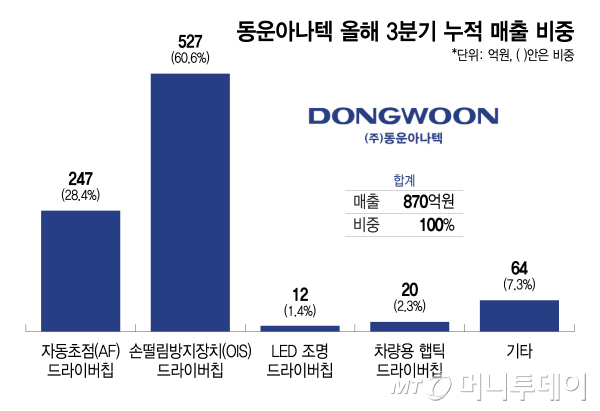
The official added, "The cumulative revenue for automotive haptic driver chips in the third quarter of this year exceeded 2 billion won for the first time. We are also striving to grow performance in our core business by increasing revenue from non-smartphone semiconductor products."
Dongwoon Anatek continues to invest in R&D for research on saliva-based blood glucose meters. Last year's R&D investment cost was 22.2 billion won, a 39.7% increase from the previous year. The cumulative R&D investment amount for the third quarter of this year is 16.3 billion won. The R&D investment ratio relative to revenue rose from 11.5% in 2024 to 17.4% last year, and to a cumulative 18.7% in the third quarter of this year.
Dongwoon Anatek emphasized that there is no change to its plan to launch D-Salife next year. The company is currently awaiting approval of its clinical trial plan from the Ministry of Food and Drug Safety (MFDS).
In August, the company strengthened its commercialization capabilities for D-Salife by recruiting former Moderna Korea CEO Son Ji-young, who gained experience at global big pharma companies, as the head of the Healthcare Division. Last month, it signed an advisory contract with UK-based healthcare specialist consultancy PharmaVentures, laying the foundation for D-Salife's entry into the global market.
Dongwoon Anatek has also been continuously pursuing shareholder-friendly policies recently. Last month, it canceled 695,491 common shares of treasury stock worth 13 billion won. Following this, on the 6th, it decided to newly acquire treasury stock worth 10 billion won. The purpose is to stabilize the share price and enhance shareholder value.
A Dongwoon Anatek official said, "Since this is the first domestic clinical trial for a saliva-based blood glucose measurement system, and there are no cases abroad either, we understand that regulatory authorities are verifying it thoroughly. The review is proceeding smoothly according to the regulatory authority's schedule."
The official said, "We will first focus on domestic approval, and then pursue entry into the global market. In our core semiconductor business, we will focus on enhancing competitiveness through portfolio diversification, such as expanding the supply of automotive products."

 in THEBIO
