

Active exchange-traded funds (ETFs), in which asset managers directly select stocks to pursue excess returns, are bound by regulations requiring them to track an index. This is due to the Capital Markets Act, which mandates maintaining a correlation coefficient of 0.7 or higher with a benchmark index. Six KOSDAQ active ETFs have all outperformed the index over the past three months, demonstrating management capabilities, but legal revisions to relax these regulations remain uncertain for passage within the year.
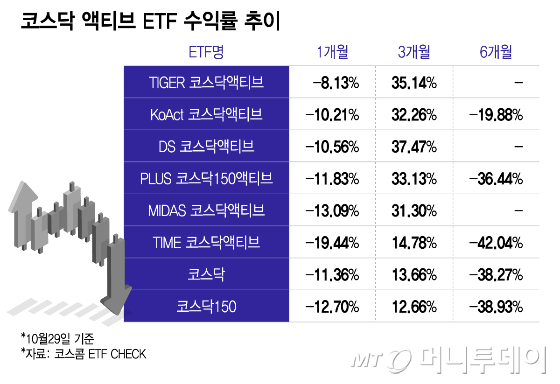
According to KOSCOM ETF CHECK and Korea Exchange on the 29th, the returns of six domestically listed KOSDAQ active ETFs over the past three months ranged from 14.78% to 37.47% as of that day, outperforming both the KOSDAQ index (13.66%) and the KOSDAQ 150 index (12.66%). However, some products underperformed the index over the past one-month and six-month periods.
All six funds primarily invest in semiconductor materials, components and equipment stocks. As expectations for benefits to materials, components and equipment suppliers grew due to expanded capital investment by memory semiconductor companies, stock prices rose, lifting ETF returns.
Although the main theme is the same, a closer look reveals slight differences. The number of constituent stocks ranges from 46 to 85. Even when holding the same stocks, weightings differ, or certain stocks are included with high weights only in specific ETFs, such as "Co-sec" in TIGER products. Returns can vary depending on which stocks managers select and how much they invest.
However, criticism also emerges that all six funds are concentrated in semiconductor materials, components and equipment stocks, resulting in limited differentiation between products. The asset management industry views the correlation coefficient regulation as creating this limitation. Under the current Capital Markets Act, "listed index collective investment securities" aim to be managed in line with index changes, making it difficult for active ETFs to deviate significantly from the index. This is why opinions are emerging that the regulation must be abolished for distinct characteristics of each asset manager to stand out.
An official at an asset management company stated, "When the market moves due to supply and demand factors rather than fundamentals (basic strength), hedging strategies can be employed to defend against return declines, such as increasing cash weightings unrelated to the index." The official added, "If a strategy is misapplied even once, it is not easy to restore a dropped correlation coefficient for products with low volatility."
China Approves First 18 Products… Domestic Revision Within Year Uncertain
Fully active ETFs are widespread in major countries such as the United States. Last year, 84% of newly listed ETFs in the U.S. and 54% of all listed ETFs were fully active ETFs.
Fully active ETFs are also set to be listed soon in China. According to the China Specialist Forum (CSF) of the Institute of Foreign Economic Policy, the China Securities Regulatory Commission approved 18 of China's first active ETFs on the 19th. The approved products are scheduled to be listed with nine each on the Shanghai Stock Exchange and the Shenzhen Stock Exchange.
The Financial Services Commission announced on January 30 that it would promote the introduction of fully active ETFs through legal revision, alongside single-stock leveraged ETFs. This stems from the purpose of resolving asymmetric regulations between domestically listed ETFs and overseas listed ETFs to achieve a "Korea Premium." The Financial Services Commission stated it would support efforts to ensure the revised bill could be submitted to the National Assembly by the first half of this year, but institutional introduction has not yet been realized.
There were also promises of institutional improvement domestically. The Financial Services Commission announced on January 30 that it would promote the introduction of fully active ETFs through legal revision, alongside single-stock leveraged ETFs. This was intended to resolve asymmetric regulations between domestically listed ETFs and overseas listed ETFs to achieve a "Korea Premium." The Financial Services Commission stated it would support efforts to ensure the revised bill could be submitted to the National Assembly by the first half of this year, but institutional introduction has not yet been realized.
Public-private discussions have also stalled. From March to April, the Financial Services Commission, Korea Financial Investment Association, and Korea Exchange held biweekly task force (TF) meetings on the introduction of fully active ETFs at the Seoul Financial Investment Center to gather opinions from the asset management industry. However, TF operations were suspended in May and are known not to have resumed as of now. Korea Exchange is also not reviewing the matter. According to documents obtained through the office of Democratic Party of Korea lawmaker Han Min-soo, Korea Exchange stated, "There are no meetings or reviews being conducted under the exchange's jurisdiction regarding the introduction of fully active ETFs."
With other issues such as single-stock leveraged ETFs taking precedence, legal revision within the year is expected to be tight. It is known that concerns exist within the Financial Services Commission that abolishing the correlation coefficient requirement could have a negative impact on the market amid controversies surrounding single-stock leveraged ETFs.
In the National Assembly, the office of lawmaker Han Min-soo is considering plans to promote legal revision as early as next month. However, it was assessed that the decision on whether to push for revision will be made after reviewing the bill submitted by the Financial Services Commission. Lee Eui-woon, Chairman of the Financial Services Commission, responded to a question from lawmaker Han regarding the necessity of introducing fully active ETFs during the National Assembly Political Affairs Committee's national audit of the Financial Services Commission on the 8th, saying, "We will review it," and added, "If you show interest, we will actively support our discussions."
On the other hand, some in the industry also voice opinions that caution is needed regarding the abolition of the correlation coefficient requirement. This is because in the KOSDAQ market, which has many stocks with small market capitalization, fund inflows through ETFs can significantly impact individual stock prices. There are also points noting that when KOSDAQ active ETFs were launched earlier this year, funds concentrated on some small and mid-cap stocks, causing their stock prices to rise.
Another official at an asset management company stated, "The U.S. market is large, so the impact of fund inflows through ETFs on stock prices is not significant, but there are many stocks with small market capitalization in the domestic KOSDAQ." The official added, "If the price of a specific stock rises significantly due to ETF funds, investor losses could occur, so minimum management standards are necessary."

 in STOCK
