
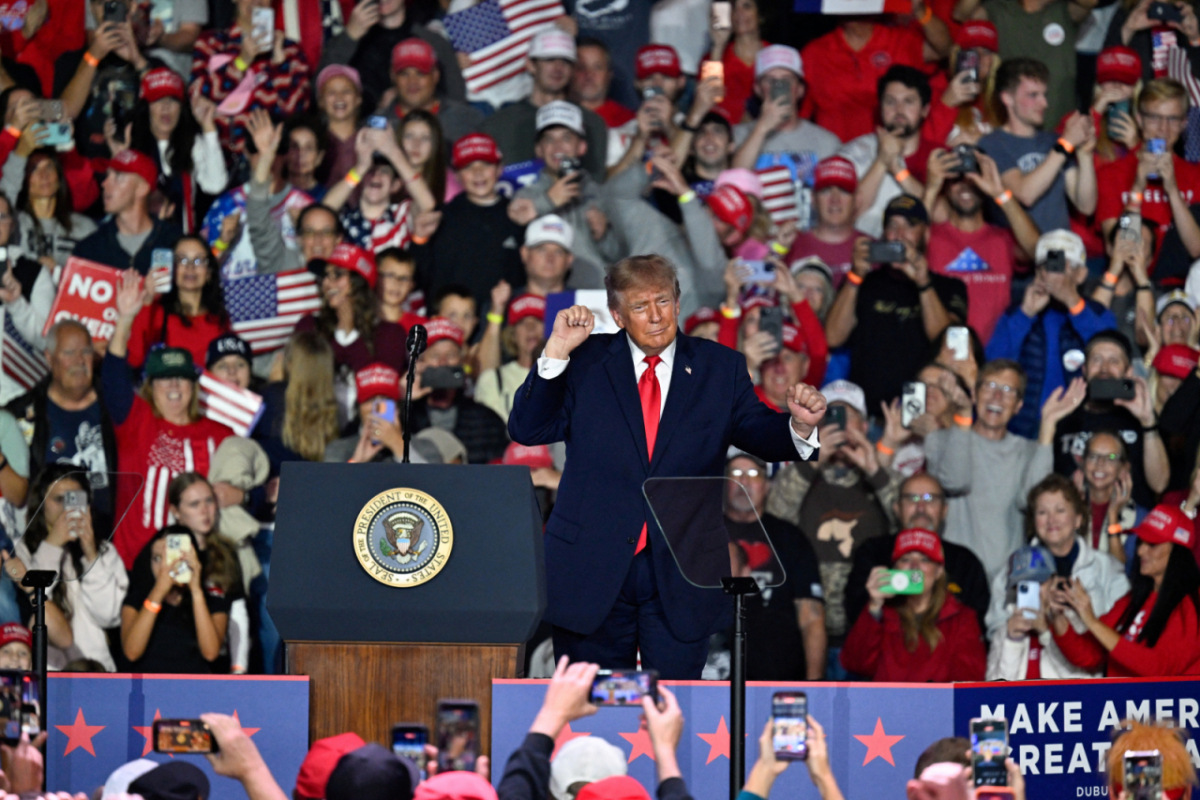
With the U.S. midterm general election approaching, the Korean stock market is set to be the "first" major market to face the election results. Concerns over intense volatility are mounting as the timing of exit poll releases overlaps with the domestic market’s opening hours.
According to the financial investment industry on the 3rd (all times in Korea), voting will conclude by 8 a.m. on the 4th in eastern Indiana and Kentucky. By 10 a.m., most of the eastern region, along with Senate battleground states such as Maine, Michigan, Texas, and Kansas, will have closed polling.
The midterm elections will determine 35 seats (35% of the total) in the U.S. Senate, all 435 seats in the House of Representatives, as well as governors and state legislators in 36 states. Predictions for Senate seat distribution based on exit polls are expected to be reported later that afternoon.
Typically, U.S. midterm elections are viewed as a positive factor for resolving political uncertainty. According to data compiled by Yuanta Securities since 1990, the S&P 500 and KOSPI indices both recorded gains in the 18% range within 200 days following midterm elections. However, counterarguments persist that results vary widely depending on the measurement period, pre-election declines, and monetary policy.
In terms of the congressional seat composition, weight is given to the view that it will be difficult to reverse the direction of the second Trump administration under either a "blue sweep" (where the Democratic Party controls both chambers) or a "split" scenario (where the Democrats hold only the House majority). This is because U.S. presidents have frequently bypassed the legislative branch via executive orders, and the size of the Democratic Party’s seats has not been sufficient to nullify presidential vetoes.
Kang Jin-hyuk, a researcher at Shinhan Investment Corp, said, "The core will be partial adjustments in budget, regulation, and taxation rather than a comprehensive policy shift." He added, "Fiscal variables are also about prioritizing support for strategic industries versus fiscal soundness, not simple expansion or contraction. This could impact semiconductor, energy, and battery companies whose economic viability depends on tax credits and subsidies, as well as companies with high government dependence."
The securities industry is focusing on gubernatorial elections rather than the House and Senate. This is because candidates have proposed pledges to suppress and temporarily suspend (moratorium) data center (DC) construction in response to public opinion opposing power supply shortages and surging electricity rates. In the U.S., where the power grid is privatized, upward pressure on generation and transmission costs is frequently passed on to households.
Hwang San-hae, a researcher at LS Securities, noted, "Candidates from both parties have made demonizing DCs a primary strategy in their election campaigns, following President Donald Trump. Furthermore, 12 of the top 20 states by U.S. DC capacity are holding gubernatorial elections. Since there is no federal regulation encompassing AI, the authority of governors, who hold approval rights, is strong." He added, "Regulatory uncertainty is inevitable until the stances of each state government are reconfirmed after the election."
Seo Sang-yeong, an executive at Mirae Asset Securities, said, "There are factors for change regarding investment location reallocation, increased project costs, and the timing of capital expenditure execution." He added, "Along with DC regulations, strengthened AI oversight is also a variable. If the Democratic Party takes control of the House, congressional investigations could expand to cover electricity rates, Big Tech’s investment and financing, AI model safety, risk assessment, incident reporting, semiconductor export controls, and the relationship between corporations and the Trump administration."
Some are issuing warnings about tail risks (low-probability but high-impact dangers) after the election. Analysts suggest that President Trump might attempt to escalate tensions against Iran as a means of shifting the political landscape, either due to widespread election disputes or concerns over responsibility for defeat. There is precedent for this: when international credit rating agency Fitch downgraded the U.S. sovereign credit rating in August 2023, it cited the January 2021 U.S. National Assembly riot as one of the background factors.
Kim Du-eon, a researcher at Hana Securities, said, "We propose increasing exposure when election disputes remain localized, oil prices and exchange rates stabilize, and foreign spot supply and demand improve." He added, "If confirmation of the U.S. majority party is delayed, we recommend a strategy of securing cash and lowering leverage. If Iranian retaliation spreads to the Strait of Hormuz and energy facilities, total risk exposure should be reduced."
There is also an unusual piece of advice suggesting that investors can refer to the portfolios of members of both U.S. parties when selecting sectors. In the U.S., exchange-traded funds (ETFs) such as NANC (tracking the Democratic Party) and GOP (tracking the Republican Party), which select stocks based on public disclosures of holdings by senior officials, are traded.
Seon Tae-hyun, a researcher at DB Securities, said, "The Democratic Party has an information technology (IT) weighting of 46.7%, concentrated in Big Tech and AI software. In the event of a landslide victory, themes related to semiconductors and green subsidies could gain strong momentum." He added, "Considering the disclosure lag (45 days), one should be wary of indiscriminate chasing buys. It is also effective to maintain interest in DC cooling and power infrastructure, which are top sectors for the Republican Party and a bipartisan issue."
 in STOCK
