
Taxation on virtual assets (cryptocurrencies), which is two months away from implementation, will be postponed once again. This comes as the government, which had maintained its policy of taxing virtual assets starting next year as scheduled, has decided to push for an amendment to the Income Tax Act that would defer virtual asset taxation by two years. The government plans to begin taxation in 2029, when information exchange on virtual assets with the United States is expected to take place.
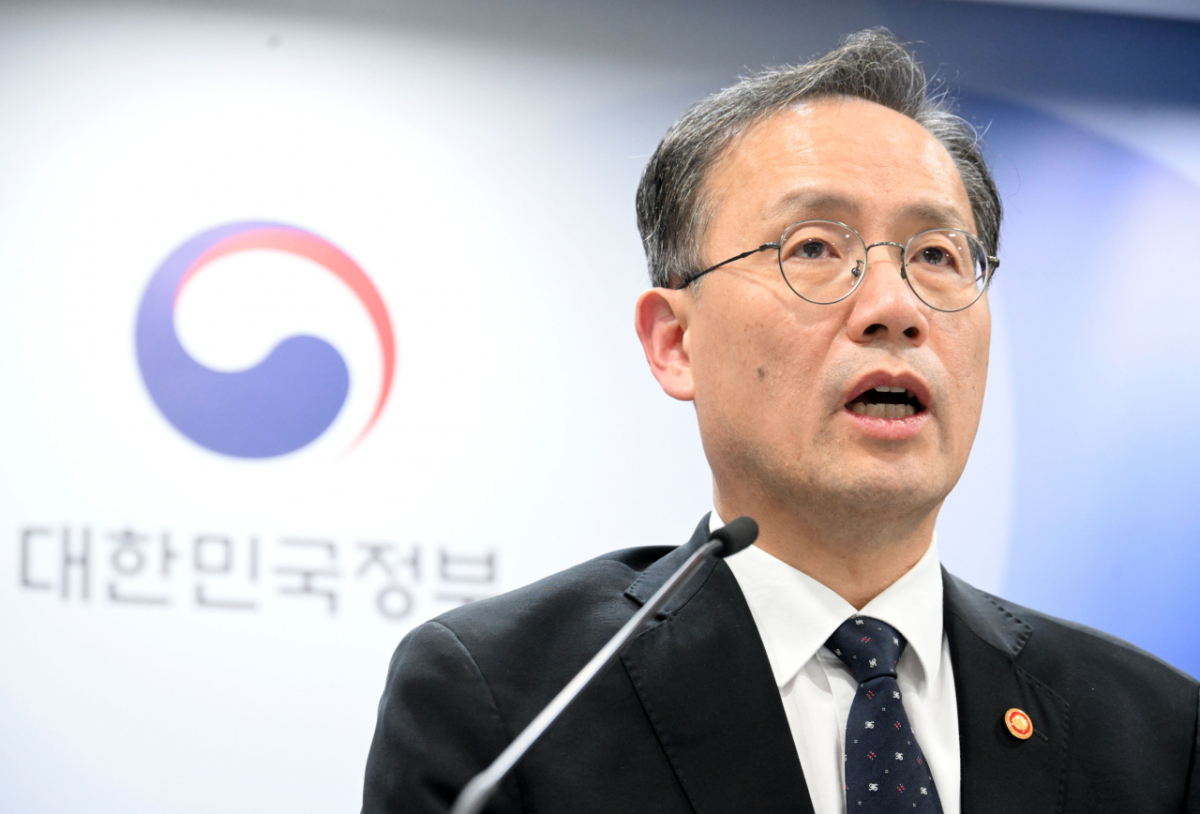
Vice Prime Minister and Minister of the Ministry of Economy and Finance Lee Hyoung-il said during a briefing at the Government Seoul Complex on Thursday, “We intend to consult with the National Assembly and push forward a plan to defer virtual asset taxation, scheduled for next year, by two years.”
Lee said that this decision was made after comprehensively considering concerns that the domestic market could be at a relative disadvantage compared to overseas markets, as well as opinions that changes resulting from the enactment of the Digital Asset Act should be reflected in the taxation system.
The core of virtual asset taxation is imposing a 20% income tax on income exceeding 2.5 million won generated from the transfer or lending of virtual assets. For example, an investor who earns a profit of 10 million won in Bitcoin and incurs a loss of 5 million won in Ethereum over the course of a year must pay 500,000 won in taxes, which is 20% of the remaining 2.5 million won after deducting the basic deduction of 2.5 million won from the total profit of 5 million won.
Virtual asset taxation, originally scheduled to be introduced in January 2022 through an amendment to the Income Tax Act in 2020, was delayed by one year due to inadequate related infrastructure. It was subsequently postponed for an additional two years citing market conditions and the need to organize investor protection systems. It was then deferred for another two years due to the necessity of further institutional adjustments.
As a result, the implementation date for virtual asset taxation had been pushed back to January 1, 2027, but under the government’s policy of an additional two-year deferral, it is now facing its fourth postponement.
In particular, the government will also push for the introduction of “loss carryforward deductions,” which are permitted by major countries such as the United States and the United Kingdom. This scheme allows losses incurred during virtual asset investment to be carried forward for up to three years and deducted from profits.
Under the current Income Tax Act, income from virtual assets is classified as miscellaneous income, meaning that losses cannot be carried forward for deduction. This implies that past losses are not subtracted from the following year’s earnings.
On the other hand, if loss carryforward deductions were permitted, in a case where an investor incurs a loss of 5 million won in the first year and earns a profit of 10 million won in the following year, only the remaining 2.5 million won after deducting the basic deduction of 2.5 million won from the 5th million won (the profit minus the carried-forward loss) would be subject to taxation.
Additionally, the government plans to launch a “Digital Asset Taxation Public-Private Joint Working Group” to discuss preparation tasks for tax implementation, including rationalizing the taxation system, establishing detailed tax standards, and improving convenience for taxpayer reporting.
The government also intends to swiftly push forward the enactment of the “Digital Asset Act” to support the formation of a digital asset ecosystem and strengthen the protection of digital asset users.
“Even if the timing of tax implementation is adjusted, the basic principle of taxation that ‘where there is income, there should be taxation’ must be upheld," Lee said. "We will utilize the upcoming two-year preparation period to ensure that virtual asset taxation can be implemented without any issues in 2029.”
 in ECONOMY
