

The outstanding balance of bank home loans scheduled to undergo interest rate changes in the fourth quarter of this year has reached 165 trillion won. Concerns are emerging that household repayment burdens for principal and interest could snowball as the timing for recalculating rates on loans taken out at low rates during the COVID-19 pandemic coincides with recent rising interest rates.
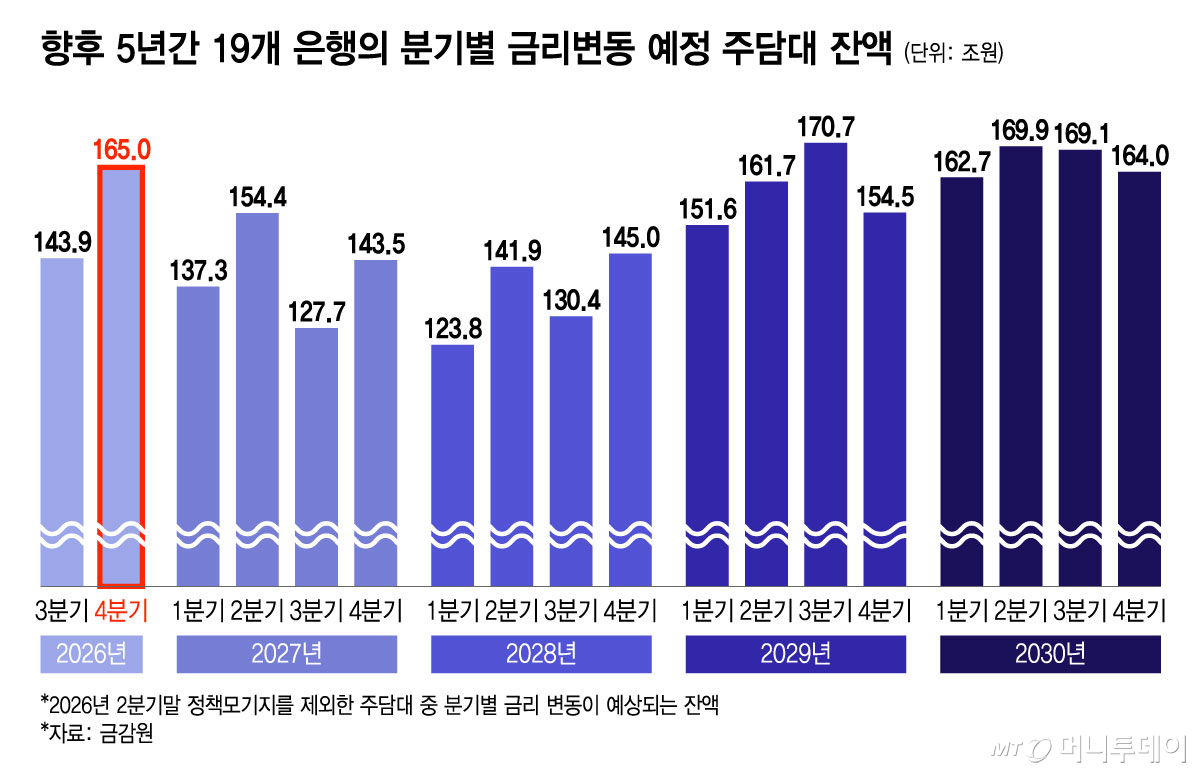
According to data submitted by the Financial Supervisory Service and obtained by the office of Rep. Han Chang-min, a member of the Social Democratic Party on the National Assembly's Political Affairs Committee, the outstanding balance of home loans at all 19 domestic banks, excluding policy mortgages, scheduled for interest rate changes in the fourth quarter of this year was tallied at 165 trillion won. This is an increase of 21.1 trillion won from 143.9 trillion won in the third quarter.
Home loans facing upcoming interest rate recalculations will continue to exceed 120 trillion won each quarter going forward. The amounts are 137.3 trillion won in Q1 next year, 154.4 trillion won in Q2, 127.7 trillion won in Q3, and 143.5 trillion won in Q4. In 2028, quarterly amounts will range from 123 trillion to 145 trillion won, while in 2029, the scale facing interest rate changes will be between 151.6 trillion and 170.7 trillion won. By 2030, the amount will surge sharply to a range of 162.7 trillion to 169.9 trillion won.
In particular, as the period for interest rate adjustments arrives for borrowers who purchased homes at ultra-low rates during the COVID-19 pandemic, their repayment burdens are expected to grow. Based on the Bank of Korea's weighted average interest rate for deposit banks, home loan rates rose by 1.56 percentage points from 2.70% in Q2 2021 to 4.26% in Q2 this year. If all 165 trillion won scheduled for interest rate changes in Q4 this year are assumed to be five-year cycle loans originated at that time, the principal and interest burden would increase by 143.4 billion won per month and 17.212 trillion won annually, based on a 30-year maturity with equal principal and interest payments.
The issue is that the loan structure continues to leave home loan borrowers fully exposed to interest rate fluctuation risks. According to the Financial Supervisory Service, of the 41.5 trillion won in new bank home loans excluding policy mortgages in Q2 this year, variable-rate loans accounted for 36.3 trillion won, or 87.5%. Pure fixed-rate loans were 4.3 trillion won (10.4%), and hybrid (fixed-rate) loans amounted to only 1 trillion won (2.4%). Even among the total outstanding home loan balance at the end of Q2 (767 trillion won), variable-rate loans reached 497.1 trillion won, accounting for 64.8%.
Since 2011, the government has promoted the expansion of fixed-rate home loans to improve the qualitative structure of household debt. The Financial Services Commission even formed a separate long-term, fixed-rate TF (task force) last year and held its first meeting on May 30, and at last month's household debt review meeting, the FSC urged banks to launch long-term fixed-rate home loans. However, in response to a recent inquiry from a lawmaker's office about the progress of the TF, the FSC replied that "the long-term fixed-rate TF is not operational and is currently under internal review."
The funding structure lies behind banks' reluctance to supply long-term, fixed-rate home loans. This is because if banks that raise funds in the short term lock in loan interest rates for 20 to 30 years, they must bear the risks associated with rising interest rates. A research commission conducted by the Financial Research Institute of Korea at the request of the FSC also analyzed that while long-term, fixed-rate home loans can reduce borrowers' repayment burdens and banks' credit risks during periods of rising interest rates, supply remains sluggish due to banks' funding costs and interest rate risk burdens.
The Financial Research Institute proposed activating MBS (mortgage-backed securities) and covered bonds as a solution to increase the supply of long-term, fixed-rate loans.
In the short term, it argued that MBS securitization through the Housing Finance Corporation should be expanded, while in the medium to long term, the market for banks issuing covered bonds using home loans and other assets as collateral to raise long-term funds must be grown. In fact, the Housing Finance Corporation is providing payment guarantees on banks' covered bonds to facilitate the supply of long-term, fixed-rate home loans, and had signed related agreements with nine banks as of last April.
Han (Rep.) emphasized that "the government has made multiple efforts to expand long-term, fixed-rate home loans but has failed every time," and stated that "policy efforts such as expanding the issuance of MBS and covered bonds must be made to reduce the proportion of variable-rate loans that shift interest rate fluctuation risks onto borrowers."

 in FINANCE
