

Samsung Electronics is expanding the scope of its MLCC (multilayer ceramic capacitor) price increases from distributors to finished goods manufacturers. The adjustment covers not only standard products but also high-specification items used in AI (artificial intelligence) servers. As price adjustments extend beyond the distribution stage to actual production clients, upward pressure on MLCC prices is spreading across the entire supply chain.
According to market research firm TrendForce on the 30th, Samsung Electronics is expected to raise MLCC prices for OEM (original equipment manufacturer) and ODM (original design manufacturer) customers in the fourth quarter of this year. Standard consumer-grade 'X5R' products are projected to see an average price increase of 25% to 30%, while high-specification 'X6S' products used in AI servers are expected to rise by an average of 10% to 20%, depending on negotiations with clients.
This adjustment has a broader scope than previous price hikes. Samsung Electronics raised MLCC prices supplied to distributors by 30% starting this month. However, the fourth-quarter increase is notable for extending the price hike to OEM and ODM customers who actually produce finished products. In particular, high-specification X6S units used in AI servers have been included in the price increase scope.
The background for price increases differs between standard X5R and high-specification X6S models. Samsung Electronics appears to be raising X5R prices significantly to regulate orders, thereby freeing up production capacity to expand its production lines for high-specification products. In contrast, the X6S model for AI servers follows a structure where increased demand directly leads to price hikes. This is interpreted as part of Samsung Electronics' strategy to boost the production share of high-specification products by regulating orders for standard models.
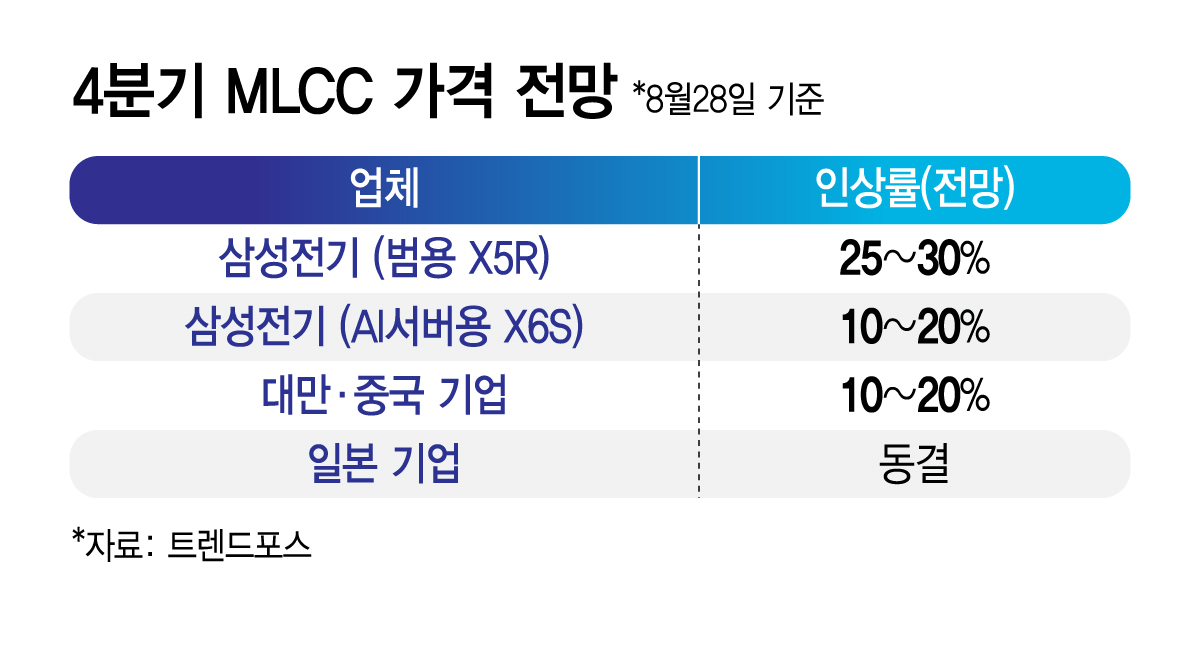
As some orders for medium- and high-capacity consumer-grade MLCCs shift to Taiwanese and Chinese companies, these firms are also expected to raise prices by an average of 10% to 20% in the fourth quarter. Some companies' production capacity utilization rates have already approached 90%. With demand for standard products dispersing to other manufacturers and available supply shrinking, upward pressure on prices is spreading across the entire market.
Additionally, rising demand for MLCCs centered around AI data centers has increased supply burdens. According to industry sources, inventory levels for major MLCC products have fallen below 30 days. With continued demand related to AI, the gap between supply and demand is likely to widen further in the fourth quarter, and price increases are expected to persist.
However, overall demand across all upstream industries of MLCCs is not strong. The traditional ICT (information and communications technology) and automotive markets may experience weaker-than-usual seasonal demand in the second half of this year due to economic slowdowns in China and the United States and a contraction in consumer sentiment. Ultimately, the recent MLCC price increase is analyzed as being driven more by increased demand for high-specification products centered on AI and production adjustments by suppliers rather than a broad recovery in upstream demand.
Whether the price hike trend will spread across the entire MLCC industry depends on the moves of Japanese companies. Murata, Taiyo Yuden, and Kyocera are currently holding prices steady while monitoring market conditions. With Taiwanese and Chinese companies expected to follow Samsung Electronics' lead in raising prices, if major Japanese firms also join the price increases, it could signal a broader spread of MLCC price hikes across the industry.

 in INDUSTRY
