
Interest rate and geopolitical variables have once again pulled the KOSPI index back from the 7,000 threshold, resulting in a box-range market. As the third-quarter earnings season emerges as a key market focus, experts advised investors to pay close attention to overseas indicators and corporate trends that can gauge the mood in advance.
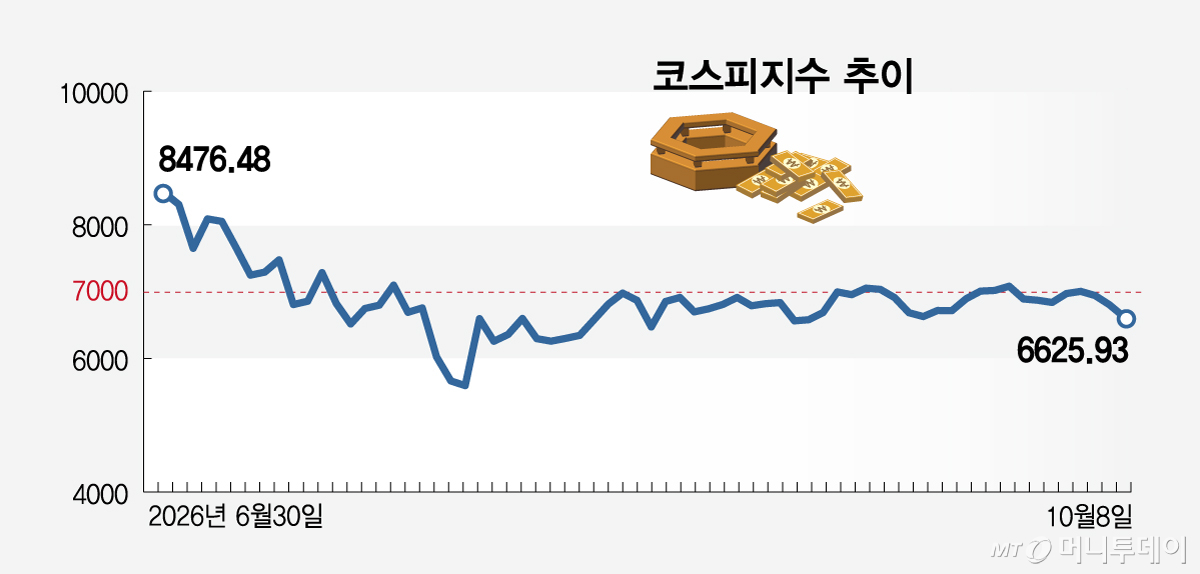
According to Korea Exchange on the 11th, the KOSPI index closed at 6,625.93 on the 8th. The weekly decline was 377.81 points (5.39%). Other corporations, including share buybacks, made net purchases worth 2.4823 trillion won, and retail investors bought a net 6.3591 trillion won, while foreign investors sold a net 6.4692 trillion won and institutional investors sold a net 2.3887 trillion won.
Concerns persist that the weakening of downside support is underway as Samsung Electronics' and SK Hynix's on-market share buybacks near their end. Samsung Electronics has acquired 106.7% of its announced quantity, effectively completing its buying operations, while SK Hynix has acquired 83.3% and is expected to place its final buy orders around late this month. Kim Seok-hwan, a researcher at Mirae Asset Securities, said, "Market attention is shifting to the question of whether earnings can support stock prices even without share buybacks."
The U.S. inflation data release and overseas large-cap earnings are cited as the turning point for this week. In Korean time, the U.S. September CPI (Consumer Price Index) will be released on the 14th, while the U.S. September PPI (Producer Price Index) and TSMC's earnings will be disclosed on the 15th.
Experts forecast that if inflation pressure remains within the expected range and anxieties surrounding AI (artificial intelligence) demand and funding subside, the domestic stock market could enter the major corporate earnings announcement phase with rebound momentum.
Lee Kyung-min, a researcher at Daishin Securities, stated, "The U.S. August PCE (Personal Consumption Expenditures), which showed inflation slowdown at the end of last month, had limited market impact due to the influence of changes in the calculation method by the Bureau of Economic Analysis (BEA). However, if the inflation slowdown is confirmed again in the September CPI, it is expected to ease vigilance regarding inflation while contributing to a downward stabilization in bond yields." He added, "The KOSPI market's 12-month forward PER (Price-to-Earnings Ratio) has fallen further into historically low territory at 5.26 times. There is ample room for upward revision due to valuation normalization, and even assuming a forward PER of just 6 times, the index could reclaim the 7,700 level."
Opinions favored a gradual approach regarding investment strategy. This outlook is supported by the compounded uncertainty arising from the intersection of Middle East armed conflict and U.S. midterm elections.
Kim Jong-min, a researcher at Samsung Securities, said, "While the time for large-cap stocks is approaching, it is premised on the resolution of macroeconomic pressures. At this point, an alpha play (pursuit of excess returns) centered on flexible small- and mid-cap stocks is in a valid phase." He added, "It is rational to set the investment timing for the two major semiconductor stocks after the expected resolution of macroeconomic concerns around the U.S. midterm elections and after confirming a trend-based breakout of the index."
Hwang San-hae, a researcher at LS Securities, said, "We are paying attention to sectors where interest rates and geopolitical risks act as revaluation factors." He noted, "The expansion of European defense budgets and energy restructuring will support order intake for defense and shipbuilding stocks, high oil prices will boost margins for energy stocks, and power bottlenecks in data centers will underpin the pricing power of power equipment stocks. Financial stocks also have room for revaluation if it is confirmed from earnings by companies such as JPMorgan Chase that high interest rates are being converted into profits."
 in STOCK
