

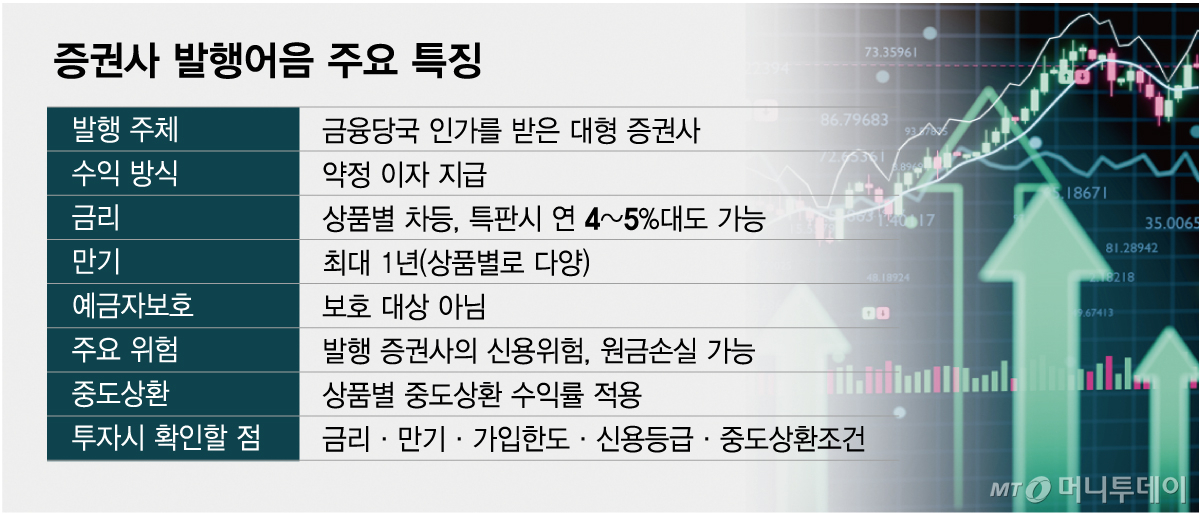
Securities firms are competing to attract retail investors through the launch of new issued promissory note products, high-interest-rate special sales, and mass-market advertising. As the number of issuers has increased to nine, issued promissory notes—originally a funding tool for securities firms—are establishing themselves as investment products for managing individuals' lump sums and short-term surplus funds. While this presents a new investment opportunity with interest rates potentially higher than bank deposits, experts point out that because these instruments are not covered by deposit insurance, investors must carefully scrutinize the issuer's credit risk and actual return conditions.
Issued promissory note commercials appear, sparking buzz on YouTube… Nine securities firms compete for mass-market adoption
According to the financial investment industry on the 26th, competition among securities firms has intensified as the number of issued promissory note operators increased to nine following new licenses granted to Samsung Securities and Meritz Securities. The firms are producing advertisements emphasizing high interest rates and easy enrollment, while launching a variety of products ranging from fixed-term agreements for depositing lump sums for a set period to demand deposit types and Comprehensive Asset Management Account (CMA) types.
Recently, Samsung Securities, which received an issued promissory note business license, produced TV commercial-style advertisements to promote its issued promissory notes on platforms such as YouTube. The 30-second video ads titled "A New Standard for Issued Promissory Notes" and "Trust Is Important for Issued Promissory Notes" each recorded millions of views on YouTube. This effort to introduce the previously unfamiliar instrument to general retail investors and generate interest demonstrates a shift in which issued promissory notes are expanding their base as a mainstream financial product.
Indeed, the market size is growing. According to the Financial Services Commission, the outstanding balance of issued promissory notes from the seven existing licensed securities firms increased from 51.2744 trillion won at the end of last year to 55.9291 trillion won by the end of the second quarter this year. The balance grew by nearly 10% in the first half of this year alone.
The expansion of the issued promissory note market means that retail investors have more options for managing their surplus funds. This is because they now have the opportunity to manage money previously held in bank time deposits or parking accounts through issued promissory notes.
An issued promissory note is a financial product with a maturity of one year or less, issued by a large securities firm licensed by financial regulators using its own credit. When an individual purchases an issued promissory note, it is effectively lending money to the securities firm, which then assumes the obligation to repay the principal and interest as agreed upon at maturity. While investors can expect a fixed interest rate similar to a deposit, the legal nature differs from depositing money in a bank.
Securities firms deploy funds raised through issued promissory notes into bonds, corporate finance, and other areas to pursue returns. The government mandates that these firms supply venture capital to small and medium-sized enterprises and venture companies in proportion to their issued promissory note funding. This design ensures that as the issued promissory note market grows, the supply of growth capital for businesses also expands.
Attractive high interest rates… But actual interest and credit risks must be carefully assessed
The first thing investors should consider is the actual interest they will receive. Not everyone earns returns equivalent to a special sale offering 5% annual interest. Some products limit enrollment to 10 thousand won or provide benefits only to new customers. Interest rates displayed in advertisements are typically pre-tax yields converted on an annual basis.
For example, investing 10 thousand won in a three-month maturity issued promissory note with a pre-tax annual interest rate of 5.8% yields approximately 14,500 won in pre-tax interest and about 12,300 won after tax. These are simple calculations; actual interest varies depending on the number of days to maturity. Therefore, investors should verify the maximum amount they can actually invest and the maturity period, rather than focusing solely on the highest rate, and compare how much more after-tax interest they can earn compared to bank deposits for the same period.
When you need to use your money is also important. If a fixed-term issued promissory note is redeemed before maturity, a lower yield than originally agreed may be applied. On the other hand, while demand-type or CMA-type products allow relatively free withdrawal of funds, their interest rates may be comparatively lower.
A risk that retail investors must understand is the credit risk of the issuing securities firm. Even if a securities firm incurs losses during its operations, those losses are not immediately passed on to investors. However, if financial soundness deteriorates and the firm fails to repay principal and interest, investors may also suffer losses. In particular, unlike bank deposits, issued promissory notes are not covered by deposit insurance.
A source in the securities industry said, "Investors should first determine when they need their funds, compare actual after-tax interest with bank deposits for the same period, and then check enrollment limits, early redemption conditions, and the credit rating and financial soundness of the issuing securities firm." The source added, "More important than a high interest rate is judging whether the additional interest earned is sufficient relative to the risks one is taking on."

 in STOCK
