

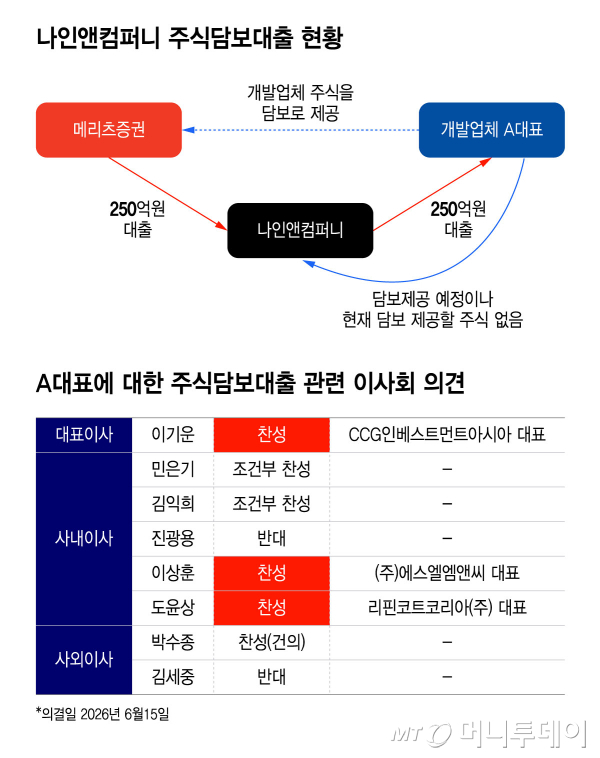
Concerns are emerging that Nine & Company (formerly Gonggu Women) may face increased cash pressure because it failed to properly secure collateral after lending 25 billion won to CEO A of a development company. This is because CEO A's shares have already been pledged as collateral to Meritz Securities, from which Nine & Company borrowed the same amount. It was revealed that there were disagreements within the board of directors regarding this matter.
According to electronic disclosures by the Financial Supervisory Service on Friday, Nine & Company deployed large amounts of funds over a short period through cash loans, prepayments for outdoor advertising goodwill, and investments in non-listed companies, both before and after being acquired in June by Singapore-based private equity fund CCG Investment (CCGI).
The company disclosed on the 15th via an amended disclosure that Meritz Securities had received collateral in the form of the company's shares held by CEO A. This contract pertains to the 25 billion won borrowed by Nine & Company from Meritz Securities, with CEO A providing a form of third-party collateral.
This structure is analyzed as resulting from Nine & Company borrowing 25 billion won from Meritz Securities and lending that amount directly to CEO A. It is reported that Meritz Securities raised issues regarding this arrangement. It disclosed that it plans to establish a pledge right on CEO A's shares as soon as the collateral provided to Meritz Securities is released. The date for the release of Meritz Securities' pledge right on CEO A's shares has not yet been determined.
Ultimately, for Nine & Company to secure CEO A's shares as its own collateral, it must repay Meritz Securities before maturity. The maturity date for the loan to CEO A is December 15. The share price of the stocks held by CEO A has fallen, causing the collateral value to decline.
The company said that the purpose of the cash loan to CEO A was "to control risk through securing stock collateral while improving liquidity management yield rates via a short-term cash loan with a six-month maturity." However, there were internal conflicts of opinion among the directors. Two out of eight directors voted against the proposal. Two who approved attached conditions, and another one who approved submitted recommendations.
The industry is concerned that Nine & Company deployed large amounts of funds over a short period through cash loans, prepayments for outdoor advertising goodwill, and investments in non-listed companies, both before and after being acquired in June by Singapore-based private equity fund CCG Investment (CCGI). This is because aggressive investments were made even while arranging and repaying acquisition financing for the M&A.
Nine & Company paid 5 billion won as a prepayment for outdoor advertising goodwill (premium) to SLM&C, represented by non-executive director Lee Sang-hoon, in the first half of this year. In July, it purchased shares in non-listed company AI Energy for 4.12 billion won. The company reported a net loss for the period of 2.1 billion won last year with no revenue.
Nine & Company's revenue in the first half of this year was 22.4 billion won, an increase of 100 million won compared to the same period last year, while operating profit was 2.7 billion won, a decrease of 900 million won over the same period. The net income for the first half increased due to the large-scale disposal of financial products, making it difficult to view this solely as the performance of the apparel business.
A company official said, "The loan case involving CEO A has undergone legal review through Law Firm Sejong and was confirmed to have no issues in the semi-annual audit. The pledge right is clearly established under the documentary contract, so there is nothing to worry about." The official added, "Parts related to the acquisition process were also conducted lawfully, and it is difficult to disclose some matters due to non-disclosure agreements (NDA)."

 in STOCK
