
The plan to shorten the settlement cycle for the domestic stock market has taken shape. Investors may be able to receive proceeds from stock sales one day earlier as soon as 2028. However, the key lies in the readiness of the securities industry, which must process more than 10 stages of settlement operations within a single day, and foreign investors burdened by time zone differences.
On Monday, the Korea Exchange, the Korea Securities Depository, and other securities-related agencies released a draft roadmap to shorten the stock market settlement cycle from the current two business days (T+2) to one business day (T+1). Aiming for a transition by 2028, they plan to refine related systems and operational frameworks, with the specific implementation date to be determined after considering the readiness of market participants.
The settlement cycle is the period from the execution of a stock trade until the actual exchange of shares and funds. Shortening the settlement cycle is expected to improve the efficiency of fund utilization for investors. This is because they can recover proceeds from stock sales one day earlier to deploy in other investments or respond swiftly to funding needs.
The overall settlement risk across the market will also decrease. As the scale of unsettled trades and the duration of risk exposure after a trade are reduced by one day, the likelihood of settlement failure can be lowered.
The inspection and management system for short selling will also become more efficient. Currently, brokerages check for trades with insufficient settlement quantities based on noon on T+2 (the settlement date) and report to the exchange after verifying whether they constitute short selling. Going forward, the inspection reference time will shift to 4 p.m. on T+1, allowing for a one-day earlier confirmation of settlement quantity shortages compared to the current standard.
Shortening the settlement cycle is also a trend in global capital markets. The United States has implemented the T+1 settlement system since May 2024, while the EU (European Union) and the UK are pushing for a transition by October 2027. In Asia, India has already adopted the T+1 system, and Hong Kong is promoting implementation in the second half of 2028.
However, the operational burden on the securities industry resulting from the system transition is a hurdle to overcome. This is because procedures such as verification, correction, clearing, currency exchange, and settlement following stock trades will be concentrated within a single day. In addition to brokerages, comprehensive computer system upgrades and operational automation are needed across all market participants, including custodian banks and asset management companies.
An official at a brokerage said, "It is a considerably difficult task because we must simultaneously change the systems and business practices of related institutional investors such as the exchange, the Korea Securities Depository, the Bank of Korea, brokerages, asset management companies, and pension funds."
The official added, "We must approach this in stages while maintaining the domestic settlement failure rate, which is effectively at 0%, to ensure preparation proceeds without disruption."
Constraints may also arise in fund management for foreign institutional investors. Global investors who purchase domestic stocks using funds from selling overseas assets, such as those in the United States, may face difficulties in funding due to differences in settlement timing and time zones across countries. The reduced time available for trade confirmation, settlement instructions, and won currency exchange is also a burden.
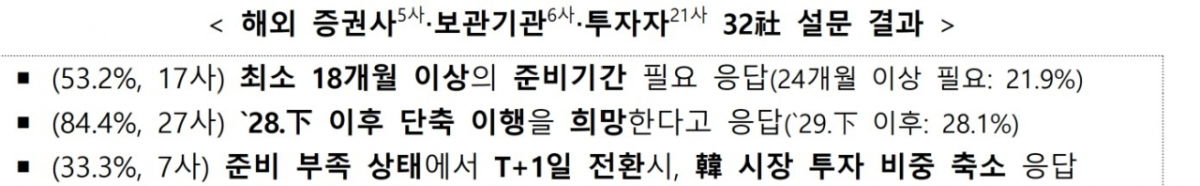
In fact, in a survey conducted by the exchange targeting overseas brokerages, custodians, and investors, 33.3% of respondents answered that they might reduce their investment allocation to the Korean market if the T+1 system were implemented while they were inadequately prepared. In the same survey, 27 out of 32 total respondents (84.4%) expressed a preference for a settlement cycle shortening date in the second half of 2028 or later for the Korean market, which is in the same context.
In this regard, Park Yong-jin, vice chairman of the Regulatory Rationalization Committee, said, "Foreigners who were initially negative about the introduction of the system itself have shifted to a stance of wanting to consult together after two public forums."
He added, "If implementation is rushed without sufficient preparation, it could receive negative evaluations from foreign investors and adversely affect inclusion in the MSCI (Morgan Stanley Capital International) developed market index."
 in STOCK
