

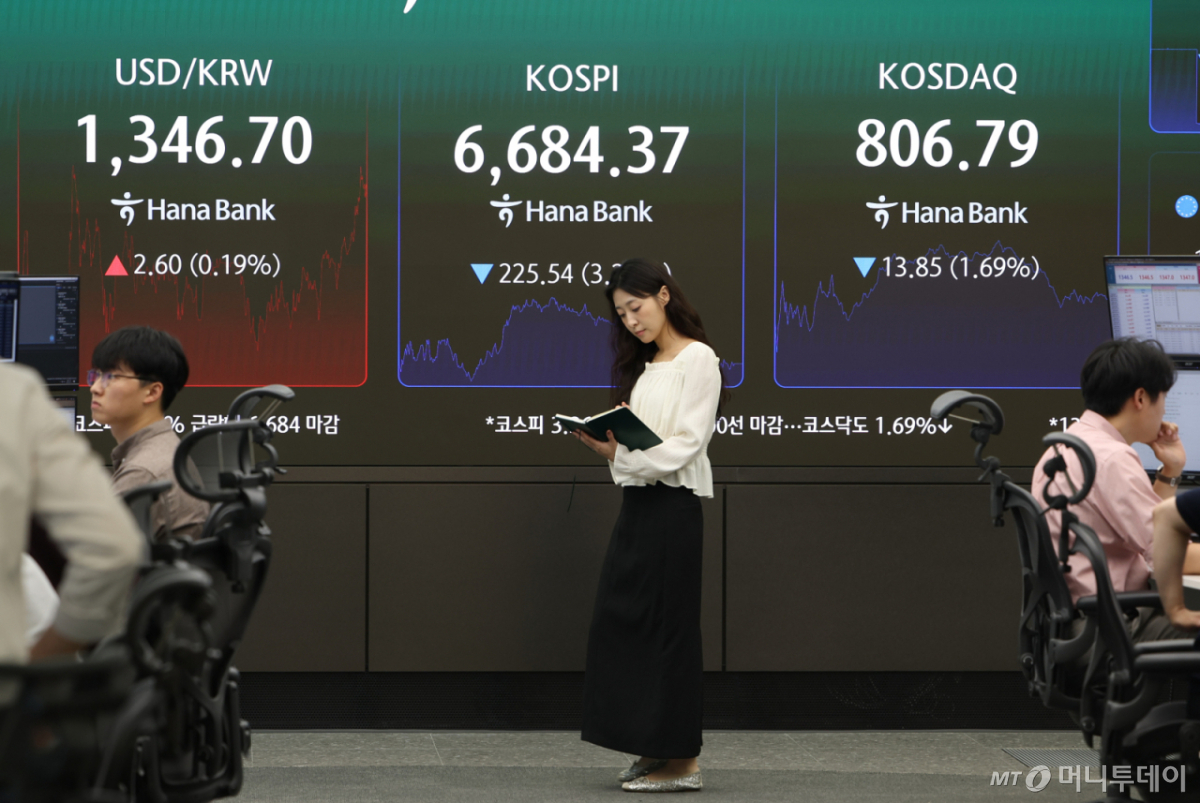
The won-dollar exchange rate, which has plunged more than 200 won in just over two months, has reached a turning point ahead of a possible resumption of monetary tightening by the U.S. Federal Reserve.
With international oil prices and U.S. Treasury yields surging, a Fed rate hike could widen the interest rate gap between South Korea and the U.S. again, potentially reversing some of the won's sharp appreciation.
The simultaneous rise in the won's value and inflation is also expected to increase pressure on the Bank of Korea to raise interest rates further after it has already shifted toward a tightening stance.
On Monday, the won-dollar exchange rate closed weekly trading at 1,347.3 won, up by 1.4 won from the previous trading day. This marks three consecutive days of increases.
Compared to 1,551.2 won on July 1, the exchange rate has fallen by more than 200 won over two months, but the downward trend has recently slowed. The exchange rate had dropped to the 1,330 won range earlier this month before rising again to the 1,340 won range amid a sharp surge in international oil prices and higher U.S. Treasury yields.
One of the factors that had driven the appreciation of the won was the narrowing of the interest rate gap between South Korea and the U.S. With concerns about U.S. tightening easing in July and August, the Bank of Korea repeatedly raised its base rate, narrowing the interest rate differential between the two countries. This was compounded by a strong semiconductor export performance leading to dollar sales by exporters and a strengthening yen, accelerating the decline in exchange rates.
However, if the Fed raises interest rates this week, the trend could change. If the Fed increases its base rate by 0.25 percentage points at the Federal Open Market Committee (FOMC) meeting on the 15th–16th (local time), the interest rate gap between South Korea and the U.S. will widen again from a high of 0.75 percentage points to 1.00 percentage point.
What pushed the Fed toward raising rates was stronger-than-expected employment data and inflationary pressures. Non-farm payrolls in the U.S. increased by 162,000 in August, significantly exceeding market forecasts. The core consumer price index also rose by 0.3% from the previous month, surpassing the expected 0.2%. Additionally, with international oil prices exceeding $100 per barrel, concerns about a resurgence in inflation have grown.
As a result, the market is treating a September rate hike as a foregone conclusion. However, since the market has already priced in much of the anticipated September increase, assessments suggest that the direction of exchange rates will depend more on the future interest rate path than on the hike itself. If the hike is limited to one round, it may be seen as resolving uncertainty; however, if the dot plot and Fed Chair Kevin Warsh strongly signal further tightening possibilities, pressure for a stronger dollar and weaker won could intensify.
Kim Ho-jeong, an economist at Yuanta Securities, presented a baseline path of 0.25 percentage point hikes in both September and December but stated that "the market's anticipated sequence of three to four consecutive rate hikes is excessive." This implies that the focus will be less on the September hike itself and more on the dot plot and the future tightening intensity projected by the Fed as key variables for the market.
With the Fed resuming its tightening measures, the Bank of Korea's calculations have also become more complex. The Bank of Korea raised its base rate consecutively in July and August, reaching an annualized 3.00%, before signaling a slowdown in the pace of hikes. In the dot plot showing the projected path for the base rate over the next six months, five dots were placed at the current level of 3.00%, ten at 3.25%, and six at 3.50%.
Bank of Korea Governor Shin Hyun-song stated after last month's Monetary Policy Board meeting that regarding the median value of 3.25% in the dot plot, "it implies raising rates once more during the next four meetings, so we expect a gradual pace of increases." This indicates an intention to assess the effects of two consecutive rate hikes before deciding on further increases.
If the interest rate gap between South Korea and the U.S. widens again due to Fed rate hikes and the won-dollar exchange rate rebounds, pressure from rising import prices due to a weaker won could intensify. Compounded by high oil prices originating in the Middle East, domestic consumer price inflation rebounded to 3.1% last month.
The market is placing weight on the possibility that the Bank of Korea will implement one additional rate hike in November or early next year, raising the final interest rate to 3.25%. However, if the Fed's tightening lasts longer than expected and upward pressure on exchange rates and inflation intensifies, the magnitude of further rate hikes by the Bank of Korea is also expected to change.

 in ECONOMY
