

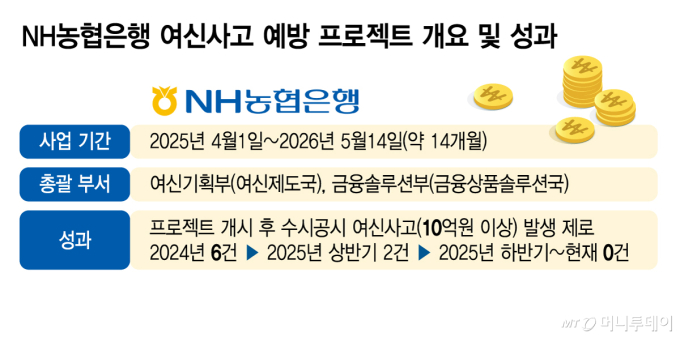
As major commercial banks continue to experience credit-related financial incidents, attention is focused on NH NongHyup Bank, which has recorded zero large-scale financial incidents subject to unscheduled public disclosure for over 14 months. This achievement resulted from strengthening internal control and consumer protection decision-making functions centered on the board of directors, alongside a high-intensity "credit incident prevention project" implemented over 14 months, which precisely established proactive control mechanisms.
According to financial industry sources on the 19th, NH NongHyup Bank conducted the "credit incident prevention project" from April last year through May this year, led by the Credit Planning Department (Credit Policy Division) and the Financial Solutions Department (Financial Product Solutions Division). This was based on the judgment that with the introduction of a responsibility structure map, it became necessary not only to identify accountability after incidents occur but also to build a proactive risk management system. As a result of completing computer development for all 120 improvement tasks identified during the project period and applying them on-site, the bank has recorded zero (0 cases) credit incidents subject to unscheduled public disclosure exceeding 1 billion won for approximately 16 months so far. This contrasts with the trend of increasing credit incident counts at other major commercial banks over the past two years compared to 2024. Since introducing the responsibility structure map last year, it is being evaluated as an effective model case among follow-up system maintenance measures promoted by institutional investors in the financial sector.
NH NongHyup Bank conducted a comprehensive analysis of credit incident cases that occurred within its own operations or at other banks over the past five years to design a detailed blocking network by incident type and stage.
To prevent incidents involving loans processed with registered fictitious collateral, the bank mandated pre-screening checks of external real estate registration information during the loan review stage. This involves comparing external real estate registration data from Korea Evaluation Data (KoDATA) with review information entered into the bank; if discrepancies are found, the review is blocked.
Verification measures were also strengthened against methods that secure loans exceeding actual transaction amounts using forged sales contracts. The criteria for requiring sales contracts were tightened, and a verification process utilizing AI-based OCR (optical character recognition) was introduced. Measures were also put in place to prevent excessive lending using fictitious lease agreements. Systems were developed to mandate lease investigations during the review process, and criteria for requiring lease agreements were strengthened.
Furthermore, to prevent incidents where specific appraisal firms collude to inflate collateral values, the number of appraisal requests was limited to three times, and the request system was upgraded to randomly designate appraisal firms.
Incident cases from other banks were also utilized to improve NH NongHyup Bank's systems. To prevent loans being granted when applicants submit false income or employment information, the bank implemented a process for reviewers to compare and verify business operator, income, and employment information entered by the reviewer against public MyData (personal credit information management) information.
Immediately after concluding the project in May, NH NongHyup Bank established a "Credit Incident Prevention TF (Task Force·provisional name)" involving relevant departments such as the Audit Department, Compliance Monitoring Department, and Credit Supervision Department, which is now operating on an ongoing basis. The TF will be responsible for continuously identifying and improving vulnerabilities in credit regulations and systems, as well as exclusively monitoring the incident prevention process. An NH NongHyup Bank official stated, "Going forward, we will make every effort to enhance trust among financial consumers through continuous monitoring and proactive process improvements."

 in FINANCE
