
E-commerce platform Curly, which recorded its first annual profit in 10 years since its founding and escaped chronic losses, has solidified its profit structure by posting an operating profit in the hundreds of billions of won range in the first half of this year alone. With this trend, achieving a profit in the hundreds of billions of won for the full year is highly likely.
Accordingly, industry observers are focusing on whether Curly will resume its initial public offering (IPO), which it abandoned midway in early 2023. While projections suggest a corporate valuation nearing 3 trillion won, Curly remains cautious about pushing forward with a listing within the year.
According to relevant industry sources on the 27th, Curly has not yet finalized its plans or timing for a listing this year. Inside the company, there are also opinions that it would not be too late to proceed with an IPO after confirming verified 'annual revenue and operating profit report cards' that the market can trust.
Kim Jong-hoon, Curly's Chief Financial Officer (CFO), stated in an interview with MoneyToday last March that "we have moved past the stage where we need to go public due to a lack of funds as in the past" and added, "We will choose the optimal IPO timing for both shareholders and the company."
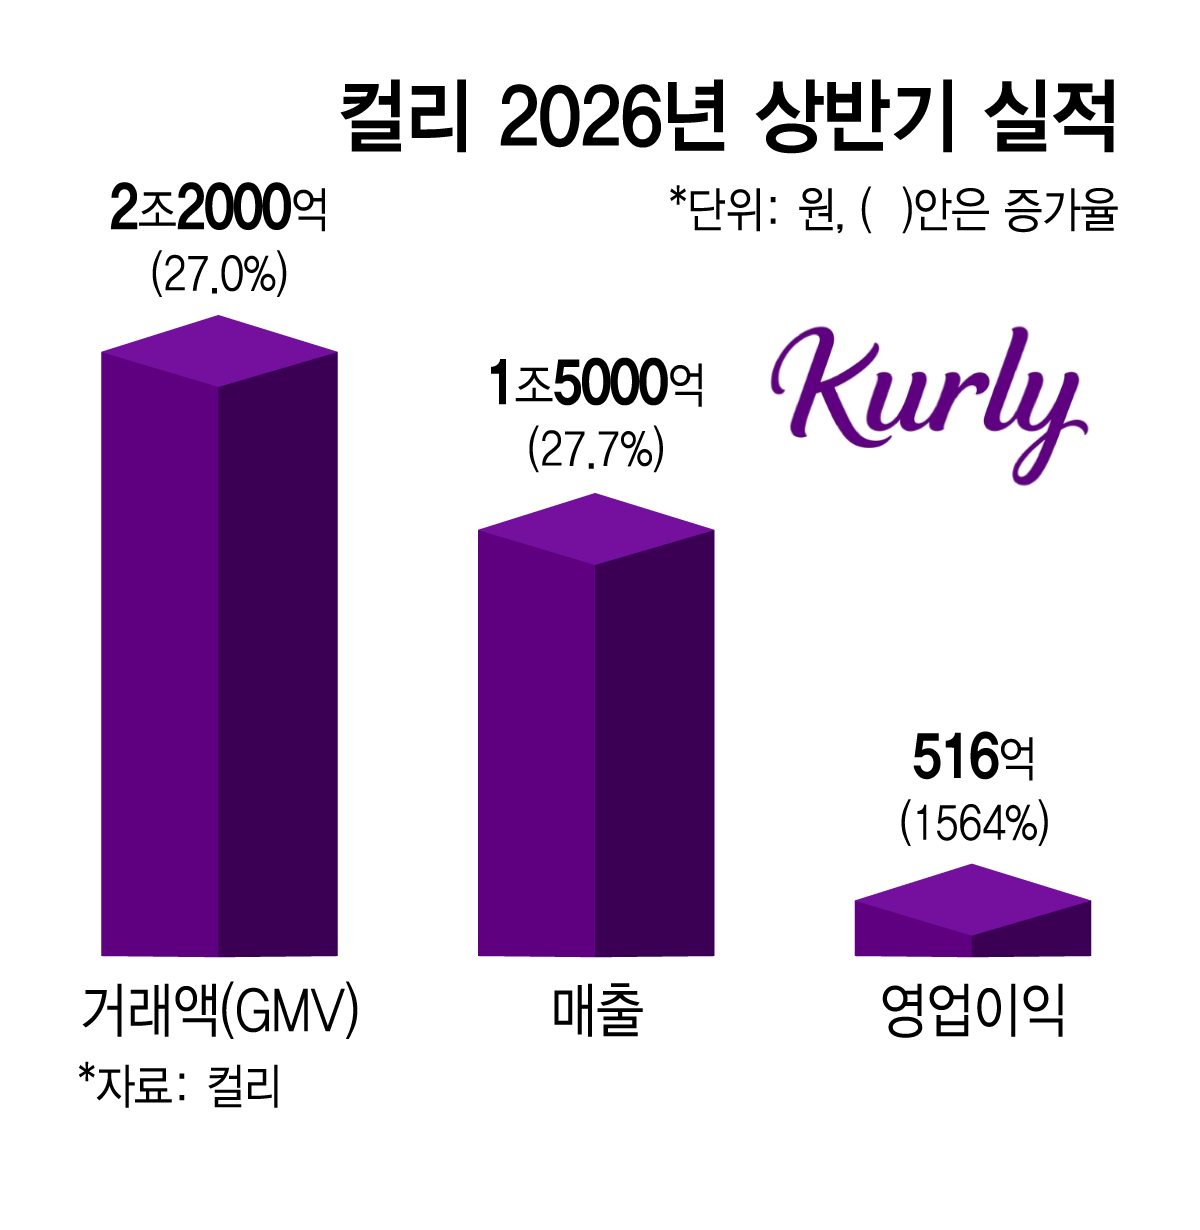
Curly recorded profits for six consecutive quarters from the first quarter of last year through the second quarter of this year. The scale of quarterly operating profit has increased significantly since the beginning of this year, resulting in an operating profit of 51.6 billion won in the first half alone. Curly's internal assessment is that it has built a foundation for independent growth without further reliance on external investment. This is the result of achieving both expansion and performance improvement simultaneously, based on continuous logistics efficiency improvements and a strategic alliance with Naver.
Curly's total gross merchandise value (GMV) in the first half of this year reached 2.2 trillion won, a 27% increase compared to the same period last year. Revenue was 1.5 trillion won, up 27.7% over the same period. This is the result of creating an 'economy of scale' as the number of loyal customers who frequently use Curly has increased. In fact, the number of paid members (Curly Members) paying 1,900 won per month grew more than fourfold in just over two years, from 300,000 in January 2024 to over 1.4 million by the end of last year.
Improvements in profitability were largely influenced by logistics efficiency. By increasing the utilization rates of the Gimpo, Pyeongtaek, and Changwon logistics centers, Curly reduced the proportion of logistics costs relative to revenue to the early teens percent range. The company's analysis indicates that increased bargaining power with suppliers due to higher GMV also improved gross profit margins, while the expansion of the seller-delivered goods (3P) business and cost-cutting strategies for selling and administrative expenses were also effective.
The strategic alliance with Naver, which has formed a duopoly in e-commerce alongside Coupang, has also yielded results. The recent GMV of 'Curly N-Mart' within the upcoming Naver Plus Store, launching next month to mark its first anniversary, is estimated to have increased approximately tenfold compared to the early launch period. Analysts suggest that Curly's early morning delivery competitiveness has created synergy with Naver Plus membership point benefits.
When Curly lists, its corporate valuation is estimated to reach around 3 trillion won. In May last year, Naver participated in a 33 billion won rights offering (paid-in capital increase) by Curly, raising its stake from 5.1% to 6.2%. Converting this to total equity share, Curly's corporate valuation is approximately 2.8 trillion won. As of the end of June this year, Curly's cash and cash equivalents were reported at 372.9 billion won, a 73% increase compared to the same period last year.
Although listing conditions have improved compared to the past, cautious opinions prevail within Curly. There are also concerns that due to recent sharp volatility in the domestic stock market and a concentration on specific large-cap stocks such as semiconductors, Curly may not receive its proper valuation.
CFO Kim stated, "Based on the high growth of our core business and new businesses, we will maximize corporate valuation to prepare an optimal foundation for a successful IPO in the future."
 in LIVING

