

The seven reports selected by the MoneyToday Securities Department for the fifth week of July (the 27th–31) are: △ "2Q26 Review: Despite Everything" by Cha Min-sook, Researcher at Korea Investment & Securities (SK Hynix); △ "Confirming Growth from New Products and Direct Sales Leverage" by Kim Jun-young, Researcher at Meritz Securities (Celltrion); and △ "Turnaround Market. Focus on Record North American Earnings" by Heo Je-na, Researcher at DB Securities (LG Household & Health Care), totaling three reports.
"SK Hynix to reach 4.7 million won"... Target price raised even as stock price halved
Cha Min-sook, a researcher at Korea Investment & Securities, raised SK Hynix's target price from 3.8 million won to 4.7 million won on the 30th and maintained its investment recommendation as "Buy" and "Overweight." Despite six out of the 14th securities firms covering SK Hynix (Daishin Securities, NH Investment & Securities, Shinhan Investment Corp., Samsung Securities, Hanwha Investment & Securities, and Kiwoom Securities) lowering their target prices that day, Cha alone maintained a bullish stance on raising the target price. This is the highest target price among those suggested by the securities industry for SK Hynix. As of the report's publication date, SK Hynix's closing price was 1.322 million won, down 55.74% from its high of 2.987 million won recorded on June 25.
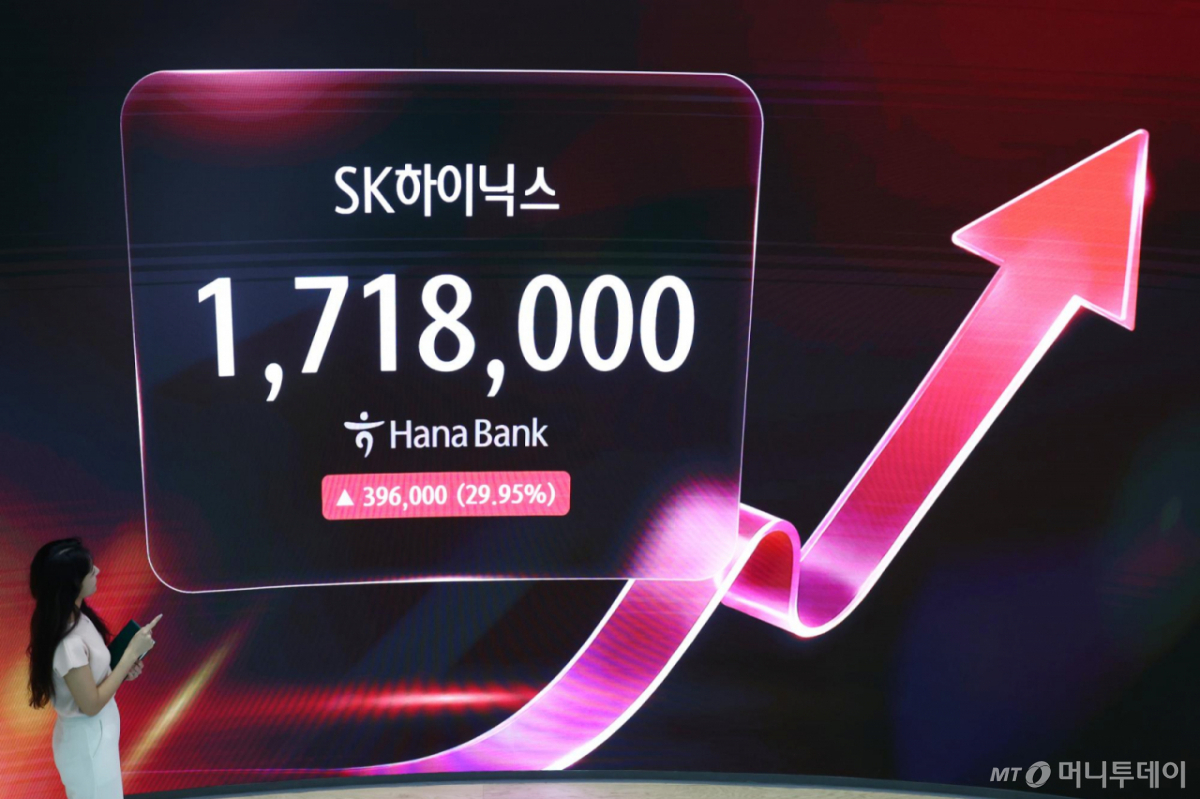
Cha researcher interpreted that the recent adjustment in SK Hynix's stock price was not due to changes in fundamentals but rather an expansion of market skepticism regarding the sustainability of AI (artificial intelligence) investments. In fact, as recognition spread that major tech companies such as Microsoft and Amazon in the U.S. have confirmed AI profitability and that deleveraging (financial stabilization through debt repayment) by large hedge funds has reached its latter stage, SK Hynix's stock price surged. On the 31st, SK Hynix closed trading at the daily limit of 1.718 million won, up 396,000 won (29.95%) in a single day.
Cha researcher also adjusted Samsung Electronics' target price upward from 590,000 won to 650,000 won on the 31st. This was a solo bet against the trend of other securities firms such as Mirae Asset Securities, BNK Investment & Securities, Shinhan Investment Corp., and Samsung Securities lowering their target prices for Samsung Electronics. Cha researcher emphasized that semiconductor supply shortages will intensify further in the second half of this year and next year, and that it is time to focus on the direction of corporate value and profits rather than short-term stock price fluctuations.
The following is a summary of the report. ()
☞'View Original Text' is available only on the MoneyToday website, not on portal sites such as Naver or Daum.
SK Hynix's second-quarter earnings missed consensus estimates by 6.4%, but its operating profit margin reached a record high of 76% for the quarter. DRAM and NAND operating profit margins are estimated at 78% and 67%, respectively. The main reason operating profits fell short of consensus estimates was that the DRAM price increase in the second quarter did not meet market expectations. However, SK Hynix analyzed that this was not due to demand slowdown but rather a delay in shipment timing, which will instead become a factor for improving third-quarter earnings. Although shipments of products in the second quarter were delayed into the second half of the year, causing combined ASP (average selling price) for the quarter to be lower than expected, DRAM prices in the third quarter are projected to rise by about 20% compared to the previous quarter, exceeding the initial estimate of 10%.
Reflecting this, annual operating profit estimates for 2026 and 2027 were revised upward by 10% and 11%, respectively, from previous levels to 2.7 trillion won and 4.18 trillion won. With ASPs expected to maintain high levels based on long-term supply agreements (LTA) of up to five years, the third quarter is also expected to see the full-scale shipment of HBM4 (high-bandwidth memory) from Yangsan, adding to the price increase effect for HBM.
Despite memory prices rising fourfold within a year compared to 2025, hyperscalers continue to invest in AI infrastructure. As customers request earlier shipments, production volumes are shipped immediately, leaving both memory suppliers and customers unable to secure sufficient safety stock.
Strong sales of new products and synergy from the North American direct sales system... Celltrion's second-quarter operating profit up 86%
Kim Jun-young, a researcher at Meritz Securities, maintained its "Buy" investment recommendation for Celltrion on the 28th and adjusted the target price upward from 266,887 won to 290,000 won. In fact, Celltrion's stock price rose 4.47% compared to the day before the report was published.
Kim researcher forecast that Celltrion's profit growth potential is increasing as it expands sales of high-margin new products and stabilizes its North American direct sales system. The proportion of revenue from Celltrion's new products expanded from 53% in the second quarter of last year to 65% in the second quarter of this year, and OPM (operating profit margin) improved by 7.2 percentage points to reach 32.4%.
The following is a summary of the report. ()
☞'View Original Text' is available only on the MoneyToday website, not on portal sites such as Naver or Daum.
Combined sales of five newly launched products in the second quarter reached 314.4 billion won, up 368.8% year-on-year and 48.8% quarter-on-quarter. In the second quarter of this year, U.S. Branchburg CMO (contract manufacturing organization) sales of 50 billion won did not contribute to operating profit because related gains and losses were adjusted to acquisition cost due to acquisition accounting. Excluding this, the OPM based on core business was 33.6%, confirming that growth from new products and the effect of alleviating fixed cost burdens through North American direct sales are leading to profit improvement.
Attention should be paid to the growth of new products including Omniclo and the normalization of Gimpenetra sales. As high-margin new products grow rapidly and the North American direct sales system stabilizes, the fixed cost leverage effect is fully underway, prompting an upward revision of next year's EBITDA (earnings before interest, taxes, depreciation, and amortization) estimate to 2.5353 trillion won.
Dr. Groot sells well... LG Household & Health Care turns profitable in North America, with a bright future ahead
Heo Je-na, a researcher at DB Securities, upgraded LG Household & Health Care's investment recommendation from "Neutral" to "Buy" and raised its target price by 52% from the previous level to 380,000 won on the 30th. While other securities firms such as Shinhan Investment Corp., NH Investment & Securities, KB Securities, LS Securities, Hyundai Motor Securities, Eugene Investment & Securities, and Kyobo Securities also adjusted their target prices for LG Household & Health Care upward after announcing earnings that exceeded market consensus estimates, the target price suggested by DB Securities is the highest.
Heo researcher forecast that as the North American subsidiary turned profitable, earnings visibility has increased, and it will maintain a profitable trend in the second half of the year due to high sales growth from entering new channels.
The following is a summary of the report. ()
☞'View Original Text' is available only on the MoneyToday website, not on portal sites such as Naver or Daum.
LG Household & Health Care's consolidated second-quarter operating profit was 102.8 billion won, exceeding expectations even after reflecting a one-time revenue of 15 billion won from U.S. tariff refunds (12 billion won for cosmetics and 3 billion won for household products). LG Household & Health Care's sales breakdown by overseas country is North America 35%, China 30%, Japan 18%, etc.
North American sales increased 46.6% year-on-year. North American sales surged significantly, led by Dr. Groot, setting a record high for sales. Despite expanded marketing expenses, the North American subsidiary recorded quarterly profits, and the proportion of revenue from its own brands reached 50%. It is scheduled to enter new channels including Sephora and Costco in the second half of the year.
In the second half of the year, while adjusting the duty-free supply volume for the main LINE of "The History," sales will turn to a growth trend as the base from last year's second half was low. LG Household & Health Care's current stock price is at a PER (price-to-earnings ratio) of 14 times based on expected net earnings over the next 12 months, presenting a buy opinion from the perspective of an earnings turnaround. The target price was calculated by applying a target PER of 15 times previously, 18 times for 2026, and 20 times for 2027.

 in STOCK


