

Amid discussions of potential fine-tuning by financial authorities regarding stricter market capitalization (hereinafter "market cap") criteria for listed company delisting (hereinafter "delisting"), Korea Exchange has decided to revise KOSDAQ implementation rules to account for the illusion where companies appear to have a smaller market cap due to temporary price adjustments following capital increases or dividends. This move comes amid persistent market backlash against the notion that profitable companies could be delisted simply because their market cap falls below the threshold, drawing significant attention.
According to the financial investment industry on the 31st, Korea Exchange (KRX) will amend KOSDAQ listing regulations implementation rules to consider cases where temporary price adjustments occur due to rights issues or stock dividends following paid-in capital increases or bonus share issuances (free share issuance), which affect market cap calculations for delisting purposes. KOSPI already implemented identical changes to its implementation rules on the 27th.
Since July, a policy has been in effect requiring companies listed on KOSPI to maintain a market cap of at least 30 billion won and those on KOSDAQ at least 20 billion won to avoid delisting criteria. Given that this rule amendment is being introduced under the current framework, it is expected that the revised implementation rules will be applied when determining whether to designate stocks as management-targeted or proceed with delisting due to insufficient market cap.
Previously, rights issues or dividend payments caused temporary price adjustments, creating an illusion where market capitalization appeared smaller than it actually was. For example, in a bonus share issuance (free share issuance), the stock price drops to reflect the increase in outstanding shares, but since the number of shares used in market cap calculations has not yet increased, the market cap temporarily appears smaller.
Assume a listed company with 10 thousand won shares at 20,000 won per share, resulting in a market cap of 20 billion won. If this company conducts a one-for-one bonus share issuance (free share issuance), an additional 10 thousand won shares will be issued, potentially adjusting the stock price to 10,000 won. Consequently, until the new shares are officially issued, the market cap may temporarily drop by half.
This situation is critical for listed companies hovering around delisting thresholds, which is why the relevant implementation rules were amended. An exchange official stated, "Since identical changes to KOSPI implementation rules have already taken effect, we expect KOSDAQ standards to be revised by early September."
The exchange's move is noteworthy as it aligns with the financial authorities' policy direction, which acknowledges that while major changes to delisting policies are difficult, fine-tuning measures should be considered.
On the 24th, Financial Services Commission Chairman Lee Eoung-won addressed market concerns that stricter market cap criteria could lead to profitable companies becoming targets for delisting. He stated, "Considering the credibility of current policies, a complete policy overhaul is not feasible, but we will examine whether there are areas for fine-tuning."
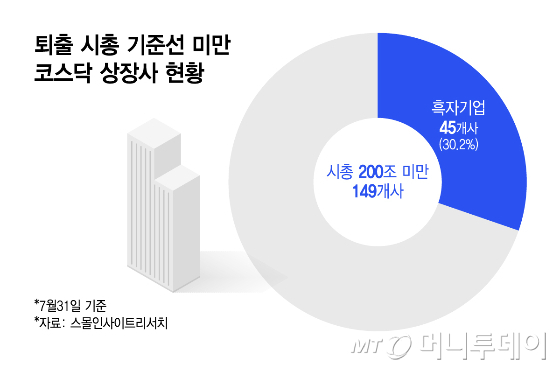
In fact, data released by Democratic Party of Korea lawmaker Kim Hyun-jeong on the same day showed that as of late July, among 149 KOSDAQ-listed companies with a market cap below 20 billion won, 45 were profitable. With the National Assembly calling for supplementary measures and financial authorities promising fine-tuning, it is highly likely that adjustments in formats such as this exchange rule amendment will continue to follow.
However, some view that the impact on the market may not be significant, as companies near delisting thresholds are unlikely to have the capacity to raise capital through equity issuance or distribute dividends.
An official from the securities industry stated, "There is a growing opinion that supplementary procedures must be substantively established to verify a company's operational foundation and recovery potential, ensuring its continuity." The official added, "Policies should not send a signal to the market that short-term stock prices and market cap management are more important than innovation."

 in STOCK
