

As volatility in the stock market has recently increased, there have been repeated instances of large-scale capital outflows from investors, lending weight to arguments that long-term investment funds must be attracted to resolve this. There are calls to restructure retirement pension benefits to encourage long-term stock investment, similar to the Long-Term Special Deduction for real estate.
According to the financial investment industry on the 26th, opinions are emerging that tax incentives are needed to attract long-term investment funds as part of additional measures to advance the capital market. This is from the perspective of expanding the benefits of retirement pensions, which form the foundation of long-term investment funds, to establish a stable supply and demand base.
As stock market volatility has recently increased, the need for inflows of long-term investment funds has grown. Kim Jun-seok and Jang Geun-hyuk, senior research fellows at the Korea Capital Market Institute, stated in their July report, "Reviewing the Background of Rising Stock Market Volatility," that "stock price volatility is an inevitable characteristic that appears in the process of discovering a company's value." They added, "However, volatility unrelated to changes in a company's intrinsic value, such as worthless information, overreaction, and clustered trading, is unnecessary and impedes the function of the stock market while lowering its credibility."
Therefore, policies should focus on mitigating unnecessary short-term volatility. To this end, they proposed strengthening the foundation for domestic long-term institutional investors. Expanding long-term institutional investors involves not only increasing the scale of massive public pensions like the National Pension Service but also expanding based on individuals' long-term investment funds through retirement pensions and similar vehicles.
Investing in domestic stocks actually results in a 'loss'…Incentives for long-term holding are also 'insufficient'
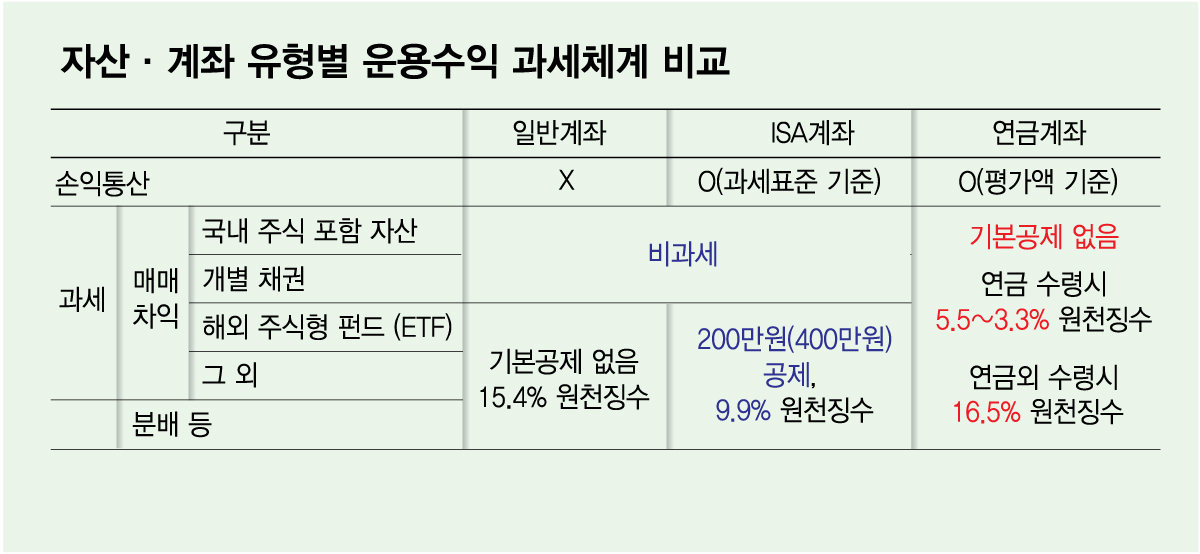
However, it is pointed out that current tax incentives for retirement pensions are insufficient to attract investors. Investing in domestic equity funds through a retirement pension account actually results in a loss.
When trading domestic equity funds in a general stock account, capital gains are tax-exempt, but in a pension account, a tax of 3.3% to 5.5% (upon pension receipt) is applied. This is because pension accounts are characterized by taxing the entire management return. Regardless of whether the investment is in deposits, domestic equity funds, or other products, taxes are levied only on the profit gained relative to the principal.
For this reason, retail investors are increasingly using retirement pension accounts to invest in overseas equity funds. Investing in overseas equity funds in a general stock account incurs a 15.4% tax on capital gains, but investing through a retirement pension significantly reduces the tax burden. Moreover, investors can enjoy benefits such as tax deferral and netting of profits and losses across multiple products.
A financial investment industry official said, "It is already widespread among investors that putting domestic stock products into retirement pensions is disadvantageous, while investing in overseas products is more favorable." They added, "Retirement pension accounts, which should attract long-term domestic investment funds, are instead encouraging capital outflows to overseas markets." Therefore, there are arguments for introducing a scheme to exempt capital gains on domestic equity products within retirement pension accounts.
Incentives to encourage long-term accumulation in retirement pensions are also lacking. Currently, retirement income tax is reduced based on how long the pension is received over time. For example, if a severance pay is received as a pension spread over 20 years, the tax is reduced by 50%.
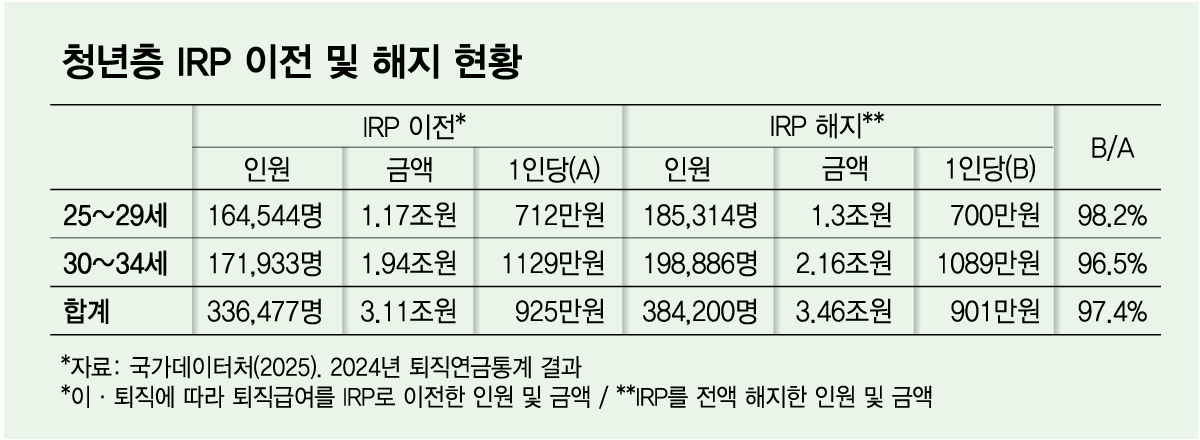
However, for young people who frequently change jobs or retire, the effect of retirement income tax reductions that occur only 20 to 30 years in the future is difficult to feel. According to the "2024 Retirement Pension Statistics" from the National Data Agency, the amount transferred to Individual Retirement Pensions (IRP) by young people aged 25 to 34 due to job changes or retirement was 9.25 million won per person, of which 9.01 million won (97%) was canceled. An IRP is an account where individuals can receive transferred severance pay or additionally deposit and manage funds to receive them as a pension after the age of 55. The statistics show that most young people prefer to withdraw their severance pay in a lump sum rather than managing it as a pension.
In response, the industry proposes improving the system by reducing retirement income tax based on the period during which the IRP is maintained without withdrawing the severance pay in a lump sum. This is a method of reducing taxes based on how long the severance pay is held without being broken up.
Another industry official explained, "Because the reduced tax amount is visible, it can create an incentive for long-term holding." They added, "If investors are informed that 'the tax reduction benefits accumulated over 5 years become zero upon mid-term cancellation,' they can visually confirm the loss, which will also serve as a mechanism to prevent cancellations."

 in STOCK

