

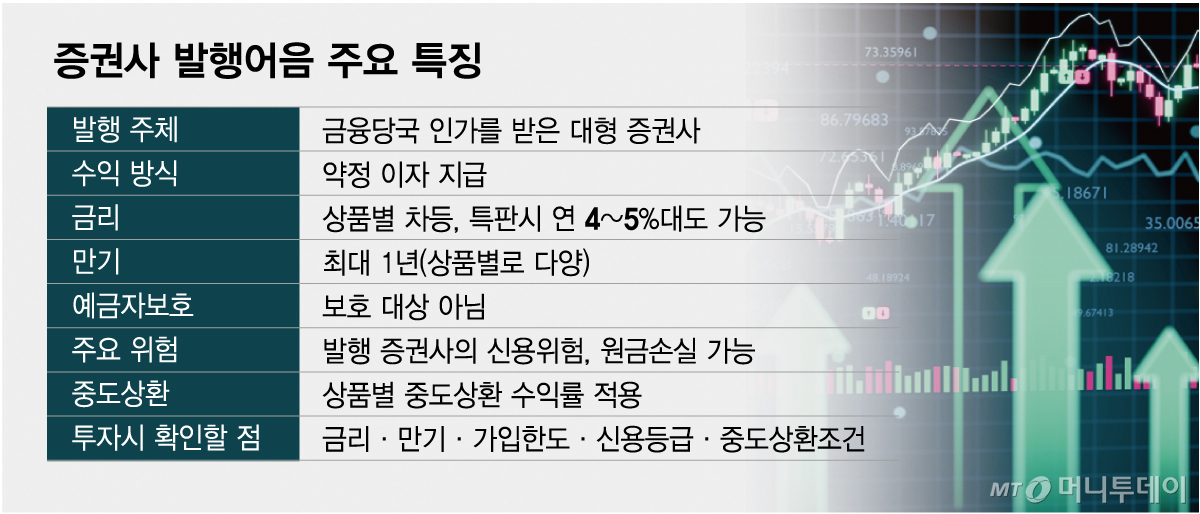
Brokerages have stepped up competition to attract retail investors through the launch of new bankers' acceptance products, high-interest special offerings, and mass-market advertising. As the number of licensed bankers' acceptance operators has grown to nine, bankers' acceptances—previously a funding tool for brokerages—are establishing themselves as investment vehicles for managing individuals' lump sums and short-term idle funds. While this creates a new investment opportunity with interest rates potentially higher than bank deposits, experts point out that because these products are not covered by depositor protection, investors must carefully assess the issuer's credit risk and actual return conditions.
According to financial investment industry sources on the 26th, competition among brokerages is intensifying as Samsung Securities and Meritz Securities received new licenses, bringing the total number of bankers' acceptance operators to nine. The firms are producing advertisements emphasizing high interest rates and easy enrollment, while launching a diverse range of products, including fixed-term plans for entrusting lump sums for a set period, demand deposit-type accounts, and Comprehensive Asset Management Account (CMA) type products.
Samsung Securities, which recently received a license to operate bankers' acceptances, has produced TV commercial-style advertisements to promote the product on platforms such as YouTube. Two 30-second ad videos titled "A New Standard for Bankers' Acceptances" and "Trust Is Important for Bankers' Acceptances" have each recorded several million views on YouTube. This effort to introduce the relatively unfamiliar product to general retail investors and generate interest demonstrates a shift in bankers' acceptances expanding their reach as a mainstream financial product.
In fact, the market size has also grown. According to the Financial Services Commission, the outstanding balance of bankers' acceptances issued by the seven brokerages previously licensed increased from 51.2744 trillion won at the end of last year to 55.9291 trillion won at the end of the second quarter this year. The balance grew by nearly 10% in the first half of this year alone.
The expansion of the bankers' acceptance market signifies that retail investors have gained broader options for managing their idle funds. This is because they now have the opportunity to allocate money previously held in bank time deposits or parking accounts into bankers' acceptances.
A banker's acceptance is a financial product with a maturity of one year or less, issued by a major brokerage licensed by financial regulators using its own credit. When an individual purchases a banker's acceptance, it is effectively lending money to the brokerage, which has an obligation to repay the principal and interest as agreed upon at maturity. While investors can expect a fixed interest rate similar to a deposit, the legal nature differs from depositing money in a bank.
Investors must calculate the actual interest they will receive when investing in bankers' acceptances. Not everyone earns returns equivalent to advertised special rates of over 5% annually. Some products impose enrollment limits or offer benefits only to new customers. Interest rates displayed in advertisements are typically pre-tax annualized yields based on a one-year period. For example, if an investor puts 1 million won into a three-month maturity banker's acceptance with a pre-tax annual interest rate of 5.8%, the pre-tax interest would be approximately 14,500 won, and the after-tax interest approximately 12,300 won. These are simple calculated amounts; actual interest varies depending on factors such as the number of days until maturity. Therefore, investors should verify the actual amount they can invest and the maturity period, rather than focusing solely on the highest advertised rate.
When an investor needs to use their funds is also important. For fixed-term bankers' acceptances, a lower yield may be applied if redeemed before maturity compared to the originally agreed rate. On the other hand, while demand-type or CMA-type products allow for relatively free withdrawal of funds, their interest rates may be comparatively lower.
A key risk that retail investors must understand is the credit risk of the issuing brokerage. Even if a brokerage incurs losses during its operations, those losses are not immediately passed on to investors. However, if financial soundness deteriorates and the brokerage fails to repay principal and interest, investors may also suffer losses. In particular, unlike bank deposits, bankers' acceptances are not covered by depositor protection.
An industry official in the securities sector advised, "More important than a high interest rate is judging whether the additional interest earned is sufficient relative to the risks one bears."

 in STOCK
