
CJ CGV is moving to issue 120 billion won worth of convertible bonds (CBs). The company has posted growth this year, supported by an improving industry environment and stronger performance from its subsidiaries.
It has also strengthened its financial position by issuing hybrid securities with credit support from its holding company, CJ Corp. Attention is now focused on whether the CB offering will prove popular among institutional investors seeking potential returns from future share price gains.
According to industry sources on Monday, CJ CGV is expected to issue bearer, coupon-bearing, unsecured private placement CBs worth 120 billion won as early as next month.
Four securities firms—Shinhan Investment Corp, Korea Investment & Securities, Hanyang Securities, and NH Investment & Securities—are participating as underwriters or lead managers. However, the lead manager for the issuance has not yet been finalized. The total issuance amount is expected to be determined based on the investment funds raised by these institutional investors.
According to a term sheet (key terms document) circulating in the market, the CBs have a maturity of five years, with both the coupon rate and the yield at maturity set at 0%. Neither the issuer, CJ CGV, nor its largest shareholder, CJ Corp (holding a 50.90% stake as of the end of June last year), holds call options (the right to demand redemption) that would allow them to buy back the CBs from investors.
Investors can exercise put options (the right to demand early repayment) every three months starting two years after issuance. The period for requesting conversion into shares runs from one year after issuance until one month before maturity.
There is no adjustment of the conversion price (repricing) in response to a decline in market price. Given that both the coupon rate and the yield at maturity are 0%, the structure has been designed so that investors can recover their funds if stock prices do not rise and investment returns cannot be expected.
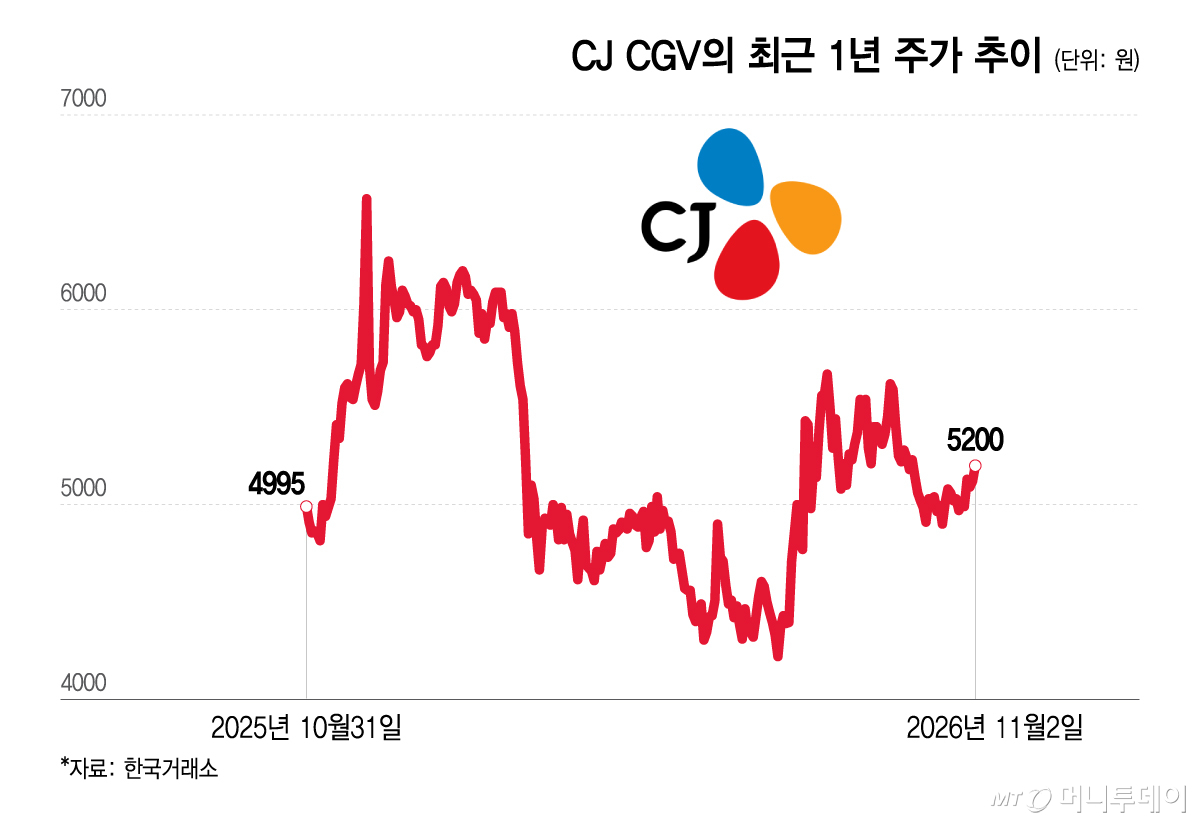
CJ CGV’s current stock price is in the 5,000 won range. It has steadily declined from the 24,000 won range in 2021, when the number of people visiting cinemas dropped sharply due to the COVID-19 pandemic, to its current level.
Since the beginning of this year, CJ CGV has shown a different approach to fundraising compared to last year. On April 30 and May 28, the company issued new capital securities totaling 600 billion won in two tranches. The issuance was successful thanks to support from its holding company, CJ Corp, which signed a funding replenishment agreement.
In contrast, last year, demand for 40 billion won worth of new capital securities amounted to only 10 billion won, and the entire 100 billion won corporate bond issuance remained unsold. Ultimately, the company navigated the crisis by raising 80 billion won through P-CBOs (Primary Collateralized Bond Obligations), a credit guarantee scheme provided by the Korea Credit Guarantee Fund for companies with low credit ratings.
Profitability is also improving. Domestic audience numbers in the first half of this year reached 57.05 million, a 34.2% increase from the same period last year, marking the highest level since the onset of the COVID-19 crisis.
This was driven by hit films that attracted 10 million viewers each, such as "The King's Warden," "Odyssey," and "Spider-Man: Brand New Day." Cost reduction efforts are also underway; the number of cinemas decreased by 20 over the past year and a half to 176 as of the end of June.
Consolidated operating profit in the first half was 20.2 billion won, up 310% from the same period last year, while EBITDA (earnings before interest, taxes, depreciation, and amortization) rose 21.8% to 178.8 billion won. The securities industry is expecting CJ CGV to turn a profit in the third quarter.
Expansion through subsidiaries is also continuing. CJ 4DPLEX, a subsidiary responsible for installing global technology-specialized screens and producing exclusive content, received approval from the Financial Services Commission in August for an investment of 220 billion won in redeemable convertible preferred shares (RCPS). The Advanced Strategic Industry Fund invested 50 billion won, while private financial institutions, including Glenwood Credit and GNP Investment, invested 170 billion won.
CJ Olive Network, a wholly-owned subsidiary handling system construction and operation for group affiliates as well as external IT services, received an "A+/Stable" rating from two credit rating agencies. CJ Olive Network became a wholly-owned subsidiary of CJ CGV in 2024 when CJ Corp made a capital contribution in kind worth 444.4 billion won.
 in STOCK
