
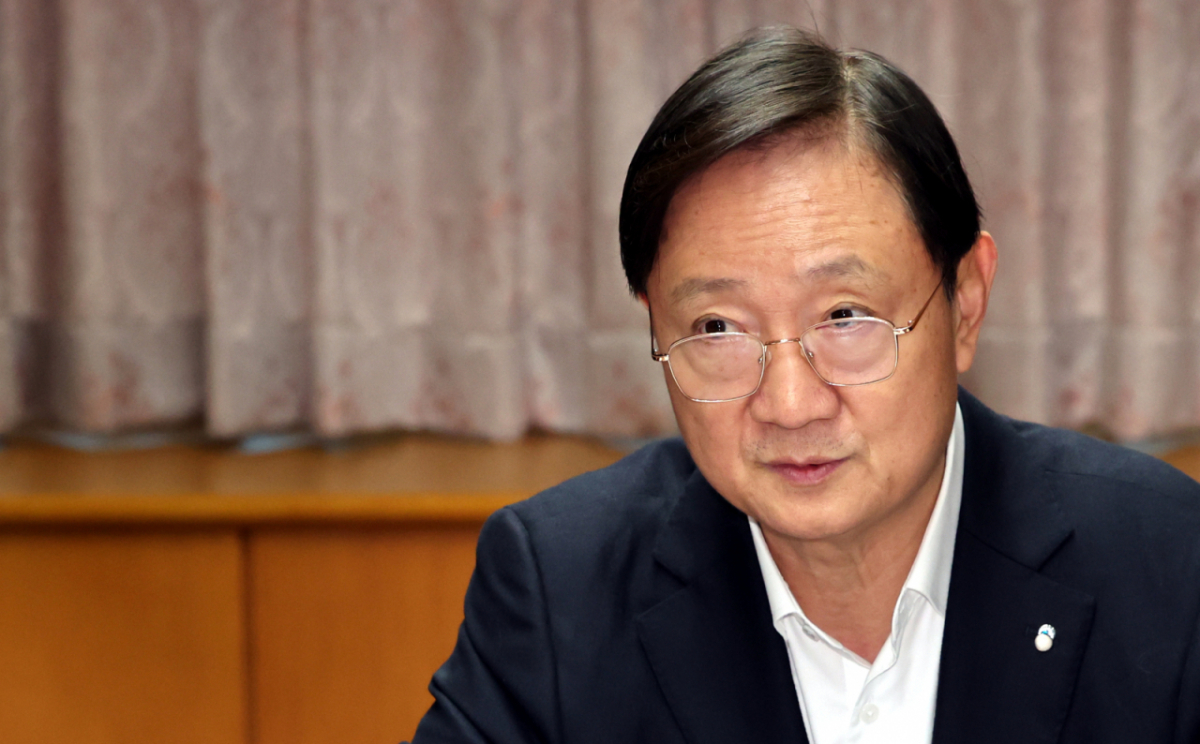
To detect accounting fraud in a timely manner, the Financial Supervisory Service will shorten the review and inspection cycle for listed companies from the current 20 years to 3-5 years. It will strengthen sanctions against serious accounting fraud such as intentional financial statement manipulation and improve internal control systems so that accountability can be pursued for legal violations by accounting firms.
Financial Supervisory Service Governor Lee Chan-jin announced this on the 10th during a meeting with CEOs (chief executive officers) and experts from eight accounting firms responsible for external audits of listed companies.
First, the accounting review and inspection cycle will be shortened. Governor Lee stated, "The review and inspection cycle for Korean listed companies is approximately 20 years, significantly exceeding the typical management tenure (3-5 years), making it difficult to identify accounting fraud in a timely manner," adding, "To resolve this supervisory gap, we will establish a periodic review system at the level of major advanced countries such as the United States and the United Kingdom." The U.S. review cycle is three years for all listed companies, while the U.K. cycle is five years for FTSE 350 constituents (the top 350 companies listed on the London Stock Exchange).
To this end, plans are in place to expand the organization and personnel responsible for reviews and inspections, strengthen inspection tools, and upgrade supervisory infrastructure. Previously, the Financial Supervisory Service announced its policy of advancing a roadmap to shorten the review and inspection cycle and communicating with the National Assembly for legislative amendments.
The financial statement review system has been implemented since 2019 following the comprehensive revision of the External Audit Act in 2017, aiming to enhance the reliability of financial information through the prompt correction of accounting errors. It involves analyzing anomalies in disclosed financial statements without on-site visits to check for violations of accounting standards (accounting review), and converting cases into inspection investigations if suspicions of accounting violations are found.
Strict sanctions will be imposed on serious accounting fraud. Recently, supervisory authorities have prepared measures to improve the accounting oversight system, including raising penalties for intentional financial statement manipulation and strengthening sanctions against acts that obstruct accounting audits and reviews/inspections.
Governor Lee emphasized, "Starting this year, with the abolition of the cap on reward payments for reporting, reports of accounting fraud have surged compared to the past," adding, "Going forward, when accounting fraud involving significant intent is discovered, we will apply a zero-tolerance principle and impose strict sanctions. We will also further strengthen supervision of accounting firms where audit failures recur."
Improvements to the internal control systems of accounting firms were also foreshadowed. Governor Lee stated, "In the past, there was a tendency to attribute incidents to individual deviations by accountants, but we will boldly improve the system so that management and supervisory responsibility for the internal controls of accounting firms can be more broadly and strictly pursued, in line with international trends."
Supervision of accounting firms will also be strengthened. This comes amid growing concerns over declining audit quality, such as reduced personnel and time allocated to audits due to falling audit fees resulting from excessive competition for engagements among accounting firms. Selective additional reviews and inspections are planned for companies and auditors where audit time has decreased excessively without reasonable justification or where signs of inadequate auditing exist. Supervision will also be conducted on whether the "Audit Quality Oversight Committee" established within large accounting firms is fulfilling its role.
Additionally, with the implementation of new Korean Accounting Standard No. 1118 (Presentation and Disclosure in Financial Statements) starting next year, the basic structure of income statements is expected to change. He also requested that accounting firms play a role in ensuring the new standard settles stably in the market. He further ordered a re-examination of information security systems to prevent the leakage or misuse of important corporate information due to the introduction of digital auditing techniques.
 in STOCK
