

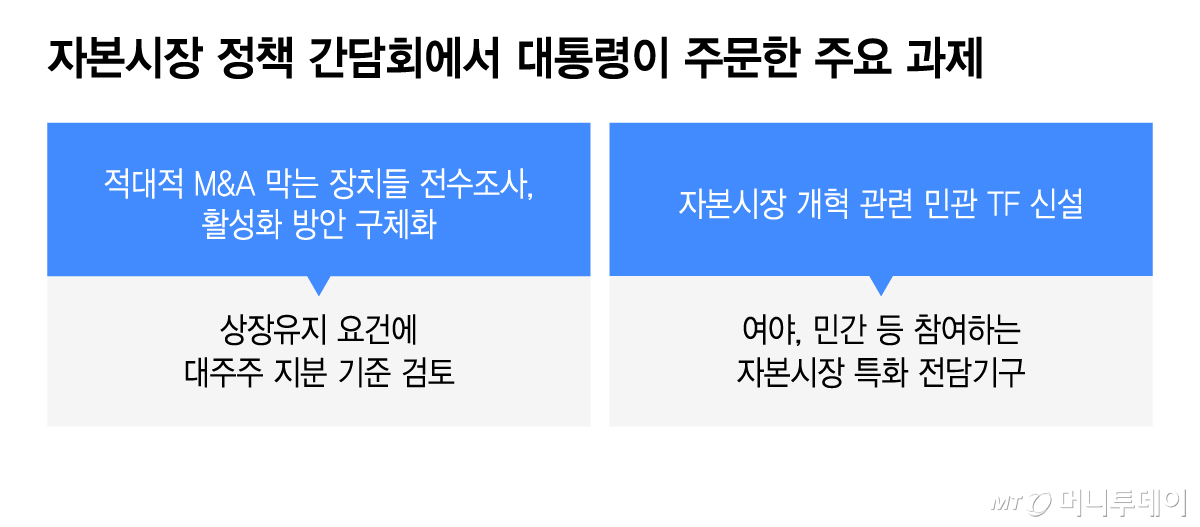
President Lee Jae Myung has called for a series of capital market reforms, ranging from a public-private task force to promote hostile M&As as a way to revive undervalued companies with low price-to-book ratios.
His remarks have left financial regulators weighing how to proceed. Lee also cited major shareholders' high ownership stakes as an obstacle to hostile takeovers and raised the possibility of delisting companies, raising concerns over potential harm to minority shareholders.
According to financial industry sources on Tuesday, regulators began reviewing follow-up measures after a capital market policy meeting presided over by Lee on Nov. 13.
According to the financial investment industry on the 17th, the financial authorities have begun reviewing follow-up tasks for capital market reform after the capital market policy roundtable chaired by President Lee on Nov. 13.
At the roundtable, President Lee ordered the creation of a public-private joint TF responsible for capital market reform. The TF is a body in which the government, ruling and opposition parties, relevant agencies, and industry and market officials participate to identify and improve capital market issues.
Lee said that he would designate a high-level head and receive direct reports. This is interpreted as an intention to form a specialized capital market TF to drive capital market policy forward.
The order followed remarks by Professor Hwang Hyun-young of the Korea Capital Market Institute at the roundtable, who noted the need for a long-term blueprint related to the capital market.
Hwang said, "The UK has the Cadbury Report, Japan has the Ito Report, and Taiwan has been publishing roadmaps for its capital market and corporate governance for a long time," adding, "We also need a long-term blueprint regarding structural issues (related to the capital market)."
As a measure to normalize low-PBR companies, President Lee ordered that options for delisting companies with excessively high major shareholder ownership ratios should also be explored, alongside activating hostile M&A.
He pointed out that while M&A is a method to check low-PBR companies, it does not function when the major shareholder's ownership ratio is as high as 70% to 80%. However, side effects such as harm to minority shareholders are also a concern.
At the roundtable, Lee said, "Shouldn't we prevent them from effectively running monopolistic management while enjoying all the profits from growth?" and added, "In listing maintenance conditions, if the major shareholder's ownership ratio exceeds half, making control contests impossible, or if it is operated too much like a personal company—50% may be appropriate, but shouldn't we explore options to delist such companies from the market?"
He further ordered a comprehensive investigation into mechanisms blocking hostile M&A and a review of measures that could activate them.
Typically, stocks with a PBR below 1 are classified as undervalued shares. This means the value assessed in the stock market is lower than the company's asset value.
Companies with many assets and stagnant growth are often in a perennial low-PBR state. The industry points out that there are 570 companies where the major shareholder's ownership ratio exceeds 50% and the PBR is below 1, making hostile M&A impossible. It is explained that if the controlling shareholder's ownership ratio exceeds 50%, external activist funds or hostile M&A acquirers cannot threaten management control even if they secure shares.
However, voices are emerging that caution is needed in institutional design because strengthening delisting requirements could lead to harm for minority shareholders.
If a company undergoes the delisting process, it becomes difficult for minority shareholders to recover their investment funds, and even if companies decide on voluntary delisting due to strengthened requirements, minority shareholders will suffer losses. Undervalued companies may also be exposed to attacks by speculative capital or overseas activist funds rather than healthy checks.
An official from the financial investment industry said, "In trying to check major shareholder stakes, various side effects can arise, such as harm to minority shareholders due to delisting, increased exposure to hostile M&A, and companies consuming resources on defending management control rather than long-term investment or strategy formulation, making it difficult for the financial authorities to reach a quick conclusion."

 in STOCK
