

Strengthened household loan management by the financial sector led to the smallest new household loans per borrower in over three years during the second quarter of this year. In particular, home mortgage loans decreased significantly, especially among the 30s and 40s who have high demand for home purchases and in the capital region. On the other hand, mortgage loans for the 20s, which have a higher proportion of first-time buyers and non-homeowners with relatively less loan regulation, increased.
According to the Bank of Korea's "Second Quarter Household Debt Statistics by Borrower (Preliminary)" released on the 25th, new household loans per borrower in the second quarter amounted to 34.14 million won, a decrease of 1.28 million won (3.6%) from the previous quarter. This is the lowest level since the first quarter of 2023.
New loans per borrower had fallen to 34.43 million won in the fourth quarter of last year before rebounding to 35.42 million won in the first quarter of this year, but decreased again within a single quarter.
Min Suk-hong, head of the Household Debt Microstatistics Team at the Bank of Korea, explained, "Due to recent loan regulations and other factors, the amount of additional loans for existing borrowers or the size of newly processed loans has shrunk, leading to a decrease in new loans per borrower."
By age group, the 40s saw the largest decline, with new loans per borrower falling by 5.83 million won to 35.88 million won from the previous quarter. This is the lowest level since the fourth quarter of 2022. The 30s also recorded a decrease of 2.74 million won, reaching 49.08 million won.
The 50s and those aged 60 and above saw decreases of 650,000 won and 480,000 won respectively, ending at 30.10 million won and 26.72 million won. In contrast, the 20s increased by 2.60 million won to 20.56 million won, the highest level since the second quarter of last year.
By region, new loans per borrower in the capital region decreased by 1.93 million won to 37.80 million won. Seoul dropped by 4.71 million won from 48.18 million won to 43.47 million won, while Gyeonggi and Incheon also saw a decrease of 530,000 won, reaching 34.91 million won.
By product type, the decline in home mortgage loans was prominent. New home mortgage loans per borrower in the second quarter amounted to 282.9 million won, a decrease of 21.10 million won (9.2%) from the previous quarter. This is the lowest level since the fourth quarter of 2024.
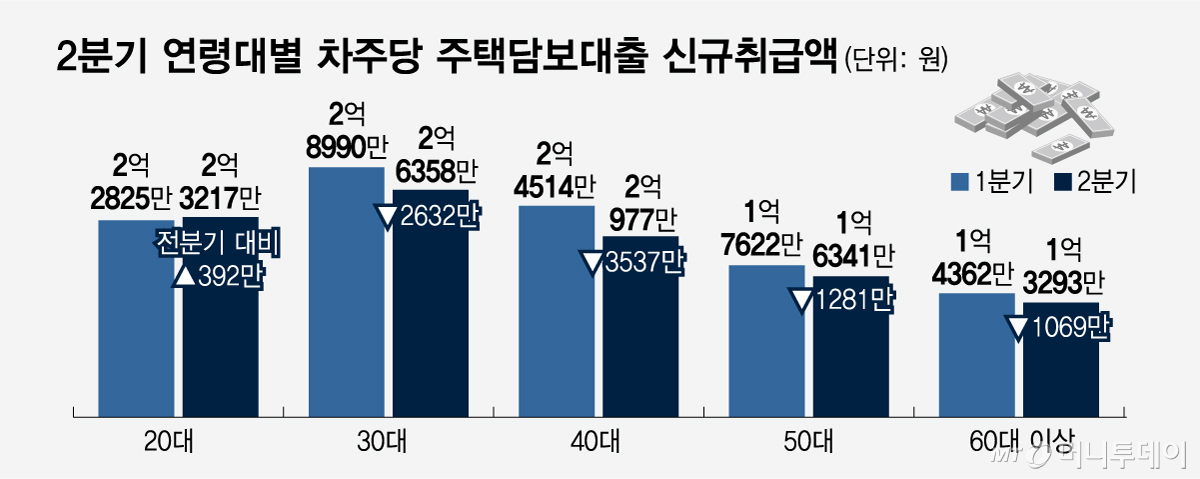
New home mortgage loans for the 40s decreased by 35.37 million won to 297.7 million won from the previous quarter. The 30s also saw a decrease of 26.32 million won, reaching 263.58 million won. The 50s and those aged 60 and above also decreased by 12.81 million won and 10.69 million won respectively.
In contrast, new home mortgage loans for the 20s increased by 3.92 million won to 232.17 million won, exceeding that of the 40s. Team Leader Min stated, "The 20s have a relatively higher proportion of non-homeowners and first-time homebuyers compared to other age groups, and loans for these individuals are relatively less restricted in terms of regulations."
However, the 20s accounted for only 6% of total new home mortgage loans. Team Leader Min explained, "The 20s who can receive home mortgages are borrowers who meet loan conditions such as income verification," adding, "Compared to all 20s, the average loan amount may appear relatively large."
New home mortgage loans per borrower in the capital region decreased by 43.97 million won to 230.59 million won from the previous quarter. Seoul saw a sharp drop of 60.65 million won to 271.40 million won, while Gyeonggi and Incheon decreased by 33.48 million won to 213.49 million won. This is believed to be due to an increase in transactions for mid-to-low-priced homes in the capital region and the impact of loan limit regulations.
On the other hand, new home mortgage loans in the Honam region increased by 11.13 million won to 173.15 million won as loans related to housing developments rose in some areas such as Gwangju and Jeonju.
By industry sector, non-bank institutions saw a sharp decline of 61.22 million won in new home mortgage loans, reaching 166.82 million won. Banks also saw a decrease of 12.40 million won, ending at 216.97 million won.
Among total household loans, new Jeonse (rental deposit) loans decreased by 5.77 million won to 145.35 million won. In contrast, credit loans increased by 470,000 won to 19.70 million won, and other loans including card loans, auto installments, leases, and student loans also increased by 730,000 won to 12.80 million won. This is explained as likely being used for stock market investment funds.
Although new loans decreased, the outstanding household loan balance per borrower increased. At the end of the second quarter, the outstanding household loan balance per borrower was 97.90 million won, an increase of 500,000 won from the previous quarter. The outstanding home mortgage loan balance increased by 1.87 million won to 161.93 million won, and the outstanding Jeonse loan balance increased by 880,000 won to 120.51 million won.
Team Leader Min explained, "The outstanding balance is largely composed of loans held by existing borrowers," adding, "In the second quarter, the amount repaid decreased compared to the previous quarter, so the amount leaving the balance was smaller, causing new loan amounts and balances to move in opposite directions."
There is also a possibility that new loan amounts will increase again in the third quarter, centered on group loans. Team Leader Min stated, "With the expansion of total household loans due to the the 13th measures, it is expected that a significant portion will be implemented through group loans, which could lead to an increase in new loan amounts," while also noting, "We need to continue monitoring the trend of strengthened household loan management, the housing market in the capital region, and the movement of funds from the money market to the stock market."

 in FINANCE

