
The recent suspension of sales for the '700 Whole Life Insurance' product has prompted life insurance companies to reshape the market with new whole life insurance offerings. They have been successively unveiling products that combine death benefits with features such as access to funds during the policyholder's lifetime or premium refunds. Insurers that were previously aggressive in selling the '700 Whole Life' need to secure alternative products, while insurers that did not offer the '700 Whole Life' are rushing to launch new products to expand their market share in a landscape where this powerful product has disappeared.
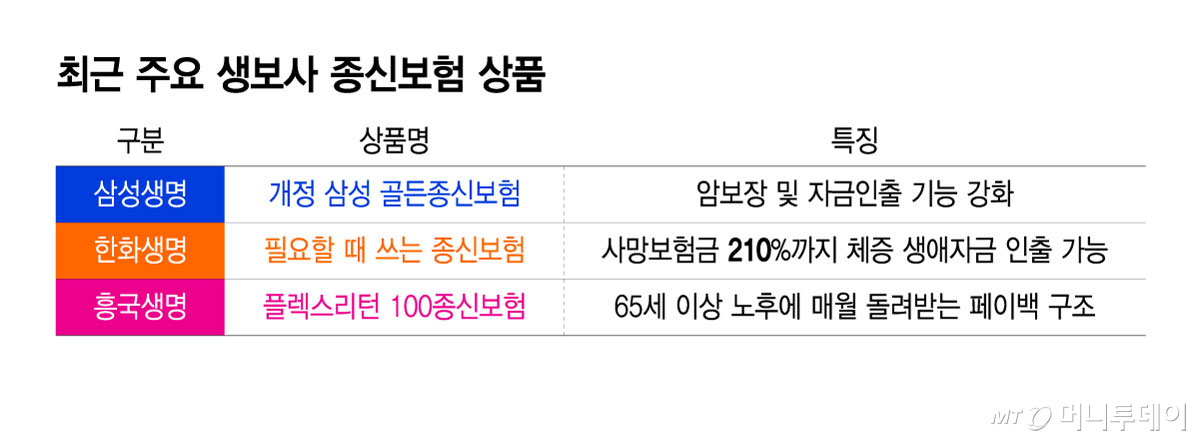
According to the insurance industry on the 18th, Samsung Life recently revised its 'Samsung Golden Whole Life Insurance' to strengthen cancer coverage and fund withdrawal features. Hanwha Life launched the 'Hanwha Life Whole Life Insurance for When You Need It,' and Heungkuk Life introduced the 'Flex Return 100 Whole Life Insurance.' It is unusual for life insurers to release new whole life insurance products so frequently on a daily basis.
The revised whole life insurance product from Samsung Life is characterized by waiving premium payments upon a cancer diagnosis and supporting additional fund withdrawals. Hanwha Life combined a compound structure where the death benefit can increase up to 210% with a lifetime fund withdrawal feature. Heungkuk Life highlighted a payback structure that returns premiums monthly in retirement.
The suspension of sales for the '700 Whole Life' insurance is behind the launch of these products. The '700 Whole Life' insurance allowed policyholders to enjoy whole life insurance benefits while paying premiums for seven years, with a refund rate of 100% or more available after seven years. As existing short-term payment whole life policies disappeared, it quickly established its position in the market through corporate insurance agencies (GAs) and other channels. However, new sales have been effectively halted due to low policy retention rates. Financial regulators expressed concern that mass cancellations occurring immediately after the principal amount is reached could undermine the soundness of insurance companies.
However, perspectives on the market vary by company. Life insurers that had relied on the '700 Whole Life' are urgently seeking alternatives. In the case of Hanwha Life, after being unable to sell the well-received '700 Whole Life,' it is in a situation where it must offer whole life insurance products suitable for use in sales operations. Within the insurance company, there is an atmosphere of wanting to promote new whole life insurance product names to fill the void left by the suspended '700 Whole Life' sales.
On the other hand, Samsung Life and Heungkuk Life view the market without the '700 Whole Life' as an opportunity. Since these two companies did not offer the '700 Whole Life,' their whole life insurance sales had been relatively less active compared to competitors that promoted it. However, they judge that with the disappearance of competing products, they can target the market with differentiated offerings.
A senior official at a major life insurer noted, "In reality, whole life insurance structures are similar, so we did not conduct separate promotions, but companies that had not offered the '700 Whole Life' found it difficult to sell whole life insurance." The official added, "With the suspension of '700 Whole Life' sales, they see it as an opportunity and are actively engaging in sales operations."
Life insurers have also become sensitive as performance has diverged significantly depending on whether they sold the '700 Whole Life.' In particular, there have been successive cases where competitors or GAs reported similar products to financial regulators. Indeed, Oriental Life's '5x More Happy Whole Life Insurance' and other products continued to be sold even after the '700 Whole Life' sales were suspended on the 21st of last month, but recently, financial regulators classified them as similar products and halted their sales.
The life insurance industry is currently grappling with developing alternative products to the '700 Whole Life.' An industry official said, "Currently, life insurers are carefully reviewing product development while watching each other's moves." The official added, "It is an ambiguous situation where no one wants to be the first to step forward, but in any case, new products that comply with regulatory intent and provide retirement benefits will be launched."
 in FINANCE
