

#. Recently, a prominent domestic law firm held multiple business briefing sessions at local insurance agencies (GAs). This is to recruit GAs not only in the capital region but also in local areas as law firm clients for consulting and litigation representation. As GAs have grown into super-large entities with annual sales reaching trillions of won, they have become a new market for law firms, alongside financial institutions such as banks and insurance companies.
#. Inka Financial Services, a KOSDAQ-listed company, conducts annual overseas travel promotions for its top-performing insurance agents. Top agents receive the highest level of treatment while traveling abroad on chartered flights. One insurance company CEO has even invited representatives of GAs that primarily sell the company's products to join him on an overseas trip. This demonstrates how much the status of GAs has risen.
With the number of agents affiliated with GAs surpassing 300,000, they have established themselves as 'super-gab' (super-bosses) to insurance companies. GAs with annual sales exceeding 1 trillion won are also emerging one after another. As the status of GAs has risen dramatically, the dependency of insurance companies on their channels has become serious. Insurance companies pay tens of trillions of won in annual sales commissions to GAs but cannot refuse their unreasonable demands. The financial authorities have no means to penalize illegal acts by super-large GAs and cannot impose severe penalties such as suspension of operations.
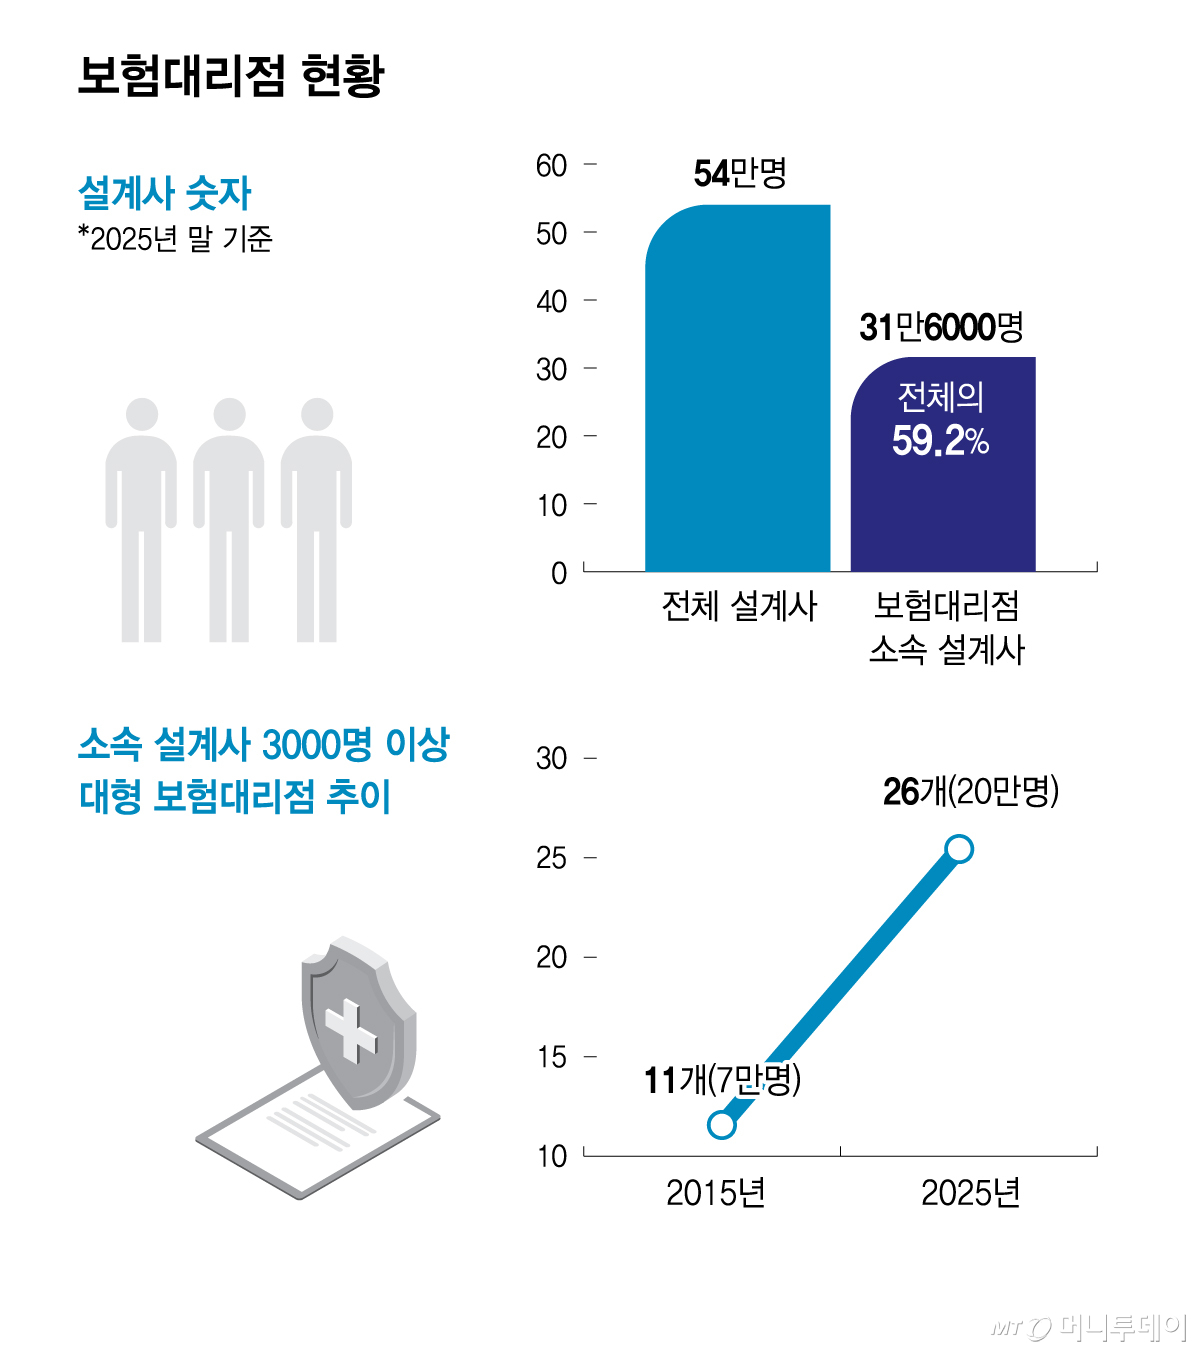
According to the insurance industry on the 22nd, as of the end of last year, there were 540,000 insurance agents, of which 310,000 belonged to GAs. More than half, or 59.2%, are affiliated with GAs rather than specific insurance companies and handle products from multiple insurers.
GAs are becoming super-large. The number of GAs with over 3,000 affiliated agents increased more than twofold from 11 in November 2015 to 26 by the end of last year. The number of agents belonging to these agencies also grew from 70,000 ten years ago to 200,000 last year. There are approximately 4,000 GAs in total, and more than half of them are large GAs with over 500 affiliated agents. Without GAs, the sale of insurance products would effectively come to a complete stop.
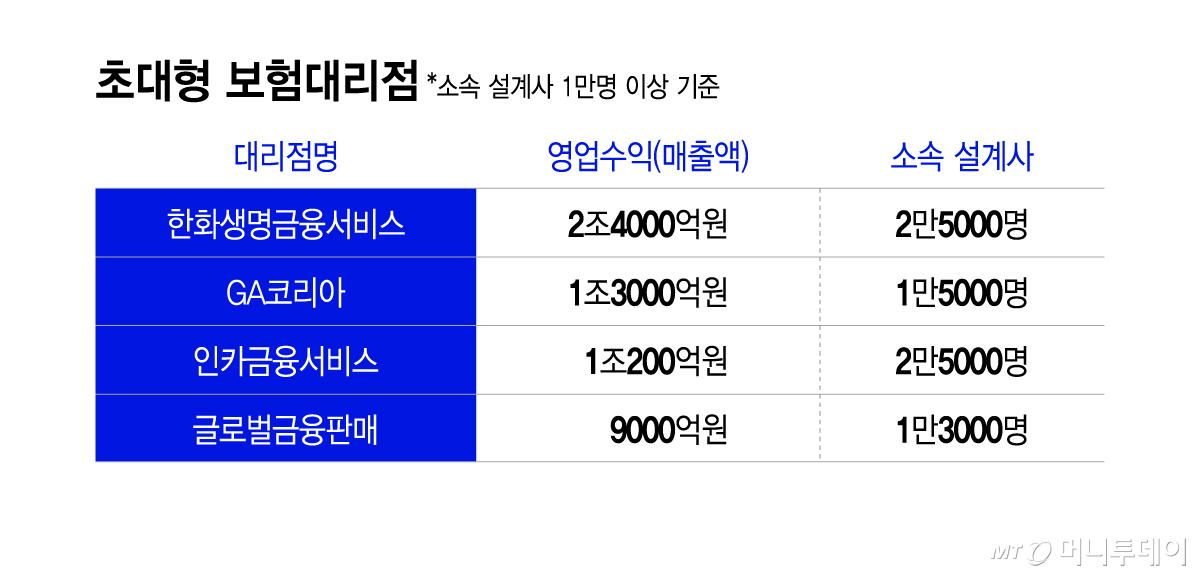
Super-large GAs with over 10,000 affiliated agents include Hanwha Life Financial Services (25,000 agents), GA Korea (15,000 agents), Inka Financial Services (25,000 agents), and Global Financial Sales (13,000 agents). Given that exclusive agents for small and medium-sized insurance companies number at most 2,000 to 3,000, GAs already possess influence surpassing that of insurance companies. In fact, the annual sales of super-large GAs reach 1 trillion to 2 trillion won. Notably, Inka Financial Services saw its sales surge from 119.6 billion won in 2015 to nearly 1 trillion won (1.0218 trillion won) last year.
Despite GAs surpassing insurance companies in scale, the financial authorities have virtually no effective means of penalty. The Financial Supervisory Service determines penalties for GAs based on the ratio of claims incurred to sales volume according to inspection and penalty regulations. If this ratio is less than 1%, a warning is issued; if it is between 1% and less than 2%, operations are suspended for one month; if it is 2% or more, operations are suspended for two months. Even when GAs commit serious illegal acts such as improper fund transfers or false contracts, their massive sales volume makes it impossible to impose severe penalties. Recently, a GA that received a heavy penalty of 5.3 billion won in fines for false contracts avoided suspension of operations due to its large total sales volume.
More seriously, as the influence of GAs grows, the burden of recruitment commissions for insurance companies is swelling like a snowball. Insurance companies executed a total of 32 trillion won in recruitment commissions last year, recording an all-time high. Particularly, insurance companies with weak own channels have intensified their dependency on GA channels. They must unhesitatingly bear the high-level commissions demanded by GAs. Even major life insurance companies struggle to meet GA demands despite spending more than twice the scheduled business expenses. Some insurance companies have even paid sales commissions exceeding 30 times the monthly premium.
Unable to stand idly by, the financial authorities applied a '1200% rule' starting in July last year, prohibiting sales commissions from exceeding 12 times the monthly premium for GAs. However, loopholes were opened where economic benefits are provided in disguise, such as covering office interior costs instead of paying cash directly to agents or boosting sales through companies indirectly related to GAs.
An insurance industry official stated, "It is difficult to refuse requests for sponsorship under the guise of accompanying them on overseas trips or Jeju Island trips, or when they demand attendance at GA annual award ceremonies." Another official lamented, "GAs even demand that we develop products with specific coverage terms they want. If we comply, the loss ratio becomes severe, leaving us unable to act either way."
This is why there are calls for creating penalty standards commensurate with the changed status of GAs and establishing fundamental measures to prevent excessive business expense execution. Insurance companies also diagnosed that "if we continue spending recruitment commissions like this, everyone will face mutual destruction" and "we have reached a point where we cannot stop on our own unless someone applies the brakes."

 in FINANCE

