

Lotte Insurance, on the verge of joining the Shinhan Financial Group, is set to improve its financial structure through a share cancellation without consideration. The company plans to reallocate capital without external capital inflow to resolve the shortfall in surrender value reserves and expand core capital.
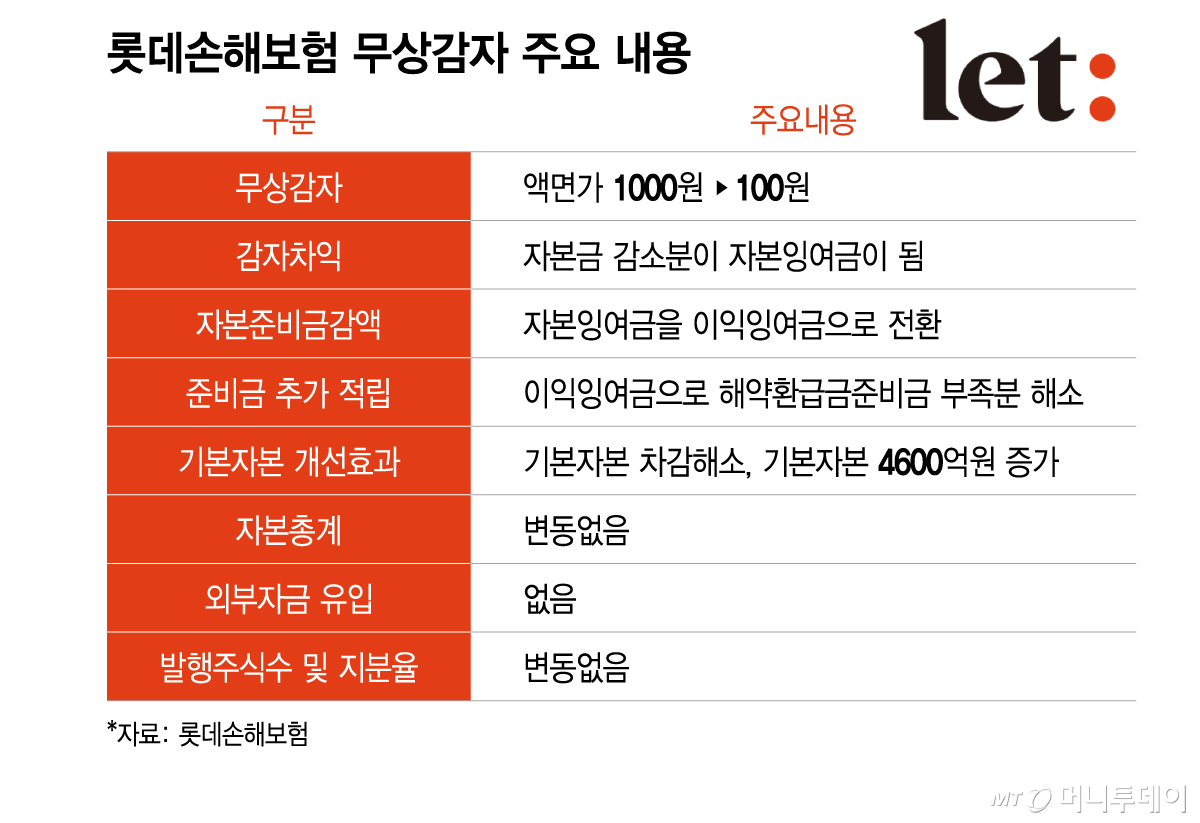
According to financial industry sources on Thursday, Lotte Insurance disclosed that it will proceed with a share cancellation without consideration using the "10-to-1 par value reduction" method, lowering the par value from 1,000 won to 100 won.
In this type of share cancellation, the number of issued shares and total capital remain unchanged. There is also no change in the number of shares held or ownership ratio for each shareholder. After the completion of the share cancellation without consideration, trading is expected to resume based on the closing price from the day before the trading suspension.
Lotte Insurance plans to use the gain from the share cancellation to additionally accrue surrender value reserves and increase the recognized amount of core capital through subsequent procedures.
This measure aims to respond to core capital-related regulations scheduled for introduction next year, while also improving financial soundness ahead of its inclusion in Shinhan Financial.
Surrender value reserves refer to reserves separately accrued within retained earnings to protect policyholders. They are calculated considering factors such as the difference between surrender values payable upon contract termination and accounting insurance liabilities.
This share cancellation without consideration is interpreted as a measure to reduce the burden of core capital deduction arising from insufficient accrual of surrender value reserves.
Until now, Lotte Insurance has struggled to accumulate necessary reserves due to a lack of retained earnings. The shortfall in unaccrued reserves is deducted from core capital according to supervisory standards.
To resolve this, it must first secure the capacity to accrue retained earnings. This is because paid-in capital or capital surplus cannot be directly accrued as surrender value reserves.
To utilize existing capital for reserve accrual, Lotte Insurance will transfer the gain from the share cancellation without consideration to retained earnings. First, the reduced paid-in capital due to the par value reduction will be reflected in capital surplus through the share cancellation gain.
Subsequently, it plans to transfer this to retained earnings through a capital reserve reduction procedure and use it as a resource to additionally accrue surrender value reserves. In this case, the burden deducted from core capital will also decrease.
Lotte Insurance expects that upon completion of the relevant procedures, the reserve shortfall will be largely resolved and the recognized amount of core capital will increase by approximately 460 billion won.
It believes this will expand its capacity to respond to core capital-related regulations scheduled for introduction next year. The company is determined to alleviate market concerns about financial soundness through stable core capital.
A Lotte Insurance official said, "Starting with this share cancellation without consideration, we plan to continue subsequent soundness improvement measures in accordance with the business improvement plan," adding, "We plan to mitigate structural constraints such as insufficient reserve accrual and enhance financial soundness by linking it with additional capital expansion by future acquirers."

 in FINANCE
