

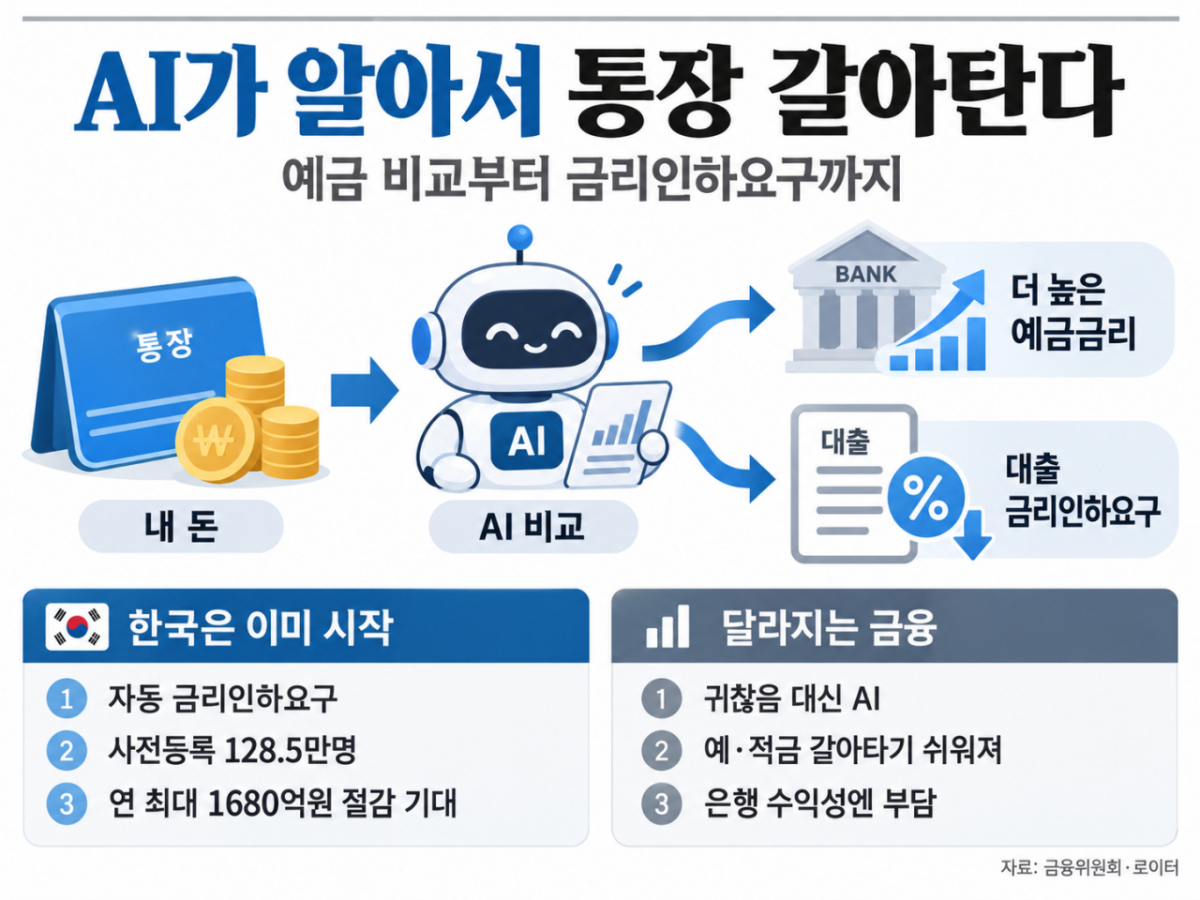
Even if money is sitting idle in a bank account, few people switch deposits to find higher rates every time. This is because the process of comparing rates, opening an account, and transferring funds is a hassle. AI (artificial intelligence) has begun to eliminate this "hassle." A "financial secretary" that monitors your account balance, interest rates, and loan terms 24 hours a day is emerging. It goes beyond simply notifying you when a more favorable product appears; it directly transfers money or applies for rate reductions.
Recently, Reuters reported that the spread of AI agents could pose a new threat to banks. This is because if AI continuously compares financial products on behalf of customers, money sleeping in low-interest accounts can quickly move to places offering higher rates. From the banks' perspective, this means a decrease in cheaply secured deposits and a situation where they must pay higher interest.
Even when there are products with higher rates, a significant number of customers do not switch their transaction bank. This is due to the inconvenience of having to reconnect salary transfers, card payments, and utility bills. AI is different. It can compare the terms of dozens of financial institutions daily to find higher rates and bring back only the necessary funds to the deposit account just before payment dates.
McKinsey analyzed that out of approximately $70 trillion in global consumer deposits, $23 trillion is held in demand deposits with little to no interest. It estimated that if even 5% to 10% of this amount moves to high-interest products with the help of AI, banks' deposit-related profits could decrease by more than 20%.
Some use the term "agentic bank run." This is different from a traditional bank run, where people withdraw money all at once because they judge a bank to be risky. It means that as numerous AIs each find the highest rate for their respective customers, funds can end up moving simultaneously as a result.
For consumers, this is a welcome change. This is because AI continues to move in the direction of receiving higher deposit rates and paying lower loan interest. In Korea, an early form of this has already become reality.
The Financial Services Commission has been implementing the "MyData-based interest rate cut request service" since February 26. With a single consent, MyData operators such as Naver Pay, Kakao Pay, Toss, and Bank Salad automatically request financial institutions to lower loan rates on behalf of consumers. Regular applications are possible up to once a month, and additional applications can be made if income increases significantly or credit scores rise.
Before the service launched, there were 1.285 million pre-registered users. The Financial Services Commission estimated that as the service becomes active, individuals and sole proprietors could save an additional up to 168 billion won in interest annually. The money consumers save is equal to the banks' decreased revenue.
Currently, domestic services are at the stage of automatically requesting lower loan rates. It is not yet common for AI to arbitrarily cancel deposits and move them to other banks.
However, the direction is clear. The Financial Services Commission also announced a plan in August to develop MyData from a service that simply displays assets on one screen into a "My AI agent" that acts on behalf of users.
If AI can simultaneously compare deposits, loans, and card benefits, the way financial institutions compete will change. It becomes difficult to expect customers to stay just because it is a hassle. If low deposit rates or high fees are maintained, AI can immediately find better products.
The most demanding customer banks will have to deal with in the future may not be human. An era is coming where AI that searches 24 hours a day for places offering even one won more manages your bank account.

 in TECH
