

Virtual asset taxation, commonly referred to as the 'coin tax,' is scheduled to begin in January next year, if all goes according to plan. However, that 'plan' has already been changed several times.
The decision to tax virtual assets was made in 2020. At the time, the Ministry of Economy and Finance expressed the view that taxation needed to be implemented as soon as possible to minimize the gap in taxation. On the other hand, there were also opinions that more time was needed to build the taxation infrastructure.
Accordingly, it was decided that virtual asset taxation would take effect from January 2022. However, even in 2021, on the eve of implementation, the taxation infrastructure had not been properly established, and the timing was postponed once to January 2023. From then on, decisions to postpone virtual asset taxation became a recurring theme.
In 2022, the taxation schedule was postponed again to January 2025. This was a period when uncertainty in the virtual asset market had grown due to incidents such as the Luna and Terra crashes, and the need for investor protection was being emphasized.
There were also discussions about postponement in 2024, intertwined with debates over the abolition of the Financial Investment Income Tax (hereinafter referred to as the FIIT). Ultimately, the timing of virtual asset taxation was postponed to January 2027. There have been a total of three grace period or postponement decisions made so far. However, there are no concrete moves toward a further grace period at this time.
The Ministry of Economy and Finance, which is in charge of tax policy, maintains its position that it will proceed with virtual asset taxation as scheduled starting next year. Former Deputy Prime Minister and Minister of the Ministry of Economy and Finance Koo Yun-cheol stated in the National Assembly last July, "We will first implement it next year and push forward in a direction to supplement any necessary parts."
Deputy Prime Minister and Minister of the Ministry of Economy and Finance Lee Hyung-il also stated in his written response submitted during his confirmation hearing as a candidate, "It is desirable to implement taxation from 2027 as scheduled, in accordance with the basic tax principle that 'where there is income, there should be taxation.'"
Contrary to the government's position, concerns about virtual asset taxation remain. Issues such as loopholes in the system and limitations of the taxation infrastructure are being highlighted.
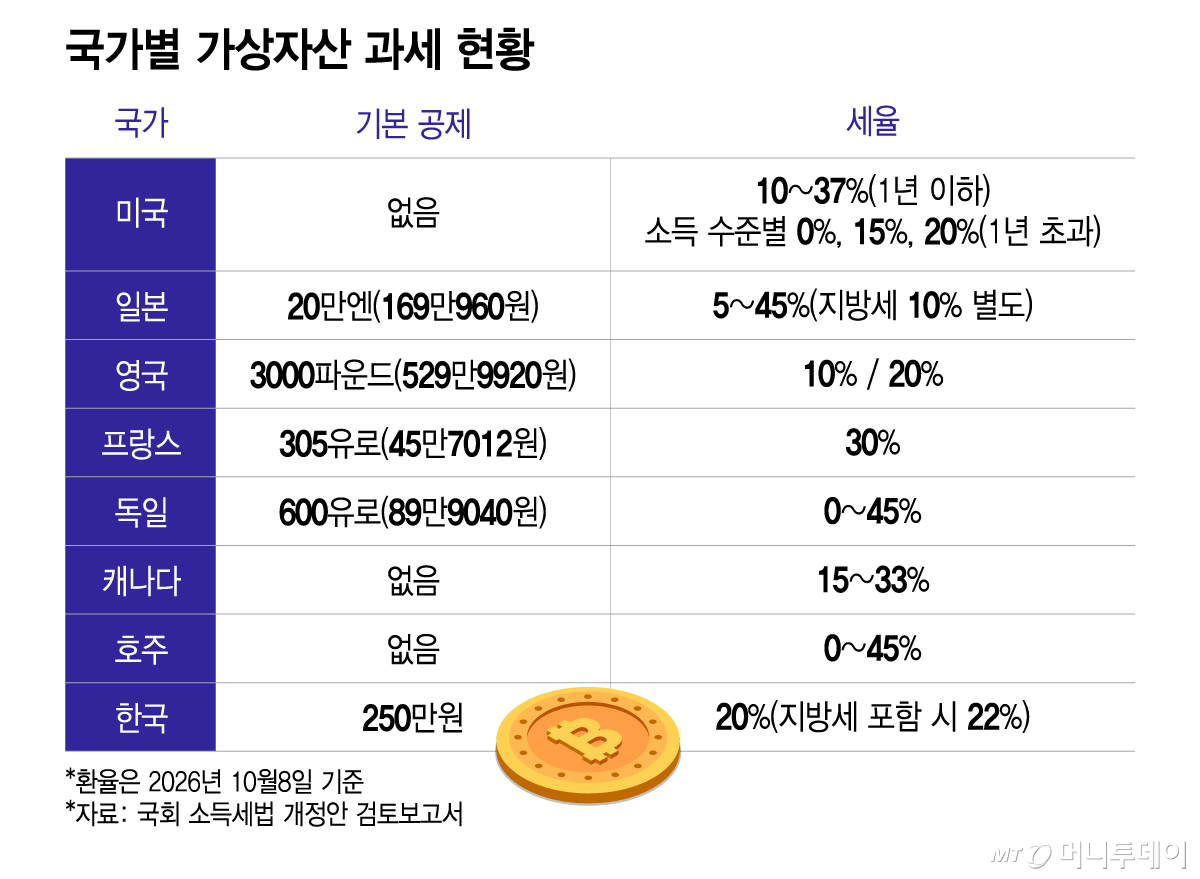
According to the Income Tax Act, the taxable objects for virtual assets are income generated from transfers and lending. Virtual asset income of 2.5 million won or less per year is not taxed. For income exceeding that amount, a deduction of 2.5 million won is applied, and taxation is imposed at a tax rate of 20% (22% including local taxes).
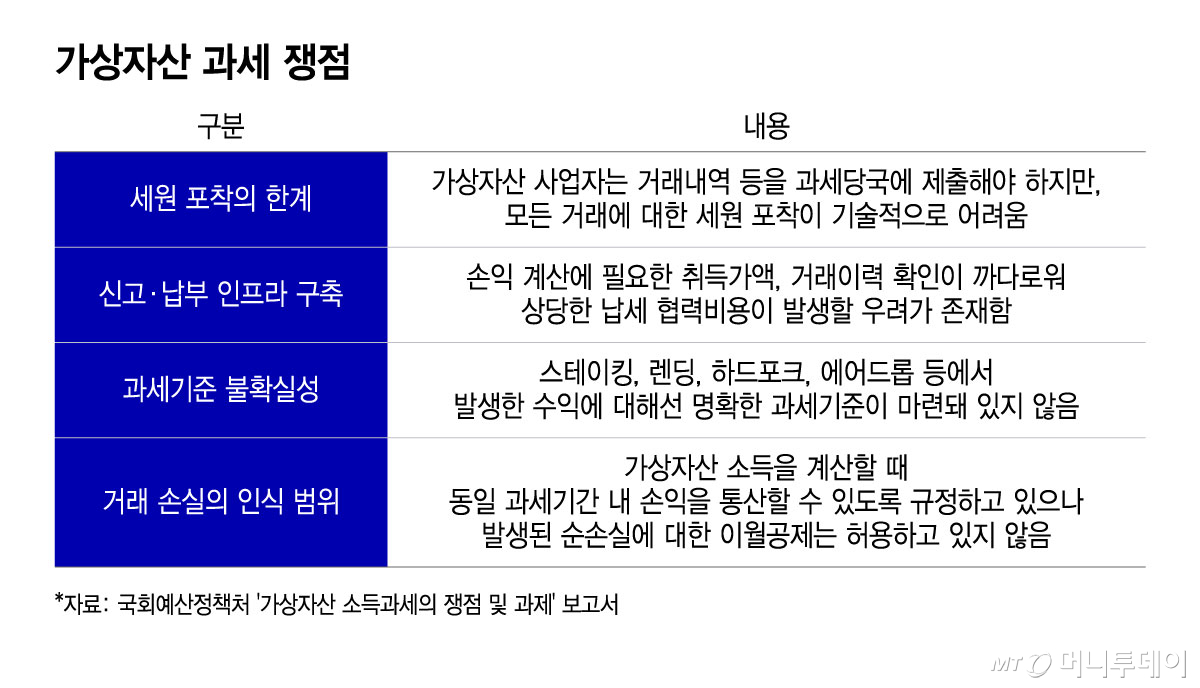
In particular, virtual asset income is classified as miscellaneous income, meaning that losses are not eligible for carryforward deductions. This means that past losses cannot be deducted from profits in the following year.
For example, if an investor incurs a loss of 10 million won this year and earns a profit of 5 million won next year, they have suffered a total loss of 5 million won, but taxation will still be applied to the 5th million won profit earned next year.
The relationship with the FIIT is also cited as an issue. The FIIT is a tax levied on investors at a rate of 20% (25% for amounts exceeding 300 million won) on the portion of profits from financial investments such as stocks, bonds, and funds that exceeds 50 million won per year. The FIIT, which was scheduled to be introduced in 2023, has been finally decided not to be implemented.
Kim Woo-cheol, President of the Korean Society for Public Finance (Professor at University of Seoul), said, "The FIIT has been abolished, yet only virtual assets are slated for taxation, creating a situation where the fairness of policy is compromised." He added, "I expect the government will have no choice but to postpone [the taxation timing] due to backlash from younger demographics who invest in virtual assets."
Concerns regarding the taxation infrastructure also exist. The National Assembly Budget Office stated in a report released last month, "Because there is no clear reporting entity for decentralized transactions and over-the-counter trades, there may be limitations in the tax authority's ability to grasp all transactions and impose taxes."
The blind-spot issue regarding overseas transactions is expected to be resolved to some extent by the 'Common Reporting Standard for Virtual Assets' (CARF), which will be implemented starting next year. However, concerns over misalignment remain, as 29 countries including Canada, Switzerland, Singapore, and Hong Kong are set to begin their first information exchange in 2028, while the United States is scheduled to start in 2029.
Oh Moon-sung of Han Yang-yeo-dae (Prof.) stated, "There are many loopholes due to the situation where each country participates in different years." He added, "Many investors have moved to Binance, an overseas exchange located in the United Arab Emirates, and investors are also preparing for tax avoidance."
Seemingly mindful of this situation, Deputy Prime Minister Lee also stated during a National Assembly audit on the 6th, "I think we will broadly gather opinions regarding various interests," expressing a stance different from the past.

 in ECONOMY

