
The ripple effects of the sales suspension for '700-type whole life insurance' (hereinafter 700-type) are spreading across the entire life insurance industry. The shock is particularly severe for small and mid-sized life insurers that had a high degree of reliance on this product. General agents (GA, corporate insurance agencies), which had expected high commissions, have begun seeking new sales products such as dollar-denominated insurance, moving to restructure their portfolios.
According to the insurance industry on the 5th, GAs and life insurers are actively exploring alternative products such as dollar-denominated insurance following the sales suspension of the 700th-type. Small and mid-sized life insurers, including iM Life, Fubon Hyundai Life, and DB Life, which are known to have relied on the 700th-type for 70% to 80% of their total sales performance, face significant difficulties as they lack a suitable alternative.
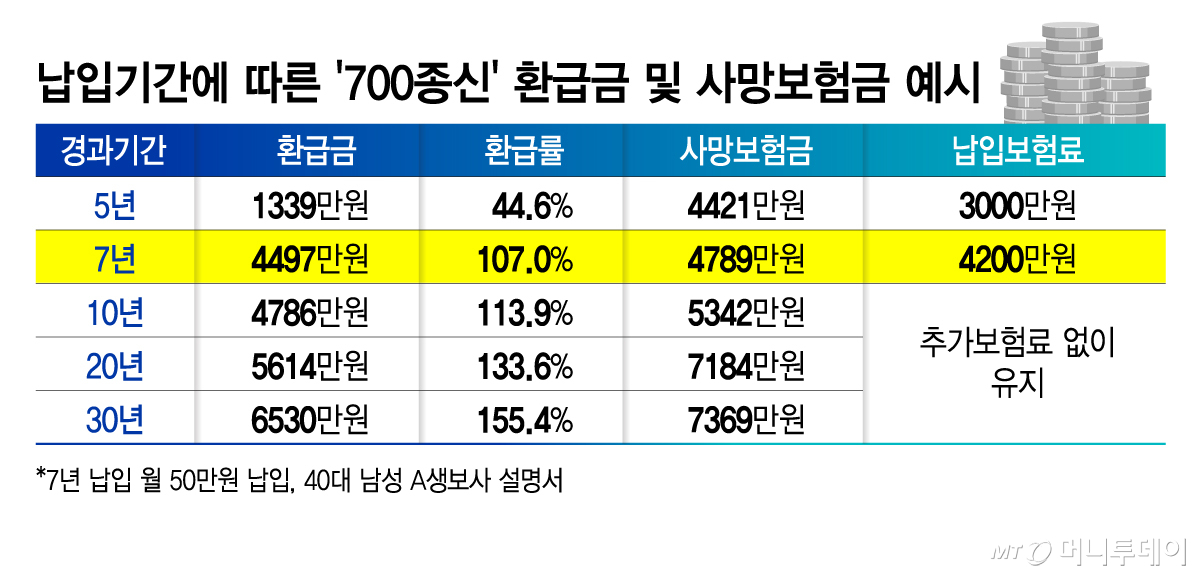
The 700-type is a product designed to allow policyholders to receive a 100% refund after paying premiums for a set period, such as seven years. It gained popularity in the market because it allows premiums paid over a short period to be returned earlier, while also adding the coverage function of whole life insurance. The earned premiums from 7-year refund-type whole life insurance sold by 12 life insurers last year reached 950 billion won, more than tripling compared to 310 billion won in the previous year. However, new sales were suspended starting on the 21st of last month after financial regulators expressed concerns over cancellation rates higher than insurers had anticipated and the possibility of incomplete sales practices.
Insurers have voiced dissatisfaction, stating that sales were halted without giving them time to prepare alternative products. On the other hand, financial regulators maintain that the measure was necessary to prevent clearance marketing ahead of the sales suspension and the resulting consumer harm. Consequently, small and mid-sized life insurers, which have relatively weak in-house sales bases, are increasingly concerned about performance gaps as they struggle to find products capable of replacing their main offering.
A source at a life insurer said, "Large life insurers may face relatively smaller impacts because their product portfolios are more diverse." The source added, "In contrast, it is no exaggeration to say that small and mid-sized insurers have been selling only the 700th-type recently, making it difficult for them to easily find a product to replace immediate performance."
Confusion among GAs and insurance agents is also growing. Because the 700th-type involves large premiums per policy, it has become a key sales product for GAs and agents due to the ease of securing commission revenue. For example, in the case of a product with a monthly premium of 500,000 won, simply applying the cap under the so-called '1200% rule' results in commissions reaching up to 6 million won. With the sales of their main product suspended, concerns over reduced income for GAs and agents are also rising.
One alternative product attracting attention from GAs is dollar-denominated insurance. This is a product where premiums are paid in US dollars and insurance benefits are received in US dollars. Recently, as signs indicate that the US base rate may be raised, major life insurers are once again promoting dollar-denominated insurance. It offers whole life insurance functions, such as death benefits, allowing policyholders to hold dollar assets with low exchange rate risk. In particular, during periods of rising interest rates, insurers invest in US Treasury bonds and other assets with higher yields, enabling expectations of higher refund rates. Many policyholders typically pay between 200 and 1,000 dollars (approximately 280,000 to 1.4 million won) per month.
A source at a large GA said, "The sales suspension of the 700th-type has put GAs in a situation where they must find new sales products." The source added, "As the scale of monthly premiums is large and interest in dollar-denominated insurance grows, field agents are also making efforts to expand the sale of related products."
 in FINANCE
