
Samsung Electro-Mechanics is expected to see its third-quarter operating profit surge more than twofold year-on-year, driven by expanding demand for MLCCs (multilayer ceramic capacitors) and semiconductor packaging substrates FC-BGA (flip chip ball grid array) for AI servers. Continued supply shortages of high-value-added components for AI servers are driving earnings growth through price increases and improved product mix.
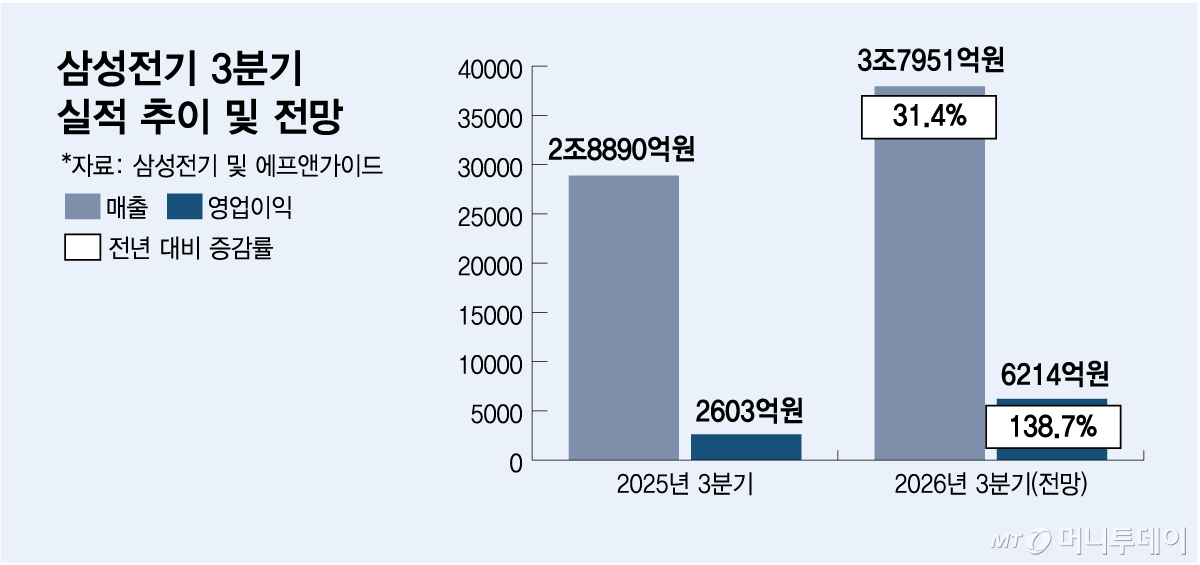
According to financial data provider FnGuide on the 16th, Samsung Electro-Mechanics' projected operating profit for the third quarter this year is 621.4 billion won. This represents a 138.7% increase from the same period last year (260.3 billion won) and a 41.1% increase from the previous quarter (440.4 billion won). The projected revenue is 3.7951 trillion won. Samsung Electro-Mechanics is scheduled to announce its third-quarter earnings on the 28th.
The component division, responsible for MLCCs, is leading the strong performance. As AI servers require higher computational performance and power consumption, demand for high-capacity and high-reliability MLCCs has surged, but production capacity remains limited. Samsung Electro-Mechanics' MLCC production line utilization rate is estimated to have reached the high 90% range. Murata Manufacturing Co., Ltd., the world's number one manufacturer, is also considering additional expansion beyond its existing investment plan of 80 billion yen. Murata's book-to-bill ratio has recently approached 1.5, indicating that new orders are growing faster than production volume, with new orders reaching approximately 150 yen for every 100 yen in shipments.
This supply shortage is contributing to Samsung Electro-Mechanics' pricing power and profit expansion. As the sales share of MLCCs for AI servers, which command higher unit prices than general products, expands, an increase in average selling price (ASP) is also expected. KB Securities estimated that the operating profit margin of the component division will rise from 11.7% in the first quarter this year to 22% in the third quarter. This reflects a structure where profit margins are rising due to a combination of mix improvement centered on high-priced products and price increases, effectively under full-capacity operation.
The package solution division, responsible for FC-BGA, is also expected to support earnings based on its high profitability. A supplier-favorable market continues as demand grows for high-layer-count and large-area substrates used in high-performance semiconductors for AI accelerators and servers. Kiwoom Securities estimated the operating profit margin for FC-BGA in the third quarter at 32%. High-specification substrates have complex manufacturing processes and large areas, making it difficult to expand supply in the short term. Samsung Electro-Mechanics' decision last month to invest a total of 6.78 trillion won in its domestic Sejong plant and Vietnamese production subsidiary is also aimed at responding to medium- and long-term demand. Among these, the Sejong plant targets Yangsan by September 2028. The effects of this expansion are expected to become visible from the second half of 2028.
However, the strengthening of the won is a variable. Samsung Electro-Mechanics' export ratio in the first half of this year reached 97%, meaning that if the won-dollar exchange rate falls, the won-denominated value of overseas revenue could decrease. Nevertheless, the securities industry is paying more attention to upward revisions in earnings due to rising unit prices for AI components and the expansion of high-value-added products, despite the burden from exchange rates.
Kwon Min-gyu, a researcher at Kiwoom Securities, analyzed, "The fact that earnings estimates are being revised upward despite falling exchange rates means that the supplier-favorable market is continuing," adding, "Samsung Electro-Mechanics benefits greatly from the AI investment cycle by operating both MLCC and FC-BGA businesses simultaneously."
 in INDUSTRY
