

Despite the rapid growth of insurance agencies (GAs) as a core sales channel for the insurance industry, their internal controls and sales accountability have failed to keep pace. Recently, personal information leaks caused by hacking incidents have also occurred. If GAs face sanctions, they can simply 'close down' and re-register, reducing the effectiveness of sanctions. This is why there are calls to change GA registration from a licensing system to a permit system and prevent indiscriminate dual operations.
According to the insurance industry on the 22nd, problems with GAs selling various insurance products were also mentioned by President Lee Jae-myung. During his presidential candidate days, President Lee stated via social networking services (SNS), "Because GAs focus solely on sales, they neglect complaint handling and other areas, leaving them ill-equipped to manage damages suffered by insurance consumers." He added, "For GAs of a certain scale, we will make liability real by requiring insurance companies to bear joint responsibility for consumer damages, thereby curbing illegal operations."
However, despite President Lee's criticism, GA problems persist. Sixty-seven designers affiliated with PS Fine Service were caught by the Financial Supervisory Service (FSS) after facilitating loans totaling 111.3 billion won from 415 policyholders to lending companies. The designers approached fresh graduates by promoting financial planning or salary management study groups unrelated to their core business of insurance sales, urging illegal loans with promises of returns around 20% annually and principal guarantees. These were not formal financial investment products but contracts to borrow money from lending companies.
Incidents continue at GAs under major financial groups. At Hanwha Life Lab and Shinhan Financial Plus, a so-called 'cutting' practice became problematic: approaching customers by offering consultation and consulting on policy funds available for SMEs (small and medium-sized enterprises), then inducing insurance purchases in exchange for securing the loans. This is an example of GAs exploiting the fact that there are no restrictions on dual operations to secure insurance contracts using 'bait' such as policy funds.
Even more unusual cases emerged in corporate insurance sales. A GA approached a nursing home institutional investor by proposing tax and accounting consulting, then had the corporation purchase whole life insurance under its name. Subsequently, the policyholder was changed, inducing the representative (CEO) to take the surrender value for personal use. Essentially, insurance was used as a conduit to move funds from the nursing home into whole life insurance and then withdraw them as the CEO's personal funds. Tax accountants also participated in such incidents in large numbers. This is because recruitment commissions generated by selling hundreds of millions of won worth of whole life insurance per case far exceed earnings from tax services. For example, selling a monthly premium policy worth 2 million won can yield an initial commission of up to 24 million won. This explains why tax accountants posed as insurance designers.
GA's lax internal controls also raise significant concerns about personal information leaks. In fact, incidents occurred where personal information of over 1,100 individuals, including customers and designers, was leaked from U-Future Insurance Marketing and Shinhan Financial Find due to reasons such as malware infection. Sensitive contract details, including insurance types, insurance companies, policy numbers, and premiums, were exposed one after another, intensifying anxiety among policyholders.
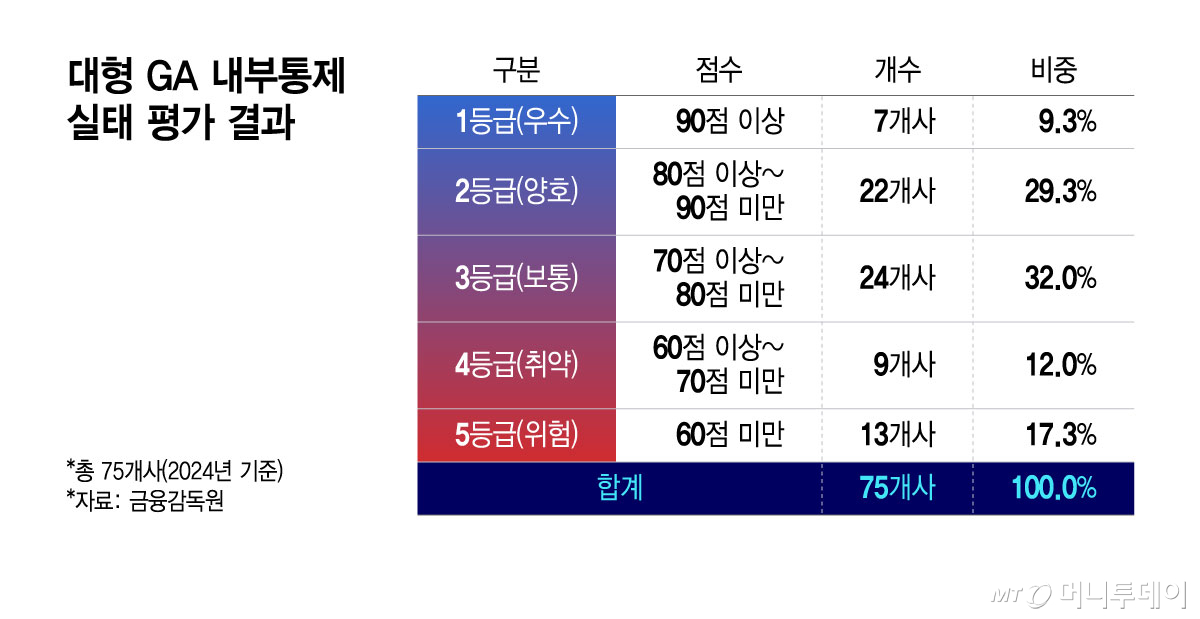
Although financial authorities have repeatedly urged GAs to strengthen internal controls, vulnerabilities remain. In the 2024 FSS assessment of internal control status at major GAs, the proportion of vulnerable GAs rated 4 or 5 reached 29.3%. This revealed a structural problem where, despite the growth of designer organizations, it is difficult for headquarters to real-time control the sales activities of frontline designers.
An insurance industry official stated, "Major GAs have grown to such an extent that they virtually lead the sale of insurance products, but when incidents occur, they are mostly resolved as issues involving individual recruiters or branch offices." The official added, "Since they operate by closing down their corporations and re-registering, the effectiveness of sanctions is diminished."
In fact, in 2020, Leaders Financial Sales received an operational suspension from the FSS due to false contracts and improper conversions. However, while the FSS investigation and sanctions were underway, thousands of affiliated designers moved en masse to new GAs under different names. Leaders Financial Sales and its special affiliates simply put up a new sign and continued operations; there is no way to stop them once they register their business and open an office.

 in FINANCE
