
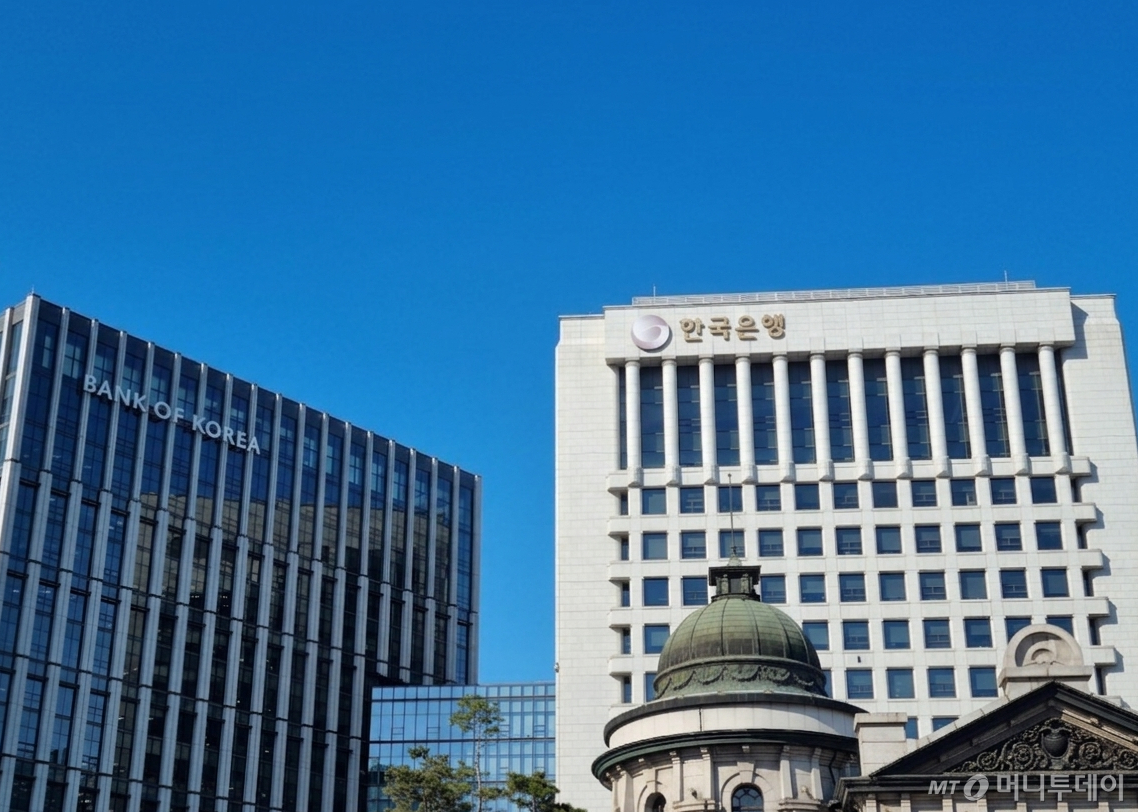
The Bank of Korea plans to shift approximately $1 billion of its foreign assets, currently entrusted to domestic asset management firms, from developed-market stocks to global bonds.
With a sharp surge in private overseas stock investments reducing the need for policy support in stock management, the central bank aims to enhance the qualitative capabilities of domestic asset managers by focusing on high-difficulty global bonds going forward.
On the 16th, the Bank of Korea announced it will reduce the scale of developed-market stock passive funds entrusted to domestic asset managers and expand overseas bond mandates. The existing "U.S. Aggregate Bond" strategy will be transitioned to a "Global Aggregate Bond" strategy with significantly broader investment scope across countries, currencies, and securities.
Currently, foreign assets entrusted to domestic asset managers total $3.21 billion. This includes $1.92 billion in developed-market stock passive funds, $700 million in U.S. aggregate bonds, and $590 million in Chinese stocks.
Specifically, the central bank plans to redirect approximately $1 billion of the stock funds managed by three domestic asset managers into bonds.
A Bank of Korea official stated during a briefing on the day: "We plan to work with about three firms and aim to transfer around $1 billion in total from stocks to bonds." The official added, "The final amount may vary depending on negotiations with these companies."
However, the overall stock-to-bond ratio of the Bank of Korea's foreign assets will remain unchanged. Stock funds recovered from domestic asset managers will be transferred to overseas managers, while the proportion of bonds managed by domestic firms will increase.
The official explained: "Adjustments will occur such that the share of overseas managers increases in stocks, while the share of domestic managers rises in bonds. There will be no change in the total stock and bond scale, nor any associated currency conversion or other fees."
This restructuring reflects the judgment that the self-sustaining capacity of the overseas stock market has grown substantially. The net inflow into domestic overseas-investment stock funds rose from 27.7 trillion won in 2020 to 163 trillion won as of June this year, while overseas stock-type ETFs surged from 1.6 trillion won to 126.3 trillion won over the same period.
A Bank of Korea official noted: "Stock-type passive funds have already grown significantly in scale within the private sector, so expanding support would yield limited policy effects. Instead, we aim to concentrate on areas with higher difficulty and lower private-sector demand to maximize policy impact."
Global aggregate bonds are more difficult to manage than U.S. aggregate bonds. While U.S. aggregate bonds cover approximately 10,000 securities in a single country, global aggregate bonds span about 30,000 securities across roughly 28 countries. Managing them requires simultaneous analysis of major economies' monetary policies, business cycles, and exchange rate fluctuations, demanding strong macroeconomic analysis and risk management capabilities.
The Bank of Korea also maintains its long-term target of allocating 10% of foreign assets to domestic asset managers. An official stated: "Although the proportion entrusted to domestic firms has stagnated in the high single digits due to declining foreign exchange reserves, if reserves stabilize and grow again, we will continue considering prioritizing allocations to domestic asset managers to approach the 10th% target."
The Bank of Korea views a minimum scale of $200 million to $300 million per asset manager as necessary for global bond management. An official said: "There is a view that global bonds require at least $200 million to $300 million to be practically managed in the market, and we plan to allocate such scales to each company."
Through this initiative, the Bank of Korea aims to enable domestic asset managers to build global management systems, overseas networks, and specialized personnel while accumulating performance records. An official remarked: "We do not expect the Bank of Korea's funds alone to accomplish everything; rather, we anticipate them serving as a catalyst." The official added, "Once track records are established, this can also lay the foundation for domestic firms to receive mandates from other institutional investors such as the National Pension Service."
 in ECONOMY
