

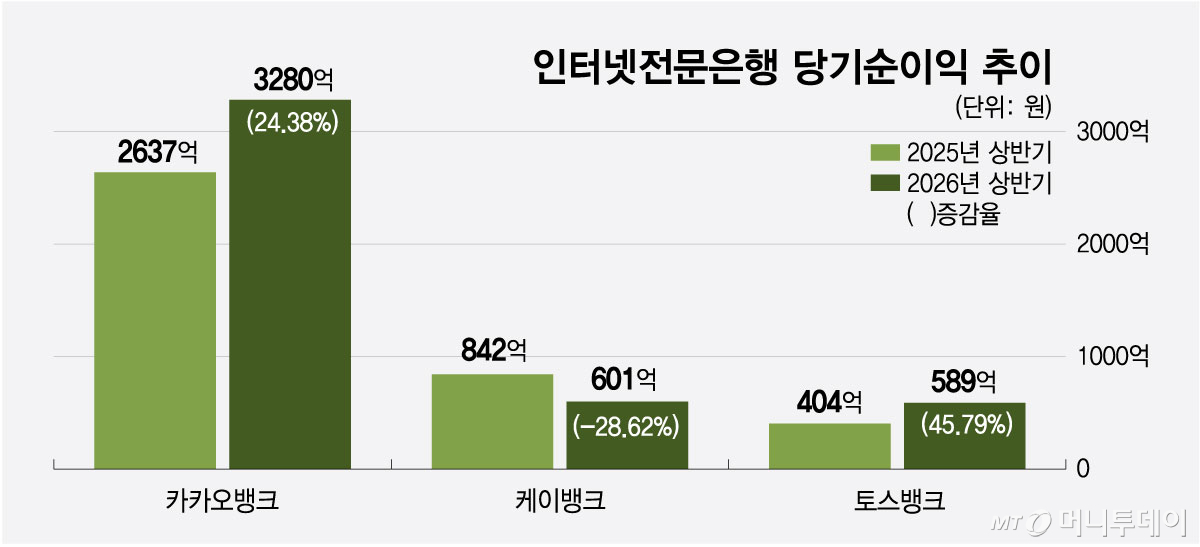
The combined net profit of the three internet banks rose by 15% compared to a year ago, though individual banks showed mixed results. KakaoBank and Toss Bank recorded their highest-ever semiannual profits, while K Bank saw its net profit shrink as last year's gains from bond sales disappeared this year.
According to financial industry data released on the 31st, the cumulative net profit of the three internet banks—KakaoBank, K Bank, and Toss Bank—for the first two quarters of this year totaled 447 billion won, marking a 15.1% increase compared to the same period last year.
KakaoBank, which secured first place, recorded a net profit of 328 billion won in the second half of the year, up 24.4% from the same period last year, setting a new all-time high. This growth was driven by increases in both interest and non-interest income. All categories of Yeosu Shin balances rose, with interest income increasing by 20.8%, primarily due to loans to individual business operators. Non-interest income, particularly fee-based earnings, surged by 92% thanks to increased usage of debit cards.
The gap between K Bank and Toss Bank, competing for second and third place, narrowed significantly. K Bank's net profit fell 28.6% year-on-year to 60.1 billion won, while Toss Bank's net profit grew by 45.8% to reach 58.9 billion won. As a result, the difference in net profit between the two companies shrank from 43.8 billion won in the first half of last year to just 1.2 billion won this year.
Market analysts note that as one-time factors supporting K Bank's performance have faded, its core business results are now more visible. The decline in K Bank's profit was largely due to a drop in non-interest income. While interest income rose by 19.6% year-on-year to 253 billion won, non-interest income fell sharply by 68.2% compared to the same period last year, reflecting reduced gains from loan bond sales that had boosted last year's results.
Meanwhile, Toss Bank succeeded not only in increasing interest income but also in significantly reducing losses in its non-interest segment. Interest income rose by 1.5% to 423.3 billion won. Non-interest losses dropped from 27 billion won in the first half of last year to just 3.5 billion won this year, thanks to increased cumulative sales of lump-sum investment services and higher debit card transaction volumes.
A financial analyst stated, "Toss Bank's growth in Yeosu Shin assets and core business performance is better than K Bank's," adding, "As Toss Bank was the first to enter individual business operator lending and has resolved its soundness issues, it can be seen as having overcome a significant portion of its losses."
Soundness management results also varied. KakaoBank's delinquency rate stood at 0.51% as of the end of the second quarter, down 0.01 percentage points (P) from the previous year, while its non-performing loan (NPL) ratio remained stable at 0.54%, similar to last year's level. Toss Bank's delinquency rate fell by 0.15 percentage points year-on-year to 1.05%, and its NPL ratio decreased by 0.07 percentage points to 0.91%.
In contrast, K Bank's delinquency rate rose by 0.01 percentage points to 0.60%, and its NPL ratio increased by 0.08 percentage points to 0.59%, indicating a deterioration in performance.
In terms of inclusive finance, all three banks met their targets. The share of credit loans provided to medium- and low-income individuals and individual business operators during the second quarter exceeded the target of 30% for the third consecutive time. Based on new transaction amounts, KakaoBank recorded 38.4%, Toss Bank 32.7%, and K Bank 32.4%. On a balance basis, Toss Bank led with 34.2%, followed by KakaoBank at 31.9% and K Bank at 31.2%.
However, as the overall lending scale expanded, performance declined compared to the previous quarter across all three banks. Based on new transaction amounts, KakaoBank's share of credit loans for medium- and low-income borrowers fell by 7.2 percentage points from the first quarter. Toss Bank saw a decline of 1.8 percentage points, while K Bank dropped by 1.2 percentage points compared to the prior quarter.

 in FINANCE
